
The original version of The Wealthy Barber was released in 1989, and has since become one of the best-selling books of all-time in Canada with over 2 million copies sold. Its cultural impact rivals that of Canadian literary classics like Margaret Atwood’s The Handmaid’s Tale and L.M. Montgomery’s Anne of Green Gables.
Personal finance books rarely capture mass appeal, but author David Chilton managed it through the relatable, conversational lessons from the wealthy Mr. White to mild-mannered Roy in his Sarnia barber shop. The sequel, The Wealthy Barber Returns, took a different approach in its 2011 release. Instead of his original characters, Chilton doled out advice by sharing his personal perspectives on money.
Timeless money lessons, reimagined for a new generation
The updated 2025 version of The Wealthy Barber was released on November 4 exclusively in Indigo stores and independent bookshops across the country. It has been completely re-written to include new realities of Canadian wealth building, like the Home Buyer’s Plan, tax-free savings accounts (TFSAs), and first home savings accounts (FHSAs). These additional account choices, along with new investment vehicles and the high cost of living, make it even more difficult to decide how best to pay yourself first. This is what makes the re-write even more relevant for a new generation of Canadians.
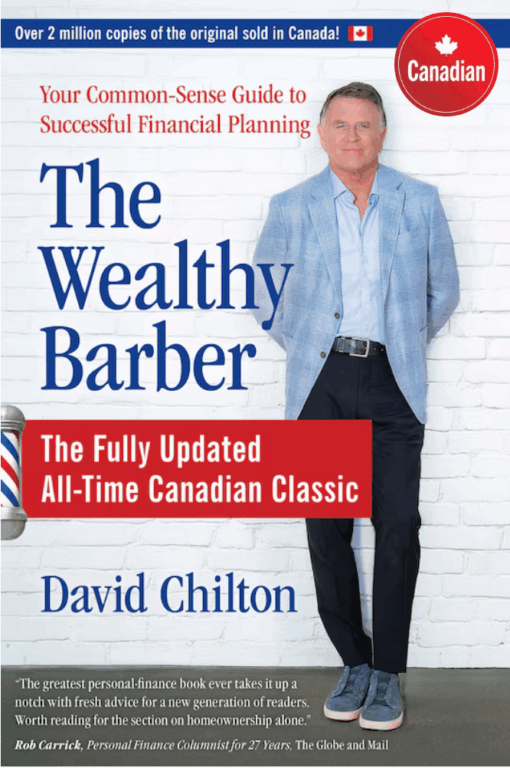
I spoke with David Chilton about the new edition. He said his motivation was to address the challenges that young people face today, from rising costs to new financial products. “The original book didn’t include ETFs or index funds,” he noted, “which are now common investment tools in Canada.”
I read the original book as a teenager, and while many Baby Boomers and older Gen-Xers may wonder if this re-write is for them, it is probably not. But it is for their kids and grandkids. According to Chilton, it targets “young adults in their 20s, 30s, and 40s, emphasizing passive investment strategies and basic financial principles like keeping costs low and paying oneself first.”
The broad appeal of the original book is probably due to the humour and relatable storytelling that simplifies complex financial topics. This helps readers feel less intimidated and more empowered. So, if you consider yourself less financially literate, the lessons will be easy to digest.
“Pay yourself first” still matters most
Chilton highlights the high cost of living, particularly housing, as making it tough for young people today to commit to regular savings. There is also the pressure of social media to spend on things that may feel like necessities but are not.
Saving has to be a necessity too, however, before making other financial commitments. In fact, when I asked Chilton for his most timeless lesson that remains relevant today, “pay yourself first” topped his list. He also highlighted the chapter in the updated book on saving savvy, which provides tips for managing daily finances to make sure there is money to set aside for the future. After all, you cannot invest if you cannot save.
Rankings
The best ETFs in Canada
Chilton expressed frustration with how much young people spend on cars despite the challenges of home ownership and rising living costs. But he gives them credit for recognizing the benefits of low-cost investment strategies, with younger generations becoming more fee-sensitive and aware of the impact of investment fees on their retirement accumulation.
One of the key messages from The Wealthy Barber is to “save and invest 10 to 15 per cent of all you make by paying yourself first.” For those who remember the 1989 original but regret not taking that advice, the good news is that it is never too late. “The best time to plant an oak tree was 20 years ago,” writes Chilton. “The second-best time is now.”
From book to podcast, Chilton’s message stays relevant
The Wealthy Barber update touches on budgeting, investing, real estate, wills, and life insurance, among other topics. The result is a series of personal finance lessons weaved into a series of fables.
Chilton has complemented the book with his new The Wealthy Barber podcast, featuring Canadian personal finance voices. He notes that “it has become a top business podcast in Canada, without monetization, while focusing on providing valuable financial information to a wide audience.”
The concepts in the book are timeless messages that stand the test of time, but the update makes it even more relevant. The appeal of the Chilton brand is that he is prescriptive with his advice while being genuine in his intentions. In a world where many young people learn questionable financial lessons from biased finfluencers, The Wealthy Barber is as good a source as any to guide a young person on their path to real financial independence.
Ask MoneySense
Have a personal finance question? Submit it here.
Read more from Ask a Planner:
- A 2025 update on return trust filings
- What happens if you sell real estate to family for $1?
- How to bridge the gap until an inheritance
- What to do when you get laid off
The post The return of The Wealthy Barber appeared first on MoneySense.