
Global Stock Rally Pauses As Gold, Silver Slide From Record High
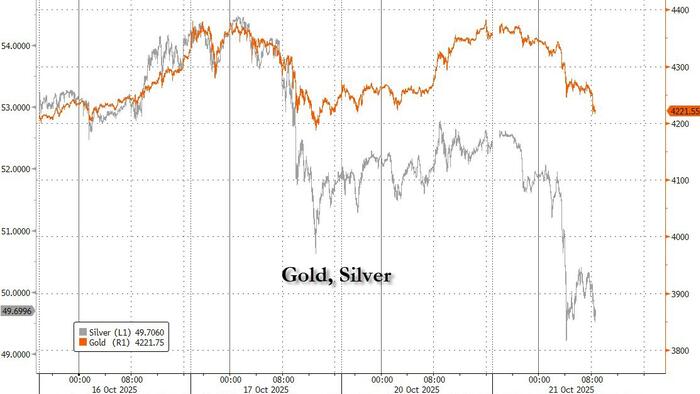
US equity futures are flat, reversing a small overnight loss, with small caps seeing some underperformance in what looks more like profit-taking than material de-risking. As of 8:00am ET, S&P and Nasdaq futures are unchanged after the S&P 500 notched its best two-day gain since June and the Nasdaq closed at a record high; premarket Mag7 / Semis are mixed but are net weaker with cyclicals underperforming as commodity names are underperforming due to a sharp overnight sell-off in precious metals, among the most notable moves today. Gold -2% and Silver -5% which appears to be de-risking in a low liquidity environment with both metals among the top YTD performing asset classes; gold set a new ATH yesterday. The rest of the commodity complex is seeing muted moves. Bond yields are flat to lower by 1bp as the USD sees a bid. The macro data focus is on Philly Fed. Coca-Cola, General Electric, Halliburton, Lockheed Martin, Northrop Grumman, RTX and 3M are expected to report results before the market open. Steady subscriber gains and rising average revenue per member should keep Netflix which reports after the close, on track for 17.3% sales growth in 3Q.

In premarket trading, Mag 7 stocks are mixed (Meta +0.5%, Amazon +0.3%, Microsoft 0.1%, Apple -0.2%, Nvidia little changed, Alphabet -0.1%, Tesla -0.3%)
- Gold and silver companies are tumbling as the precious metals slipped from their latest records as global trade tensions ease.
- Coca-Cola Co. (KO) climbs 2% after posting third-quarter sales growth that beat Wall Street expectations — a sign that consumers are snapping up the company’s beverages despite higher prices.
- Core Scientific Inc. (CORZ) is up 2% after a key proxy adviser said a takeover bid by CoreWeave Inc. undervalues the data center company.
- Crown Holdings (CCK) gains 8% after the packaging products company boosted its adjusted earnings per share guidance for the full year, beating the average analyst estimate.
- Elevance (ELV) gains 4% after the health insurer posted third-quarter profit that was ahead of expectations. The company also reaffirmed its adjusted earnings-per-share forecast for the full year, slightly above the average analyst estimate.
- Fluor (FLR) rises 5% after the Wall Street Journal reported that activist investor Starboard Value has amassed a nearly 5% stake in the engineering and construction company, citing people familiar with the matter.
- General Electric Co. (GE) inches 1% higher after the company raised its full-year outlook for a second consecutive quarter as the jet-engine manufacturer cashes in on strong air-travel demand.
- General Motors Co. (GM) climbs 8% after raising its full-year outlook and posting third-quarter results that topped Wall Street estimates on better—than-expected pickup truck sales and fresh relief from the Trump administration’s tariffs on auto parts.
- Halliburton (HAL) rises 3% after the energy service company reported third-quarter revenue that beat the average analyst estimate.
- NuScale Power Corp. (SMR) falls 4% after two analysts downgraded the nuclear small modular reactor company over concerns about its ENTRA1 deal.
- Philip Morris (PM), maker of oral pouch product Zyn, rises 3% after narrowing its adjusted earnings per share forecast for the full year.
- RTX Corp. (RTX) rises 5% after the company boosted its full-year profit outlook and reported third-quarter earnings that topped Wall Street expectations as sales and profit rose across its commercial aerospace and military hardware businesses.
- Zions (ZION) gains 1% after saying its profit topped estimates despite a $50 million loss from an alleged fraud, helping reassure investors who’d feared the credit markets might be harboring some deeper pain.
In corporate news, Amazon Web Services resolved the issues that plagued its services for about 15 hours on Monday, an episode that highlighted how much of the internet is dependent on a single company. Goldman is building out its wealth-management division in Saudi Arabia, while PayPal is said to be taking over a stake in German digital commerce company Shopware from a Carlyle fund.
The S&P 500 logged its biggest two-day gain since June as the third-quarter earnings season gets into full swing, with about 85% of US firms beating profit estimates so far. While the US government shutdown has caused an economic data vacuum, creating uncertainty about the Federal Reserve’s policy path, drawdowns have been short-lived, as investors see them as opportunities to add risk to their portfolios.
“Another day, another dearth of US data, as the government shutdown continues, with no end in sight,” said Michael Brown, a senior research strategist at Pepperstone Group Ltd. “To my mind, the path of least resistance continues to lead to the upside, and dips remain buying opportunities.”
The US Bureau of Labor Statistics is set to release September’s consumer price index on Friday, after a delay due to the government shutdown. The data, originally slated for Oct. 15, will give Fed officials a key reading on inflation ahead of their Oct. 30 policy meeting. The data may take on greater importance due to the government shutdown-driven data drought, said Rick Gardner at RGA Investments. He still sees a Fed cut in October and noted that a key test will be Big Tech earnings, with investors looking for clarity on how spending on artificial intelligence is leading to profitability.
“While earnings will remain in focus, particularly any updates on demand trends, international exposure post-tariffs, and their impact on profitability and capex, I think this week’s key events will be the inflation releases in the UK and US,” said Susana Cruz, a strategist at Panmure Liberum, “Both are still running hot and expected to rise further. Any upside surprises there could easily derail the rally.”
“Everything is weird,” said Bobby Molavi, head of EMEA execution services at Goldman. All-time highs are everywhere and classic asset class correlations are breaking down as stocks continue to climb every “wall of worry,” he wrote. It’s ‘the rally no one trusts,’ according to Bloomberg’s Markets Live blog.
As we have explained time and time again, buy-the-dip behavior from retail traders and faith in the AI narrative are a key reason why this market just keeps grinding higher; throw in a constant relentless short squeeze and you get daily record highs.
The next big test for the tech-fueled rally comes as a deluge of companies – accounting for almost 15% of the S&P 500’s total market value – report this week. Netflix, General Motors, Coca-Cola and Texas Instruments are among today’s highlights. Of the 60 S&P 500 companies that have reported so far, nearly 85% have beaten estimates.

Earnings aside, signs of easing trade tensions between the US and China continue to offer equities further support. Gold, a classic haven, dipped from its latest record ahead of the two sides returning to the negotiating table. Before those talks resume, Trump signed a landmark pact with Australian PM Anthony Albanese to boost America’s access to rare earths and other critical minerals, an effort to counter China’s tight grip on the sector. In other tariff news, small businesses challenging many of Trump’s global levies urged the Supreme Court to affirm lower court rulings that the import levies amount to a massive illegal tax.
Gold slumps, with spot prices falling by $94 to $4,262/oz, though recent precious metals volatility means it’s only hit the lowest since Monday. Silver prices are also slumping and on track for their biggest drop since April.

The selloff reversed in Europe too, with the Stoxx 600 erasing an earlier loss as real estate and utilities shares outperformed, while chemicals and mining shares lagged after prices of gold and silver slumped due to the stronger dollar. Among individual movers in Europe, Eurofins Scientific SE dropped 9% after third-quarter results. Edenred SE jumped as much as 15%, the most on record, after the digital platform for services and payments reported better revenue growth for the third quarter. Assa Abloy AB gained as much as 3.4% after the Swedish lock and entrance systems group reported reassuring results. Here are the biggest movers Tuesday:
- Edenred shares rise as much as 15%, the biggest intraday spike on record, after the digital platform for services and payments reported better 3Q revenue growth than anticipated
- Bper Banca jumped as much as 8% to the highest in 18 years after the Italian lender signed derivative contracts for a synthetic exposure to its own shares equal to 9.99% of its share capital, according to a statement
- Getinge shares rise as much as 6.8%, to the highest in more than a year, after the Swedish health-care equipment firm reported better-than-expected earnings and sales for the third quarter
- Assa Abloy gains as much as 3.6% to a fresh high, after the Swedish lock and entrance systems group reported solid and reassuring results
- Segro shares rise as much as 3.9%, after the property investment and development company said occupier sentiment has improved, leading to the strongest quarter of pre-letting activity since early 202
- Var Energi shares jump as much as 4.6% after the oil and gas company delivered cashflow and adjusted earnings ahead of expectations, tempered by a miss at the bottom-line
- Eurofins Scientific shares fall as much as 10%, the most in a year, on continued softness of the French firm’s biopharma division
- Nordnet falls as much as 8.9%, the most since June 2023 after the Swedish retail trading platform and bank’s third-quarter report missed expectations and revealed a SEK18 million one-time cost related to an administrative error
- Tele2 shares fall as much as 6.7% after the Swedish telecom operator reported 3Q Ebitda that missed estimates, causing traders to take profits following a strong rally this year
- OVH Groupe shares slide as much as 19%, the biggest drop in 18 months, after the IT services firm issued growth guidance for fiscal year 2026 that analysts found underwhelming
Earlier in the session, Asian stocks hovered near record-high levels, led by an extended rally in Chinese equities on optimism over a trade deal with the US. The MSCI Asia Pacific Index was little changed after rising about 1% earlier. Alibaba and BHP Group were among the biggest boosts. The CSI 300 Index for mainland shares gained more than 1%. Japanese stocks were volatile and the yen dropped 0.5% after Sanae Takaichi won a parliamentary vote to become prime minister, opening the way for more fiscal spending. The benchmark Nikkei 225 had nearly hit 50,000 earlier Tuesday, Pictet Asset Management Japan Ltd. head of investment strategy Jumpei Tanaka said, adding that “some profit-taking likely emerged as a reaction to that earlier rally.” Chinese stocks extended their recent rally as anticipation grew over a potential deal ahead of President Donald Trump’s meeting with his counterpart Xi Jinping next week. Trump said said he expects the US to have a “really fair and really great trade deal” with China. Meanwhile, the Fourth Plenum underway in Beijing is being monitored for potential policy boosts. “I think investors feel good about the upcoming US-China trade resolution, against a backdrop of falling rates and structural AI demand growth,” said Vey-Sern Ling, senior equity adviser for Asia technology at Union Bancaire Privee. “There’s a lot to feel comfortable about and not many visible dark clouds on the horizon.”
In FX, the dollar is stronger and gaining against all G-10 peers. The yen is among the underperformers following the appointment of Japan’s new prime minister. The Swiss franc is not far from a decade-high versus the euro on haven flows.
In rates, treasuries are little changed, keeping yields within 1bp of Monday’s closing levels, amid similar price action in European bonds and recently active French-German spreads. The US curve is slightly flatter on the day. US stock index futures are little changed, holding Monday’s 1% advance following constituents’ quarterly results. US 10-year is near 3.97% after dipping as low as 3.96% overnight, underperforming. There’s small and mixed moves across European bond markets, with bund yields lower at the long-end and little changed at the short. Gilts are rallying at the long-end despite an overshoot on borrowing.
In commodities, oil prices fluctuate, with Brent sitting around $61/barrel. Gold slumps, with spot prices falling by $94 to $4,262/oz, though recent precious metals volatility means it’s only hit the lowest since Monday. Silver prices are also slumping and on track for their biggest drop since April.
The US economic calendar calendar includes October Philadelphia Fed non-manufacturing activity at 8:30am (-22.2, down from -12.3). Fed’s external communications blackout ahead of the Oct. 29 Fed policy decision began Saturday
Market Snapshot
- S&P 500 mini unch
- Nasdaq 100 mini -0.1%
- Russell 2000 mini -0.3%
- Stoxx Europe 600 little changed
- DAX -0.1%
- CAC 40 little changed
- 10-year Treasury yield -1 basis point at 3.97%
- VIX +0.5 points at 18.72
- Bloomberg Dollar Index +0.2% at 1211.97
- euro -0.2% at $1.1622
- WTI crude little changed at $57.57/barrel
Top Overnight News
- USTR Jamieson Greer warned China not to retaliate against foreign companies helping the US to develop critical industries after Beijing sanctioned the American units of South Korea’s Hanwha Ocean. BBG
- BoJ officials see no urgency to hike the benchmark rate next week. The officials believe conditions are coming together for a rate hike as soon as December, but there is no conclusive factor to raise the rate on Oct. 30. BBG
- US Director of Federal Housing Pulte said the Trump administration is opportunistically evaluating an offering for Freddie and Fannie, which could occur as early as the end of 2025.
- US Senate Democrats are launching an effort to repeal a portion of Republicans' budget law that exempts certain "orphan drugs" from Medicare price negotiations: Axios
- Japan’s benchmark Nikkei Stock Average neared the 50,000 mark on Tuesday, as foreign investors bet on the expansionary policies of Sanae Takaichi, who received parliamentary approval the same day to become the country’s first female PM. Nikkei
- The longest-duration Japanese bonds are attracting relative-value hunters, suggesting there’ll be more flattening of the JGB curve, according to MLIV. BBG
- Small businesses urged the Supreme Court to affirm lower court rulings that Trump’s global tariffs amount to an illegal tax on American companies to the tune of $3 trillion. BBG
- The BOE has begun reaching out to financial institutions about conducting stress tests on the private credit market, people familiar said. BBG
- Republican leaders on Capitol Hill are quietly ramping up talks within their senior ranks and with White House officials over how to structure and advance a potential extension of key Affordable Care Act insurance subsidies before the end of the year. Politico
- The US Army asked Apollo, Carlyle, KKR and other PE firms to pitch financing models to help fund a $150 billion infrastructure overhaul. FT
- ZION Q3 earnings report: Core PPNR beat driven by slightly higher NII, while expenses came in below. Credit performance outside of the two identified credits was solid noting that ex these charge off NCOs would have been 4bps. Despite the elevated credit losses in the quarter, ZION noted it anticipates the credit losses are an isolated incident, with further review of the portfolio not showing any incremental credit issues. (H/T GS Fins Trading)
Trade/Tariffs
- US Trade Representative Greer said they will take action over Nicaragua's labour rights policies and he proposed additional duties of up to 100% on Nicaragua following the conclusion of a Section 301 investigation, while he proposed to suspend all of Nicaragua's benefits under the Central America-Dominican Republic Free Trade Agreement, either immediately or phased in over 12 months.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks took their cues from the rally on Wall Street as the focus remained on US-China trade with some optimism following US President Trump's comments in which he stated that China has been respectful of them and although he continued to tout a November 1st deadline for additional tariffs, he also reaffirmed that he will be meeting with Chinese President Xi and thinks they will reach a 'fantastic deal'. ASX 200 climbed to a fresh record high with the advances led by the mining and resources sectors after Australia and the US signed a critical minerals agreement, and with mining giant BHP gaining following its quarterly production update. Nikkei 225 rallied and briefly approached to near the 50k level before fading some of the gains, while attention was on the PM vote in parliament where Abe-protege Takaichi was elected to become Japan's first female PM, and which is seen to potentially delay or slow the BoJ hiking rates. Hang Seng and Shanghai Comp were higher amid the hopes for an improvement in US-China trade relations and with the ongoing plenum where China is to map out its next five-year plan.
Top Asian News
- Japanese PM Takaichi to speak at 14:00BST.
- Japanese LDP leader Takaichi won the lower house vote (237 votes out of 465-seats) to become Japan's first female PM, as expected. It was separately reported that Takaichi is to appoint Satsuki Katayama as Finance Minister and Kimi Onoda as Economic Security Minister, while she will appoint Ryosei Akazawa as Trade Minister and Shinjiro Koizumi as Defence Minister, according to FNN.
- Japan incoming Finance Mi