Blue Finessence
Blue Finessence
  • Home
  • About Us
  • Services
    • Our Services
    • Company Formation in Europe
  • News
    • Internal News
    • General news
  • Contact
  • Your cart is currently empty.

    Sub Total: $ 0,00 View cartCheckout

Global Corporate Tax Levels Continue To Slide, But France Remains Highest

Home / Finance / Global Corporate Tax Levels Continue To Slide, But France Remains Highest
Global Corporate Tax Levels Continue To Slide, But France Remains Highest
  • October 22, 2025
  • test
  • 65 Views

Global Corporate Tax Levels Continue To Slide, But France Remains Highest

Global Corporate Tax Levels Continue To Slide, But France Remains Highest

Since the turn of this century, OECD countries have experienced a marked trend of declining corporate tax rates.

The average corporate income tax rate applied by OECD members fell from about 33 percent in 2000 to between 24 and 25 percent in recent years (24.2 in 2025).

As Statista's Tristan Gaudiant details below, using the organization's data, France maintains the highest combined corporate tax rate in the OECD, at 36.1 percent in 2025, followed by Colombia (35 percent), while the lowest marginal corporate tax rate is found in Hungary, at 9 percent, followed by Ireland (12.5 percent).
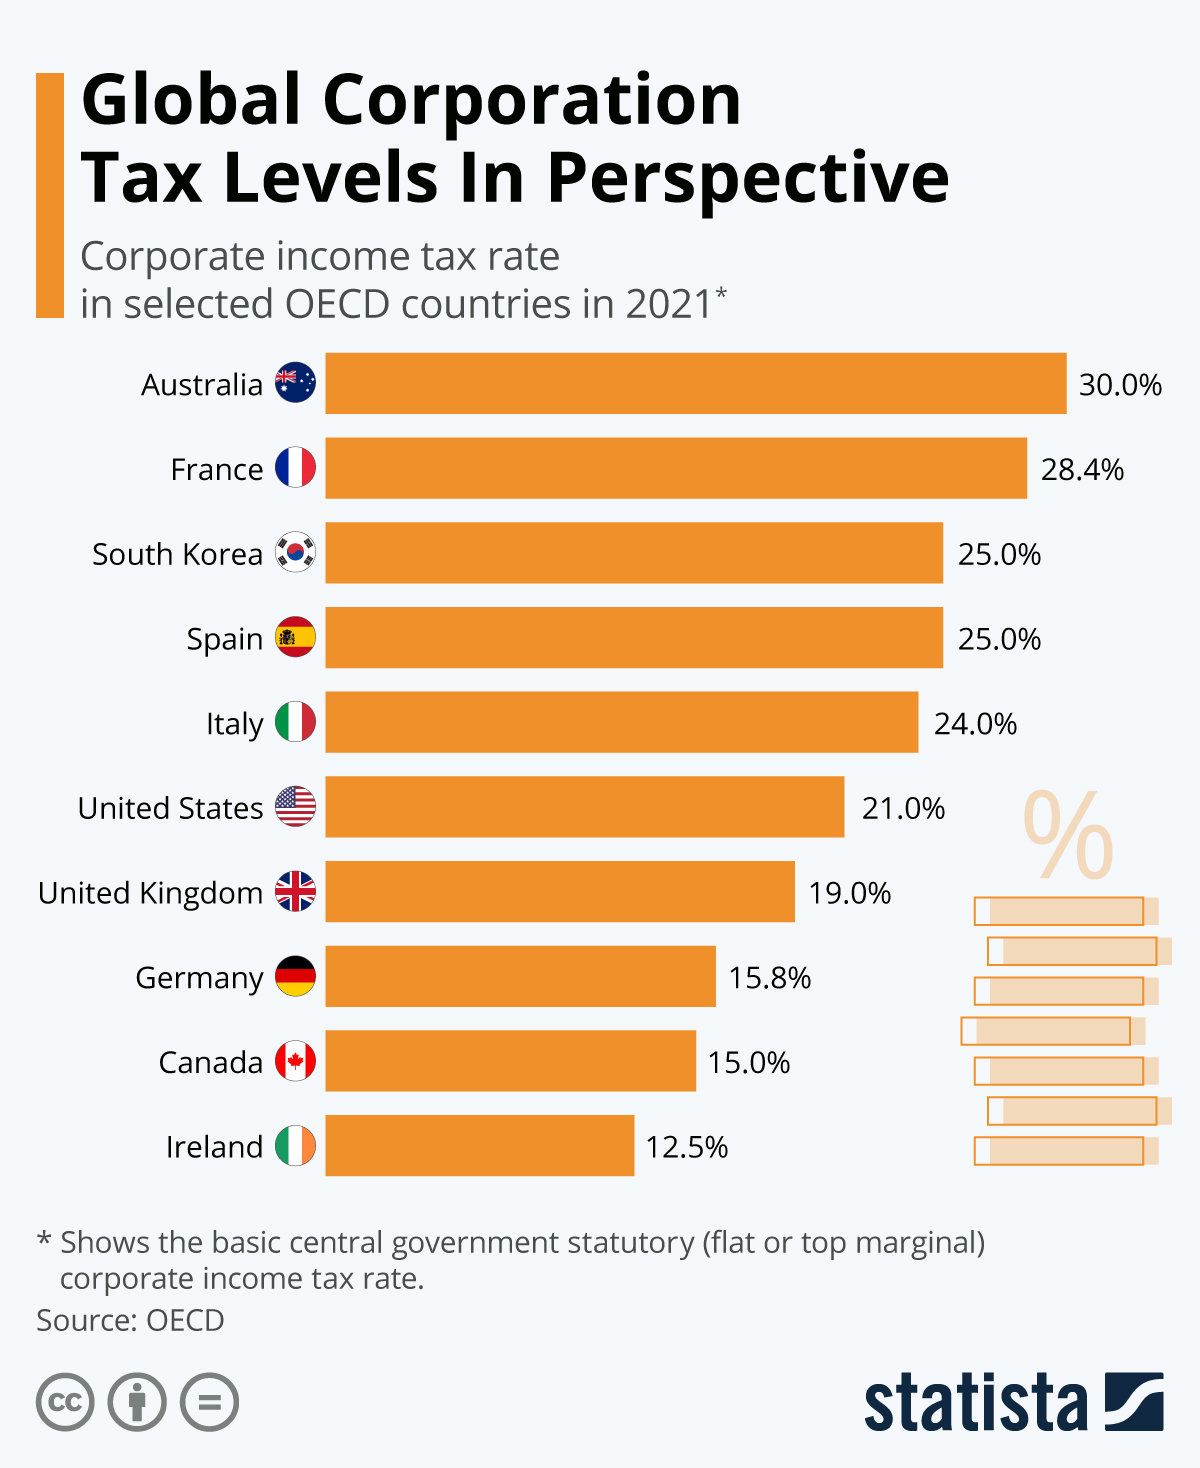
Infographic: Global Corporation Tax Levels In Perspective | Statista

You will find more infographics at Statista

In 2021, a major international agreement was reached under the guidance of the OECD to establish a minimum corporate tax rate of 15 percent on the profits of multinational companies, aimed at reducing tax inequalities and preventing profit shifting to low-tax territories.

Since then, many jurisdictions have taken steps towards the implementation of these rules into their domestic law, with the global minimum tax starting to apply from the beginning of 2024, although two countries (Hungary and Ireland) are yet to meet this requirement.

The challenge for OECD countries remains to strike a balance between economic attractiveness and tax fairness, while minimizing competitive distortions.

Advocates of low tax rates argue that they attract foreign investment and boost competitiveness, whereas critics point out that such rates can reduce useful public revenue (public services, social policies funding) and exacerbate inequality, particularly when large corporations benefit from preferential regime and aggressive tax optimization.

Tyler Durden
Wed, 10/22/2025 – 02:45

Tyler DurdenSource

Share:

Previus Post
UK inflation
Next Post
Hungary ‘Safest

Leave a comment

Cancel reply

Recent Posts

  • Independent assessment to support establishment of a Future Entity
  • Predisposizione, da parte dell’Agenzia delle entrate, delle bozze dei registri IVA, delle liquidazioni periodiche dell’IVA e della dichiarazione annuale dell’IVA di cui all’articolo 4 del decreto legislativo 5 agosto 2015, n. 127. Ulteriore estensione del periodo sperimentale stabilito con il provvedimento del Direttore dell’Agenzia delle entrate n. 183994 dell’8 luglio 2021 (provvedimento)
  • Istituzione delle causali contributo per il versamento, tramite modello F24, dei contributi all’INPS da destinare ad Enti Bilaterali (risoluzione n. 5)
  • Deadline for challenging your business rates valuation
  • Targeted financial support for aspiring social workers

Recent Comments

  1. validtheme on Digital Camera

Archives

  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025

Categories

  • Finance
  • internal news
  • Italy
  • Uncategorized
  • United Kingdom

Recent Posts

  • Independent assessment to support establishment of a Future Entity
    09 March, 2026Independent assessment to support
  • Predisposizione, da parte dell’Agenzia delle entrate, delle bozze dei registri IVA, delle liquidazioni periodiche dell’IVA e della dichiarazione annuale dell’IVA di cui all’articolo 4 del decreto legislativo 5 agosto 2015, n. 127. Ulteriore estensione del periodo sperimentale stabilito con il provvedimento del Direttore dell’Agenzia delle entrate n. 183994 dell’8 luglio 2021 (provvedimento)
    09 March, 2026Predisposizione, da parte dell’Agenzia
  • 09 March, 2026Istituzione delle causali contributo
  • Deadline for challenging your business rates valuation
    09 March, 2026Deadline for challenging your

Tags

Blue%20Finessence

Excellence decisively nay man yet impression for contrasted remarkably. There spoke happy for you are out. Fertile how old address did showing.

Contact Info

  • Address:CEO Blue FinEssence Ltd Piccadilly Circus 126 London
  • Email:director@bluefinessence.com
  • Phone:004407784915057

Copyright 2024 Bluefinessence. All Rights Reserved by Bluefinessence

  • About Us
  • Our Services