
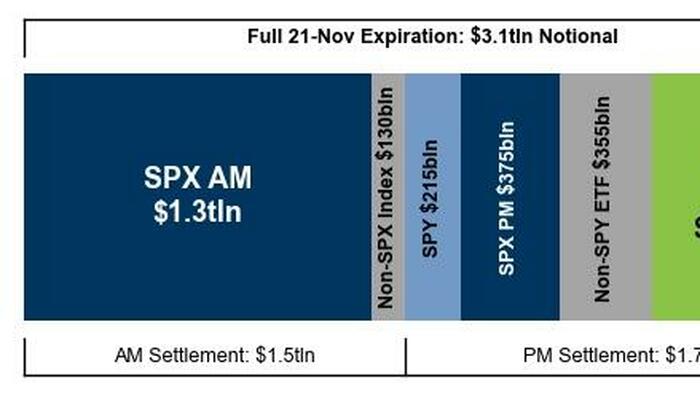
Futures Slide As Bitcoin Flash Crashes To April Low Ahead Of $3.1 Trillion Opex
10 Things You Shouldn’t Miss This AM…
1) Japan on Friday escalated its warning of currency intervention and the central bank governor signaled the chance of a near-term interest rate hike, as authorities sought to combat unwelcome yen falls blamed for pushing up the cost of living. RTRS
2) Japan’s inflation ticked higher and exports rose. National CPI for Oct is inline w/the Street, including on headline at +3% (up from +2.9% in Sept) and core (ex-food/energy) at +3.1% (up from +3% in Sept). BBG
3) India’s rupee fell to a record low against the dollar, pressured by uncertainty around a potential US trade deal. BBG
4) The US is open to lifting tariffs on EU goods such as beef and other foods to help keep grocery prices affordable. FT
5) The U.K. government’s borrowing continued to run ahead of projections in October, a deterioration in its finances that it will aim to correct with tax rises and some spending cuts in its annual budget statement next week. WSJ
6) Trump has lifted a 40% tariff on certain Brazilian agricultural products, including coffee, beef and fruits, as Brazil reaps the benefit of the US administration’s attempt to bring down domestic food prices. FT
7) The Fed’s Anna Paulson struck a cautious tone ahead of December’s meeting, saying, “Each cut raises the bar for the next.” Still, she remains more worried about labor market weakness. Stephen Miran reiterated that policy is very restrictive. BBG
8) America’s middle class is weary. After nearly five years of high prices, many middle-class earners thought life would be more affordable by now. Costs for goods and services are 25% above where they were in 2020. Even though the inflation rate is below its recent 2022 high, certain essentials like coffee, ground beef and car repairs are up markedly this year. WSJ
9) The Congressional Budget Office now estimates that Trump’s tariffs will reduce deficits by ~$3T over the next 10 years, down from a prior forecast of $4T. CBO
10) Including yesterday (dating back to since 1957) there have been 8 instances where the S&P 500 gaps up more than 1% only to reverse and close in the red. On the bright side here is S&P 500’s average performance after these 8 instances: 1 day later +233bps, 1 week later +288bps, 1 month later +472bps.
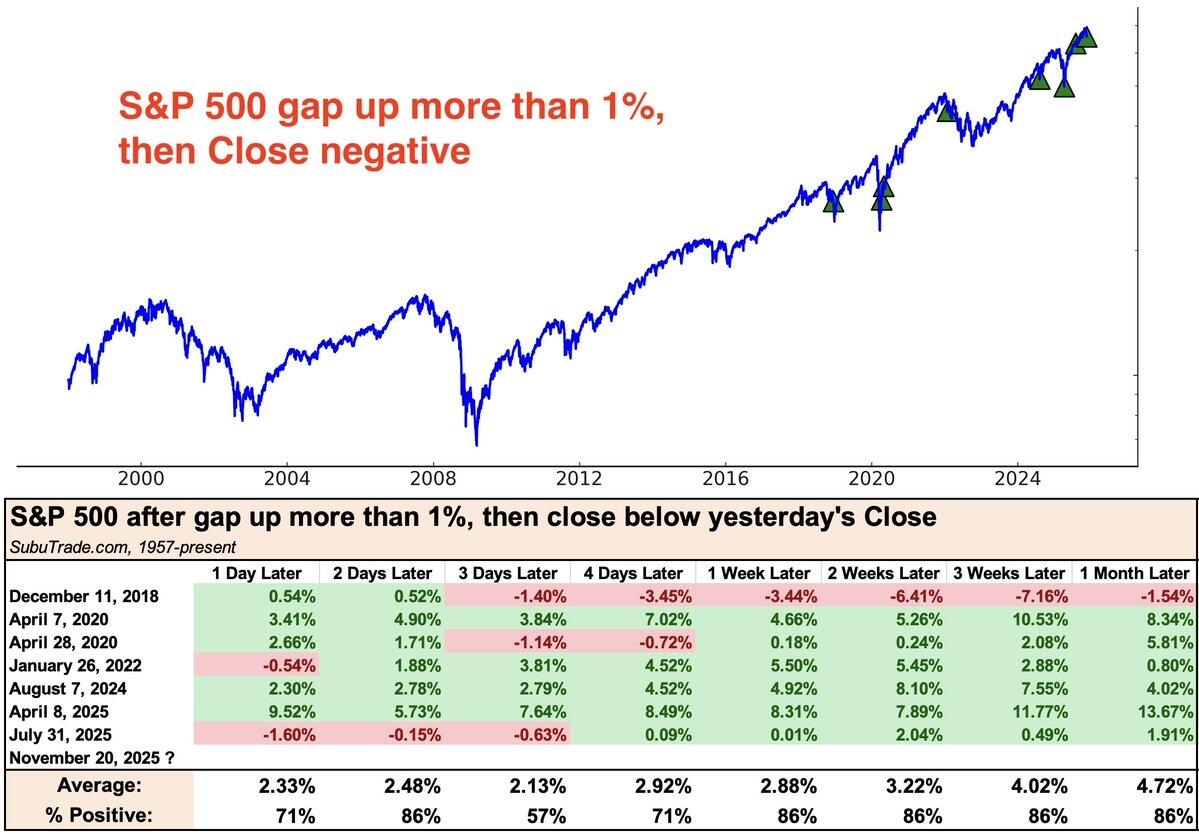
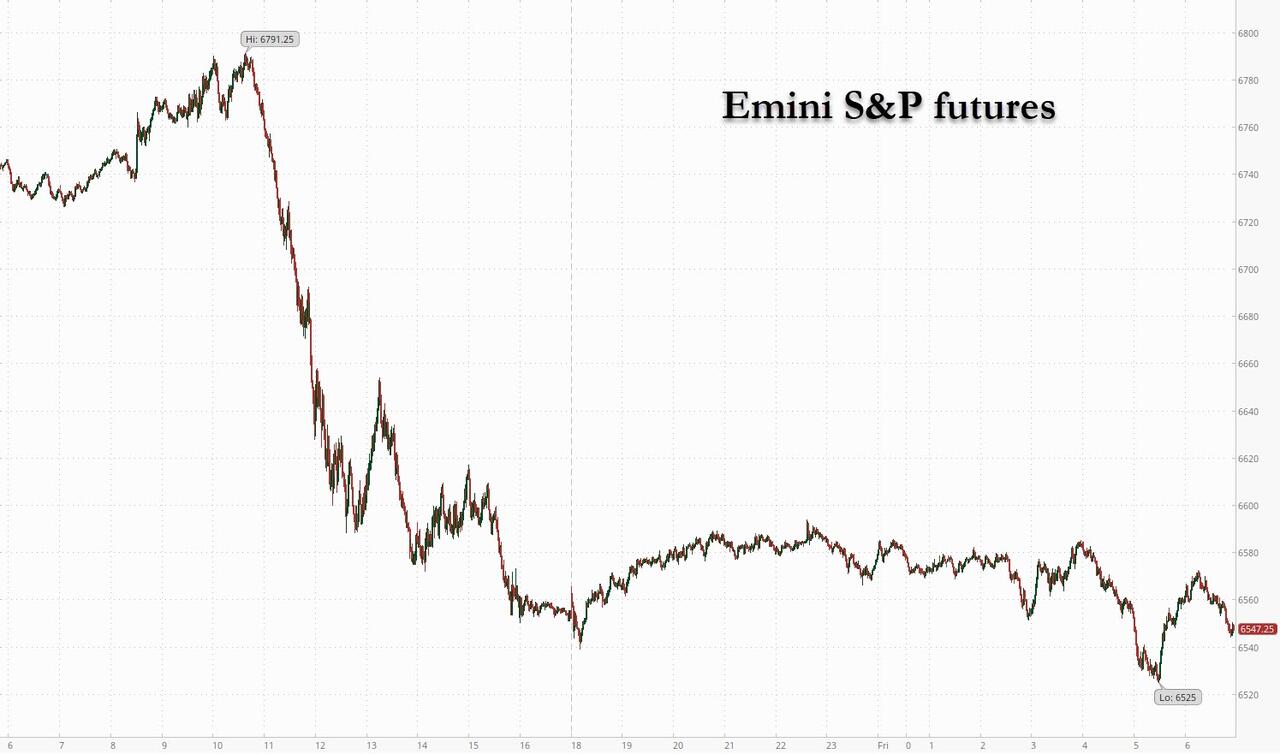
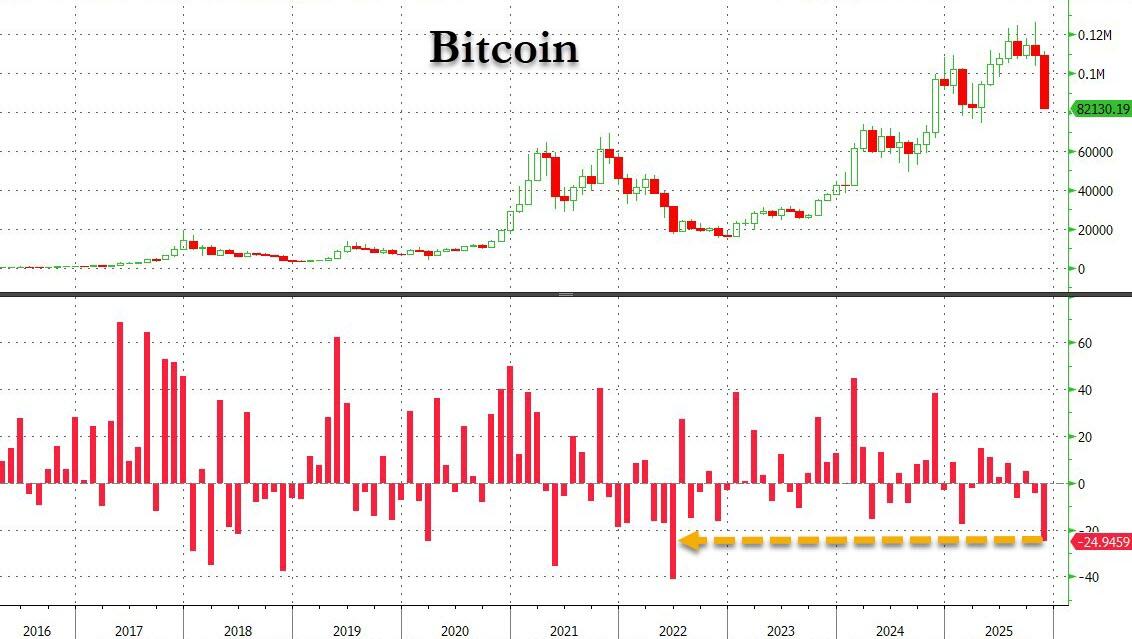
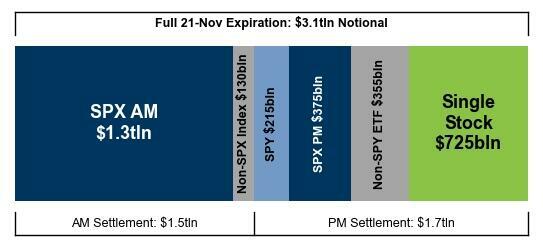
US stock futures continued to sink following yesterday’s remarkable reversal – from +2% to -2% intraday, a move which according to Goldman has only happened 2 other times before: April 7th 2020 (after COVID crash) April 8th 2025 (after Liberation Day crash) – and broad underperformance in Asia (NKY -2.4%, HSI -2.4%, Kospi -3.8%). As of 7:15am, S&P futures were down 0.3% and Nasdaq futures slid 0.4% with a $3.1 trillion option expiration on today's calendar. Pre-mkt, Mag 7 were mixed, with Nvidia falling more than 1% in premarket trading as the biggest artificial-intelligence stocks remained under pressure. Meanwhile the collapse in bitcoin is accelerating, and after a flash crash in overnight trading, it's on pace for its worst month since the June 2022 crypto crash. Bond yields are 1-3bp lower; USD is largely unchanged. Commodities are mostly lower: oil -2.6%, Silver -3.3%. Today's we’ll get the global flash November PMIs, the November Kansas City Fed services activity update, and the Final UMIch numbers.Central bank speakers include the Fed's Williams and Logan, the ECB's Lagarde, de Guindos, Kocher, Muller and Nagel, and the BoE's Pill.
In premarket trading, Mag 7 stocks are mixed: Nvidia falls 1.4%, on track to extend losses, with shares in the semiconductor giant lagging other Magnificent Seven stocks in premarket trading (Alphabet +0.7%, Tesla +0.8%, Amazon +0.2%, Meta +0.3%, Apple +0.1%, Microsoft -0.4%)
-
AnaptysBio (ANAB) fell 15% after GSK initiated litigation against the company in the Delaware Chancery Court.
-
Cryptocurrency-exposed stocks (MSTR -2.9%, COIN -1.3%, MARA 1.5%) tumble as Bitcoin is on track for its worst monthly performance since a string of corporate collapses rocked the wider crypto sector in 2022.
-
Gap Inc. (GAP) rises 4.5% after it reported stronger-than-expected sales, a sign that celebrity-fueled marketing, flashy collaborations and a revamped inventory are luring in consumers.
-
New Fortress Energy (NFE) rises 12% after it reported third quarter earnings.
-
VinFast Auto (VFS) falls 5.1% after it reported total revenue for the third quarter that missed the average analyst estimate.
-
Enviri shares (NVRI) rise 34% after Veolia agreed to buy the US hazardous waste firm Clean Earth for an enterprise value of $3b.
In corporate news, Netflix, Comcast and Paramount Skydance submitted bids for Warner Bros. Discovery by the Nov. 20 deadline. OpenAI is partnering with Hon Hai to design and manufacture hardware for data centers and Hon Hai aims to spend up to $5 billion growing its US manufacturing footprint.
The Trump administration is proposing to open new areas off of California, Florida and Alaska to crude drilling that would dramatically expand the sale of oil and natural gas rights. Trump’s 28-point peace plan would force Ukraine to cede large chunks of territory taken by Russia, cap the size of its military and lift sanctions on Moscow over time.
A $5 trillion slide in global equities has left investors questioning how much further the tech-led pullback can go. The S&P 500 saw its sharpest intraday reversal since April’s tariff turmoil on Thursday as concerns over lofty valuations and waning prospects for US interest-rate cuts rattled sentiment.
“This is a rational selloff after the rally in tech stocks this year,” said Rory McPherson, chief investment officer at Magnus Financial Discretionary Management. “It could go even further as the market’s not oversold yet. The Fed’s rates policy outlook at the next meeting will absolutely be key.”
US stock futures struggled for direction after the S&P 500 sank to its lowest level since September amid a sustained retreat from the market’s riskier corners. Bitcoin fell below $82,000, after suffering a 3000 point flash crash just before the European open.
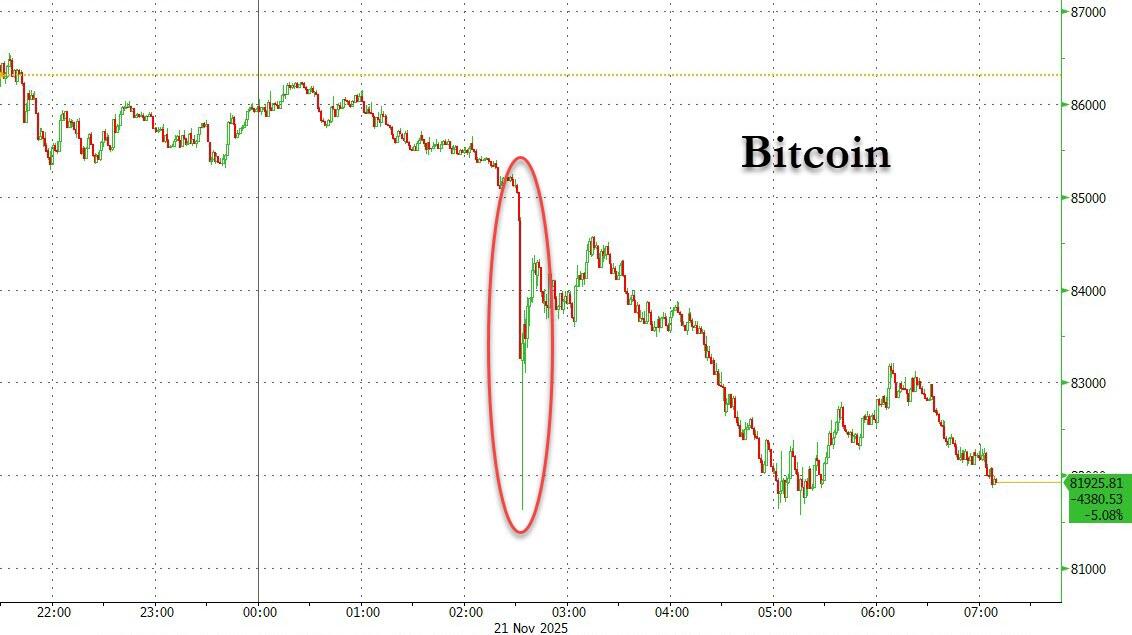
Bitcoin is now down 35% from its October highs, with the November drop wiping out a quarter of bitcoin's value, and is on pace for the worst monthly drop since the June 2022 Crypto collapse.
Fed’s Barr, who had supported rate cuts in September and October, added to the hawkish narrative signaling discomfort over inflation. Meanwhile, JPMorgan abd Morgan Stanley’s economists said they no longer expect a December rate cut, citing the bounce back in payrolls for September lowering the risk of a higher unemployment rate.
Thursday’s dramatic reversal in equities failed to deliver the “all clear” for risk that traders sought, instead sending them for cover against further losses, said Goldman partner John Flood. Today’s November options expiry, including $1.7 trillion of S&P 500 options and $725 billion notional of single stock options, has the potential to fuel erratic moves in the index.
Other concerns include brewing worries about over investment in AI, frothy valuations and the ongoing vacuum of macro data. Oracle is emerging as the credit market’s barometer for AI risk and the price of the company’s CDS have surged. Big tech’s debt binge isn’t limited to just Oracle, with risks rising in the race to create an AI world, as highlighted by Ryan Vlastelica in today’s Tech Watch column.
Stocks in Europe are also sliding, following from the sharp reversal in sentiment on AI and tech stocks in yesterday’s US session and heavy declines in Asia. Stoxx 600 down by 1.1% with technology and energy stocks the biggest drags. The benchmark is on track for its worst week since April. Here are the biggest movers Friday:
- CTS Eventim surges as much as 12%, the most in five years, after the events firm delivered adjusted Ebitda growth above analyst expectations in the third quarter and reiterated its full-year guidance
- Ubisoft shares turn higher, reversing initial declines, as the stock resumes trading following a week-long suspension caused by a delay to the publication of second-quarter results
- Hammerson shares rise as much as 2.8%, , after the real estate firm said it has taken full control of The Oracle retail and leisure destination in Reading after buying a 50% stake from its joint venture partner
- Canal+ shares rise as much as 9.6%, after the broadcaster announced it has retained exclusive rights to the Champions League and two other UEFA cup competitions in France for the period 2027-2031
- ITM Power gains as much as 8.4% after being selected by Stablegrid Group as the technology partner and supplier for two energy infrastructure projects in Germany
- European defense shares fall on Friday after Ukrainian President Volodymyr Zelenskiy said he’s agreed to work on a peace plan drafted by the US and Russia and expects to talk with Donald Trump in the coming days about the proposals
- Tullow Oil shares plummet as much as 32% to a new record low after the company issued a trading update. Analysts said there has been a lack of progress on the refinancing of its mountain of debt
- Babcock drops as much as 6.7% following its first-half results, and amidst wider weakness in defense stocks on Friday after Ukrainian President Volodymyr Zelenskiy said he’s agreed to work on a peace plan
- Ithaca Energy shares fall as much as 11%, the most in two months, as Goldman Sachs downgrades its rating on the North Sea oil company to sell from neutral, with a 180p price target
Earlier in the session, Asian equities posted their steepest weekly decline since April as technology shares followed a sharp selloff in US peers, driven by renewed concerns over stretched AI valuations. The MSCI Asia Pacific Index fell as much as 1.7%, bringing the week’s losses to nearly 4%. Benchmarks in Taiwan and South Korea led declines in the region, with shares in China and Hong Kong also traded lower. Some banks, such as HSBC, are starting to look at countries with lower exposure to AI, including India and Indonesia, as alternatives. Asia’s leading chip suppliers to Nvidia led losses on the regional gauge. TSMC and Samsung Electronics dropped more than 4% each before paring some of those losses.
In FX, the Bloomberg Dollar Spot Index slightly higher, with the yen outperforming after Japan’s government unveiled its biggest stimulus plan since the pandemic. Indian rupee hit a record low.
In rates, bonds rallying in the risk-off environment, with outperformance in gilts after weak retail sales data, a borrowing overshoot and scant growth shown in PMIs. Eurozone activity remained solid, boosted by services.
In commodities, oil prices dragging on energy companies, with Brent down over 2% below $62/barrel as traders weigh a Ukraine-Russia peace plan and sanctions on two Russian oil majors. Bitcoin sliding below $82,000 and set for worst month since 2022. Gold prices lower, down about $40 to $4,038/oz.
The US economic calendar includes September real average hourly earnings (8:30am), November preliminary S&P Global US PMIs (9:45am), November final University of Michigan sentiment, August wholesale inventories (10am) and November Kansas City Fed services activity (11am). Fed speaker slate includes Williams (7:30am), Collins (8am), Barr and Miran (8:30am), Jefferson (8:45am) and Logan (9am)
Market Snapshot
- S&P 500 mini -0.4%
- Nasdaq 100 mini -0.8%
- Russell 2000 mini -0.4%
- Stoxx Europe 600 -1.1%
- DAX -1.2%
- CAC 40 -0.7%
- 10-year Treasury yield -3 basis points at 4.05%
- VIX +1.1 points at 27.54
- Bloomberg Dollar Index little changed at 1227.51
- euro -0.1% at $1.1516
- WTI crude -2.5% at $57.53/barrel
Top Overnight News
- OpenAI CEO Sam Altman is bracing for possible economic headwinds in catching up to a resurgent Google (GOOGL), according to The Information. He told colleagues last month that Google’s recent AI progress could “create some temporary economic headwinds” for OpenAI, and the company’s narrowing tech lead and rising cash-burn projections have raised questions among investors.
- Treasury Secretary Bessent said the Fed should keep going with its cutting cycle and should be looking at the data, via Bloomberg.
- JPMorgan no longer expects the Federal Reserve to cut rates in December, vs its prior forecast of a 25bp cut.
- Standard Chartered no longer expects the Fed to cut by 25bps in December following the jobs data; expects a Q1-2206 cut, most likely January (prev. forecast no 2026 cuts)
- Republican senators have been privately lobbying US President Trump to support a limited short-term extension of Obamacare subsidies, according to Punchbowl. Adds that save the GOP from a 2026 drubbing and buy time for Congress to pass a more favourable longer-term health care plan. Multiple GOP senators were set to meet with US President Trump on Thursday, but the meeting was cancelled for unrelated reasons.
- Fed’s Paulson (2026 voter) said she is approaching the December rate decision cautiously and that the September labour-market report was encouraging overall, though she remains, on balance, more worried about the labour market than inflation. She said rate cuts so far have been appropriate but each one raises the bar for the next, and with upside risks to inflation and downside risks to employment, monetary policy must walk a fine line. She expects to learn a lot between now and the December meeting and said her longer-term policy thinking is focused on balancing inflation and labour-market risks. Paulson said the US economy is doing OK, but aggregate growth is unusually dependent on high-income earners and is particularly sensitive to equity valuations. She added that tariff effects are smaller than feared and that the overall demand environment is helping contain inflation, according to Reuters.
Trade/Tariffs
- US President Trump signed an order modifying the scope of tariffs on Brazil, stating that certain agricultural products will not be subject to the additional ad valorem duty imposed under Executive Order 14323, according to the White House. Bloomberg reported that Trump has expanded his reductions of certain food tariffs by extending them to the 40% surcharge placed on Brazil over the Bolsonaro case, noting that last week’s exemptions did not apply to that portion of the tariffs. White House said US President Trump's order on Brazilian imports removes tariffs announced on July 30th on imports of Brazilian beef, coffee, and orange juice.
- EU Trade Commissioner said momentum is improving on the Australia–EU trade deal and expects another round of talks early next year, according to Reuters.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks traded lower across the board as the sharp Wall Street selloff reverberated through the region despite the absence of fresh catalysts. ASX 200 was dragged down by all sectors, with gold and mining leading declines; tech held up relatively better alongside defensive names. Nikkei 225 slipped at the open, pressured by mining and metals, while financials found some relief as yields eased off highs. No move was seen on the budget, which came in line with expectations. Hang Seng and Shanghai Comp both opened softer but recovered to trade firmer, though still reflecting the cautious global tone.
Top Asian News
- Japan’s cabinet approved a JPY 21.3tln economic stimulus package (vs expectations of JPY 20–21.3tln), with JPY 17.7tln in fresh spending via the extra budget and an overall impact of JPY 42.58tln, according to Bloomberg. Japan PM Takaichi said new bonds will be issued to fund the package if tax revenue falls short, but total JGB issuance will be smaller than last year, adding that sustainable state finances must be achieved through economic growth, according to Reuters.
- Japanese Finance Minister Katayama said she will take appropriate action if there are excessive FX moves, noting that FX intervention is an option as it was mentioned in the Japan–US agreement in September. She said the government will issue debt to fund part of the stimulus package as needed, is not trying to increase the size of spending, and is alarmed by recent one-sided and rapid foreign-exchange moves, according to Reuters.
- Japanese Finance Minister Katayama said she is closely watching FX moves with a high sense of urgency and will take appropriate action based on the US–Japan forex agreement. She declined to comment on FX levels, noted that recent moves have been sharp and one-sided, and stressed that currencies should move in a stable manner reflecting fundamentals. She said that at her meeting with BoJ Governor Ueda and the Economy Minister, Ueda explained the BoJ will gradually adjust monetary support in line with economic and price improvements, adding that specific policy decisions are up to the BoJ. She