
Futures Rise As Bullish Sentiment Returns After Rollercoaster Week
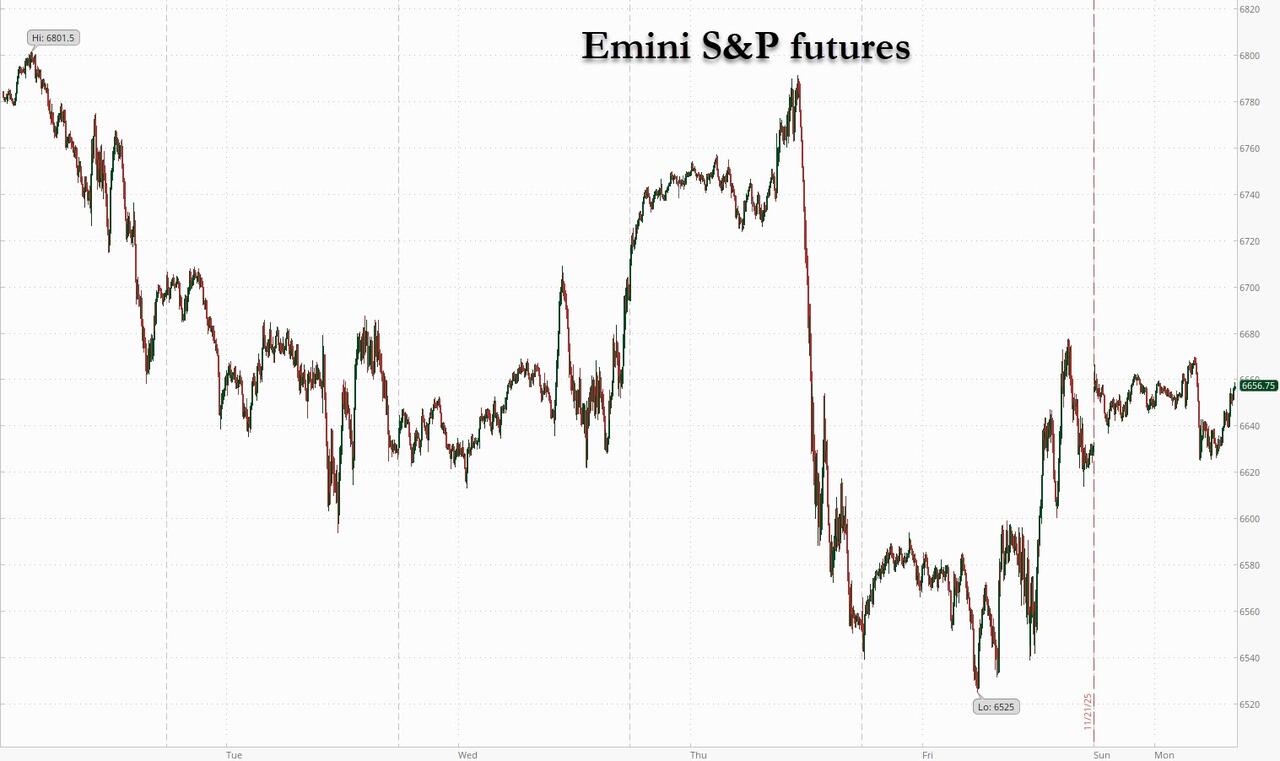
US equity futures are higher, but off their overnight highs, as the market looks to rebound from its worst week since early Oct; sentiment was lifted after shares of Alibaba jumped 4.7% in Hong Kong after a strong debut for its AI app; also boosting futs was a spike in December rate cut hopes and bullish comments from Morgan Stanley’s Michael Wilson. Still, after a bruising week, and with key macro data delayed until after the December FOMC, bulls are tentative as the S&P is -3.5% MTD, its worst monthly performance since March. As of 8:00am ET, S&P futures are up 0.6%, but moving fast in an extremely illiquid environment. Pre-mkt, Mag7 names are higher led a 3% gain for Alphabet. Semis are boosted by AVGO / NVDA up 24 and 40bp. Cyclicals, ex-Materials, are higher and outperforming Defensives. Novo Nordisk slumped 10% in Copenhagen after studies showed an Ozempic pill failed to slow Alzheimer’s progression. Bond yields are lower by 1-3bp as the yield curve bull flattens and the USD trades lower. Bitcoin began the week on the back foot – with a slam shortly after the European open killing hopes for a modest rally – following a prolonged selloff that has put the token on track for its worst month since 2022. Crude is trading near session highs, reversing an earlier slide, following the biggest weekly loss since early October, as traders watch US-Ukraine talks for signs on whether a Russia peace deal could increase crude flows. Trump floats a 2-yr ACA extension with increased restrictions on qualifying for the program with additional details expected this week. More Sept macro data will be released this week with the market most likely to care about Retail Sales into Black Friday / Cyber Monday.
In premarket trading, Magnificent Seven stocks are all higher (Alphabet +3.4%, Tesla +1.8%, Amazon +0.5%, Meta Platforms +0.8%, Microsoft +0.4%, Nvidia +0.6%, Apple is flat)
- Alibaba ADRs (BABA) gain 3.9% after the company said its re-branded Qwen AI tool hit 10 million downloads in the first week after it became available to the public.
- Biogen Inc. (BIIB), a drugmaker with an Alzheimer’s treatment on the market, rises 4% after Novo Nordisk said a pill version of Ozempic failed to slow the progression of Alzheimer’s disease.
- Bristol Myers (BMY) climbs 3.8% after peer developer, Bayer AG, said an experimental stroke-prevention drug showed positive results in a late-stage study. Analysts see positive readthrough to Bristol’s drug, milvexian, with Cantor calling the data a “needed win” for the space.
- Green Dot (GDOT) jumps 17% after entering into agreements to be acquired by Smith Ventures and CommerceOne Financial Corporation in a deal that will split the company’s operations between the two buyers.
- MP Materials shares (MP) are up 2.7% after BMO upgraded its recommendation to outperform, saying the stock’s recent pullback offers a buying opportunity into the long-term theme of the US shoring up its rare-earth supply chain.
- Performance Food Group (PFGC) falls 2% after US Foods says it’s no longer pursuing a combination with the company.
- Primoris Services Corp. (PRIM) slips 1.3% after the construction and engineering services company was initiated at Goldman Sachs with a recommendation of sell.
- WeRide Inc. ADRs (WRD) gain 9% after it narrowed its third-quarter net loss on increased robotaxi orders, as it races for a slice of the growing global market for driverless cabs.
In corporate news, Revolut garnered a $75 billion valuation in its latest share sale, a steep increase from the $45 billion price tag it received last year. US officials are said to be having early discussions on whether to let Nvidia sell its H200 artificial intelligence chips to China. Trump said that no television networks should be able to expand, citing the potential growth of what he considers left-wing news outlets.
Futures gained to start the week as the AI narrative was boosted by strong demand for Alibaba’s relaunched AI app, while comments from NY Fed’s Williams on Friday led investors to boost the odds of a rate cut next month to around 70%. Morgan Stanley’s Wilson reckons the recent stock-market pullback is coming to an end and sees a buying opportunity into 2026.
Still, few expect smooth sailing, and as reported overnight, traders are scrambling for downside protection and paying up to lock in S&P 500 gains, especially when it comes to tech. The cost of options on the Invesco QQQ Trust Series 1 ETF is hovering near its highest level since August 2024 versus that for the SPDR S&P 500 ETF Trust.
“There’s still a positive backdrop for the tech sector,” said Kevin Thozet, member of Carmignac Gestion’s investment committee. “Typically, seasonality is pretty good walking into Thanksgiving and the end of the year. So I’m rather risk-on from now on and into the first-quarter of 2026.”
In hedge fund news, Ray Dalio thinks the ‘pod shop’ hedge fund multi-strat model won’t last. Bill Ackman is said to be revving up a long-anticipated plan to hold an IPO for his Pershing Square Capital Management, the FT reported.
European stocks edged higher on Monday, the Stoxx 600 rising 0.2% to 563.34, after their worst weekly drop since early August.Construction and travel shares outperformed, while insurers lagged. Defense stocks also underperform in Europe, although have been offset by gains in construction, auto and travel names. Rheinmetall led a drop in defense stocks after Ukraine signaled progress in reconciling its position with the US on a potential peace deal with Russia. Here are some of the biggest movers on Monday:
- Ubisoft shares surge as much as 15%, the most since December, after the French video game producer announced that it had finalized a deal for Tencent to inject €1.16 billion into its Vantage Studios unit.
- Bayer shares jump as much as 12%, to the highest level since October 2024, after the German company said an experimental stroke-prevention drug called asundexian showed positive results in a late-stage clinical study.
- Vistry shares gain as much as 6.5%, the most since June, after Goldman Sachs initiated the UK homebuilder with a buy recommendation.
- Nemetschek shares climb as much as 4.6%, the most since May, as Jefferies started coverage of the German software firm with a buy rating.
- BMW shares gain as much as 2.7% after after Goldman Sachs initiated the automaker with a buy recommendation. Ferrari and Mercedes shares also gained after being rated new buys.
- Julius Baer shares drop as much as 5.9%, the most since May, after the Swiss lender said 2025 profit would be lower than last year.
- Rheinmetall shares fall as much 5.8%, hitting their lowest level since April, as European defense stocks drop on signs of progress in talks to secure Ukraine’s support for a US-backed peace plan. Leonardo, Thales and Saab also fell.
- M&C Saatchi shares drop as much as 18%, hitting their lowest level since 2021, after warning the US government shutdown has affected trading, prompting the advertising agency to cut its outlook.
Earlier in the session, Asian equities opened the week higher on optimism over a potential Federal Reserve rate cut and a rebound in AI-linked Chinese tech shares traded in Hong Kong. The MSCI Asia Pacific Excluding Japan Index climbed as much as 1.2%, with Alibaba being the biggest contributor to its gain. The company’s shares led a rally in peers after saying its rebranded AI app Qwen hit 10 million downloads in the week after it became available to the public. The Hang Seng Tech Index jumped more than 3% intraday after a four-week losing run. Tencent and Samsung Electronics were other major contributors to the regional index’s advance. Benchmarks in Hong Kong and Australia rose, while Japan was closed for a holiday. Asian markets have been volatile in recent weeks amid uncertainty over the Fed’s easing as well as doubts over the potential for returns from the AI sector that has been attracting vast sums of money.
In FX, the Bloomberg Dollar Spot Index is steady. The euro and Swiss franc vie for top spot among the G-10 currencies, rising 0.2% each.
Treasuries inch higher, with US 10-year yields down 1 bp at 4.05%. European government bonds also edge up. In early US trading long-end tenors outperform, slightly flattening 2s10s and 5s30s curves ahead of the 2-year note auction at 1pm New York time. Auction cycle begins a day earlier than usual ahead of Thursday’s US Thanksgiving Day holiday. European bonds trade steady, including Italian debt after the country’s upgrade by Moody’s Ratings on Friday. Long-end yields are richer by 2bp-3bp with front-end tenors little changed, flattening 2s10s and 5s30s spreads about 2bp; 10-year near session low 4.05% is about 1.7bp lower, outperforming bunds and gilts. $69 billion 2-year note auction has WI yield near 3.50%, within 1bp of last month’s, which tailed by 0.1bp; auction cycle also includes $70 billion 5-year Tuesday and $44 billion 7-year Wednesday
In commodities, WTI crude futures slip 0.7% to $57.70 a barrel as traders weigh the prospect of a Ukraine-Russia peace deal after President Zelenskiy’s chief of staff said discussions demonstrated significant progress in reconciling positions. European natural gas futures drop 3% and below €30 a megawatt-hour for the first time in more than a year. Bitcoin again fell below $86,000 after a weekend rebound and is on track for its worst month since 2022.
The US economic calendar includes November Dallas Fed manufacturing activity (12pm); Fed speaker slate is blank
Market Snapshot
- S&P 500 mini +0.1%
- Nasdaq 100 mini +0.3%
- Russell 2000 mini little changed
- Stoxx Europe 600 little changed
- DAX +0.4%
- CAC 40 -0.1%
- 10-year Treasury yield -1 basis point at 4.05%
- VIX +0.2 points at 23.58
- Bloomberg Dollar Index little changed at 1226.52
- euro +0.2% at $1.1537
- WTI crude -0.6% at $57.73/barrel
Top Overnight News
- Trump is expected to announce as early as Monday a general framework to address healthcare costs, proposed legislation would eliminate zero premium subsidies currently offered under the ACA, according to MS NOW. It was later reported that US President Trump is to sign an executive order on Monday at 4:00pm EST.
- Bessent said they are seeing prices get better and will see an announcement this week on healthcare costs, while he added that inflation is up because of services, not imported goods. Bessent said he expects some prices to come down in weeks and others in months. Furthermore, he said that Republicans should end the filibuster if Democrats close the government again, while he noted the government shutdown caused a $11BN permanent hit to US GDP.
- Trump’s DOGE (Department of Government Efficiency) has disbanded with eight months left to its mandate.
- Texas officials asked the US Supreme Court to allow a pro-Republican electoral map that a lower court blocked.
- JPMorgan Chase (JPM), Citi (C) and Morgan Stanley (MS) are among those that have been notified by SitusAMC that their client data may have been taken: NYT.
- Japan reaffirmed plans to deploy missiles on an island near Taiwan as tensions smolder with China. BBG
- China unveiled details of a global mining initiative with 19 nations in an apparent response to US efforts to rally allies for an alternative rare earth supply chain. BBG
- Early signs on Japan’s annual wage negotiations for next year point to another round of solid pay hikes despite profit pressure from U.S. tariffs, bolstering the case for the BoJ to raise interest rates further. RTRS
- German business confidence unexpectedly dipped this month, Ifo’s expectations index showed. Expectations component coming in at 90.6 for Nov, down from 91.6 in Oct and below the consensus forecast of 91.6. BBG
- US and Ukraine officials say they made progress in peace talks over the weekend, although neither side provide much detail on how the blueprint had evolved from last week’s initial draft. NYT
- Scott Bessent told NBC’s Meet the Press that the Trump administration is working on bringing down US health-care costs and an announcement is planned for this week. BBG
- The Trump administration is working on fallback options in case the Supreme Court strikes down one of his major tariff authorities, looking to replace the levies as quickly as possible. They are studying alternatives, including Section 301 and Section 122 of the Trade Act, which grant the president unilateral ability to impose duties, but these replacements come with risks and could face their own legal challenges. BBG
- President Trump said this week he expects much lower interest rates once he can install a new Federal Reserve chair next May. Growing opposition to a December rate cut inside the central bank suggests he might not get his way. WSJ
- The bond market is straining to absorb a flood of new bonds from tech companies funding their artificial intelligence investments, adding to the recent pressure in markets. Since the start of September, so-called AI hyperscalers Amazon, Google, Meta, and Oracle have issued nearly $90 billion of investment-grade bonds, according to Dealogic, more than they had sold over the previous 40 months. WSJ
- Hedge funds and mutual funds both currently favor Health Care and Industrials. Hedge funds increased their net tilt to Health Care last quarter by 260 bp, the largest increase among sectors. Goldman
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mostly positive following last Friday’s advances on Wall St, where sentiment was lifted as dovish comments from Fed’s Williams rekindled December rate cut hopes, while ‘tremendous’ progress was said to have been made during Ukraine peace talks in Geneva on Sunday, although conditions were quiet amid a sparse overnight calendar and with Japanese markets closed for Labor Day. ASX 200 rallied at the open with outperformance in tech and industrials front running the advances, while there were also some M&A related headlines with Qube surging to a record high on Macquarie Asset Management’s fresh AUD 11.6bln takeover proposal. Conversely, BHP shares were indecisive and eventually trickled lower after it was reported to have made a renewed approach for Anglo American, which was rejected, prompting BHP to abandon its pursuit again. Hang Seng and Shanghai Comp Chinese markets are mixed with gains led by tech strength, although semiconductor names are pressured, including SMIC, following a report on Friday that US President Trump’s team was internally floating selling NVIDIA H200 chips to China.
Top Asian News
- BoJ board member Masu said on Friday that the BoJ is ‘close’ to the decision to raise rates but can’t say which month. Masu stated it is not good for real interest rates to be deeply negative and that Japan’s policy rate is lower than the neutral rate, which he strongly believes they need to change quickly, while he said they won’t wait until after the Spring wage talks to end in raising rates.
- Japan is said to be open to intervening in the currency market “to mitigate the side effects of a weak yen,” according to a government panel member.
- New Zealand PM Luxon vowed to increase the pension saving scheme, according to Bloomberg.
European bourses (STOXX 600 +0.2%) opened stronger across the board, following on from a mostly firmer APAC session and as markets digested the latest geopolitical progress between Ukraine and Russia, whereby US Sec of State Rubio suggested “tremendous progress” has been made. However, as the morning progressed, a hefty bout of pressure took indices to session lows to now display a mixed picture in Europe – a move which lacked catalysts. European sectors opened with a clear cyclical bias. Autos, Travel & Leisure and Basic Resources lead whilst Energy underperforms as the oil complex remains pressure amidst the constructive geopolitical environment; a factor which has led to downside across Defence names, with the likes of Rheinmetall (-2%) on the backfoot.
Top European News
- Smooth End to the Year Now Looks Far Less Likely
- BHP Walks Away From Anglo; Portugal’s TAP
- Europe’s IPO Bankers See a Revival Next Year, for Real This Time
FX
- DXY is a little lower today and trades within a thin 100.08 to 100.29 range. Newsflow has been relatively quiet for the index this morning, but may pick-up later this week as Fed speak and the Fed’s Beige Book will give further insight on the health of the economy.
- EUR/USD has picked up a touch since the European cash open, and has recently made a peak of 1.1540 vs the session low of 1.1503. No clear catalyst for the move itself, but potentially as markets digest the latest bout of geopolitical updates between Russia and Ukraine. Elsewhere, no move after a subdued German Ifo set, which saw Expectations slip below the lower end of analyst expectations.
- Muted price action also in GBP/USD, currently within a narrow 1.3086-1.3111 range. Price action this morning has been sideways, with newsflow light and as traders count down their clocks to Wednesday’s UK Budget. Sky News recently outlined that the UK’s OBR will reportedly say that growth is lower in 2026 and every Parliament year in the Budget. Pertinently, the Treasury hopes to surprise with bigger than expected headroom, an outcome that would be welcome by markets; as a reminder, consensus is in a broad GBP 10-20bln+ range for headroom, vs the GBP 9.9bln Reeves had last time.
- JPY is the underperformer today, likely thanks to the broader risk-tone, but with Japanese participants also away on holiday. Currently towards the upper end of a 156.43 to 156.93 range. Weekend newsflow has been light aside from commentary via Japanese government panel member, who suggested that PM Takaichi is open to JPY intervention. A report which has seemingly been shrugged off by markets, as the JPY continues to weaken.
- Antipodeans are mildly lower vs the Dollar, with no real catalysts driving things for the moment; focus remains on the RBNZ announcement on Wednesday, where a 25bps cut is widely expected.
- Barclays FX month-end rebalancing: strong USD buying against all majors.
Fixed Inc