
Futures Flat As Gold Selloff Extends
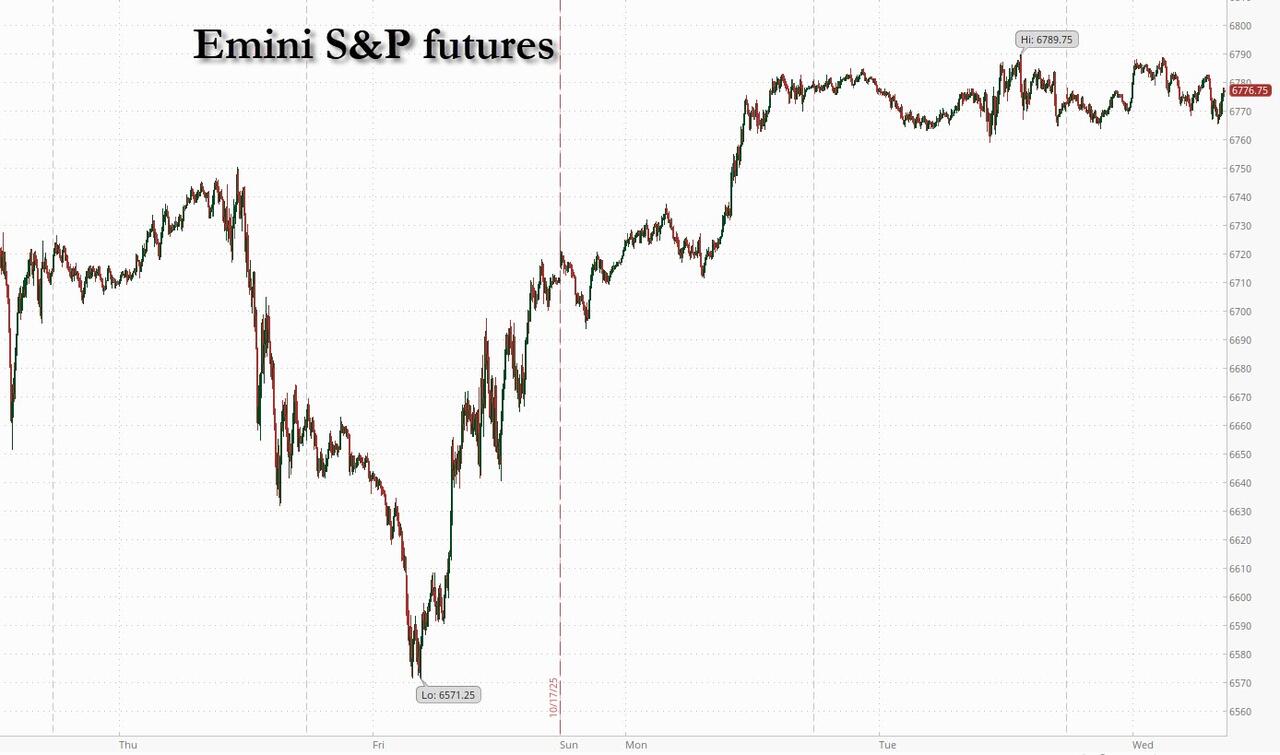
US equity futures are flat again, with tech and small caps lagging as traders parsed the latest earnings reports and corporate news amid worries over trade, the US government shutdown and geopolitical risks. Gold and silver extended declines after Tuesday’s slump. As of 8:00am, S&P futures were unchanged while Nasdaq futures dropped 0.2% after a rally on Wall Street lost steam. Pre-market, Mag7 names are mostly weaker ex-GOOG on its cloud deal. Netflix tumbled 6.8% in premarket trading after the streaming-video company reported third-quarter results that missed across the board despite stronger forecasts. Texas Instruments also plunged about 8% on an underwhelming outlook. Meme stocks are back, with Krispy Kreme among those joining Beyond Meat in the retail trader frenzy today. Mining stocks are weaker pre-market though gold and silver are bouncing off their overnight lows; both are underperforming platinum / palladium. The yield curve shifts lower and the USD continues its recent move higher. USD is +2.5% since making a 52-wk low on Sep 16. The balance of the commodity complex is bid with WTI +1.7% the standout on report that US and India are nearing an accord that could lead India to reduce imports of Russian crude. US / China situation still has aides talking behind closed doors as Trump / Xi remain likely to meet next week. There is no macro today .
In premarket trading, Netflix and Texas Instruments shares are both lower after disappointing results, with Tesla and IBM among the big names to watch later. The EV maker is expected to post a 25% drop in quarterly profits — but traders may not care. The shares have more than doubled in the past year on AI hopes.
- Mag 7 stocks are mostly lower. Alphabet (GOOGL) rises 1.8% as Anthropic is in discussions with Google about a deal that would provide the artificial intelligence company with additional computing power valued in the high tens of billions of dollars, according to people familiar with the matter (Tesla -0.2%, Nvidia +0.06%, Meta -0.1%, Microsoft +0.2%, Apple -0.6%, Amazon -1.3%).
- Alector (ALEC) tumbles 50% after the drug developer said a late-stage trial of its lead asset as an investigative treatment for dementia failed to meet a primary endpoint.
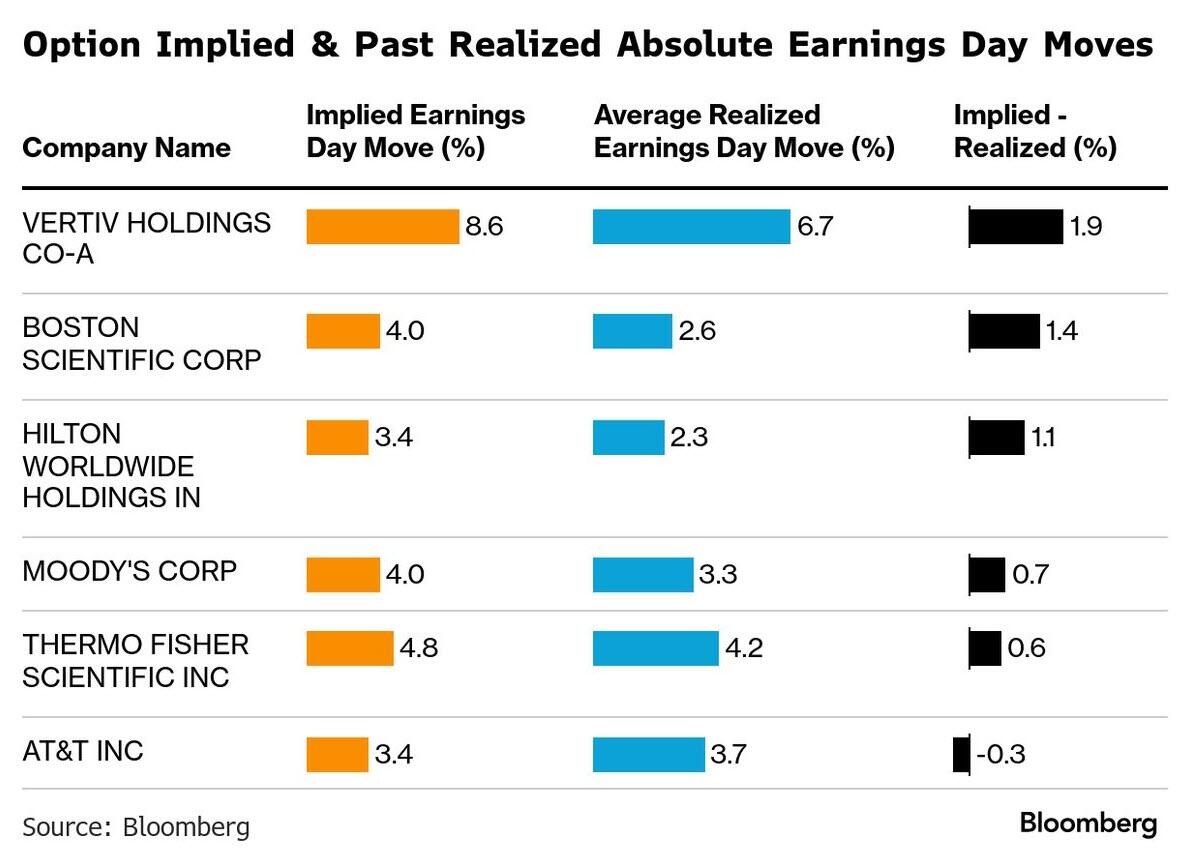
- AT&T Inc. (T) rises 1.4% after the company added more mobile-phone and home internet subscribers this summer than analysts expected.
- Avadel Pharmaceuticals (AVDL) gains 4% after Alkermes agreed to buy the company for up to $20 per share.
- Beyond Meat Inc. (BYND) soars 85%, boosting its four-day rally to almost 1,300%, in an echo of the meme-stock frenzies that periodically roil the market.
- DraftKings (DKNG) climbs 3% after the sports betting company said it acquired predictions platform Railbird for an undisclosed amount.
- Intuitive Surgical (ISRG) rallies 16% after the robotic-surgery company boosted its worldwide da Vinci procedure growth forecast for the full year.
- Manhattan Associates (MANH) falls 7% after the supply-chain software company posted a key metric — “remaining performance obligations” — for the third quarter that fell short of estimates.
- Mattel Inc. (MAT) is down 5% after the company reported third-quarter sales and earnings that missed analysts’ estimates as US retailers delayed orders due to uncertainty over President Donald Trump’s tariff policies.
- Netflix (NFLX) falls 7% after the streaming-video company reported third-quarter results it said were hurt by a tax dispute with Brazil.
- Texas Instruments (TXN) drops 7% after the chipmaker gave an outlook that is weaker than expected. The outlook indicates that some customers are slowing orders as they navigate mounting trade tensions.
- Vertiv Holdings (VRT) is up 6% after the company boosted its adjusted earnings per share guidance for the full year; the guidance beat the average analyst estimate.
- Warner Bros. Discovery Inc. (WBD) gains 2% after saying it’s considering a possible sale of the company after receiving unsolicited interest from multiple parties. Netflix Inc. and Comcast Corp. are weighing bids for parts of the media and entertainment company, according to people with knowledge of the matter.
In other company news, Anthropic PBC is said to be in talks with Alphabet’s Google about a deal that would provide the AI company with additional computing power valued in the high tens of billions of dollars. Apple’s iPhone Air got a subdued response from consumers in China.
Early US earnings point to the best corporate results in four years, with 85% of companies reporting beats. Despite recent de-risking amid concerns over trade and credit, stock exposure among global macro hedge funds and long-only strategies remains at the highest in over a year, according to Barclays Plc. Drawdowns have been short-lived as investors see them as opportunities to add risk to their portfolios.
Earnings will “play a decisive role in determining whether the rally can be sustained,” said Linh Tran, a market analyst at XS.com. “Profit expectations for major tech companies have been revised upward, while consumer and financial sectors may benefit from resilient demand and higher interest margins. If corporate results continue to outperform forecasts, this could help the S&P 500 extend its gains into Q4.”
Markets are also keeping one eye on trade news ahead of the resumption of US-China talks. Six months into Trump’s trade war, the resilience of Chinese exports is proving just how essential many of its products remain even after US levies of 55%.
Gold fell more than 2%, closing in on $4,000 an ounce and deepening its worst intraday drop in more than a dozen years in the previous session, amid concerns its rally had run too far, too fast. Silver also declined following Tuesday’s 7.1% fall. Gold's drop on Tuesday drove the VanEck Gold Miners ETF down 9.4% in its biggest drop since 2020. Still, gold mining stocks are still on track for their biggest ever annual gain over the S&P 500.
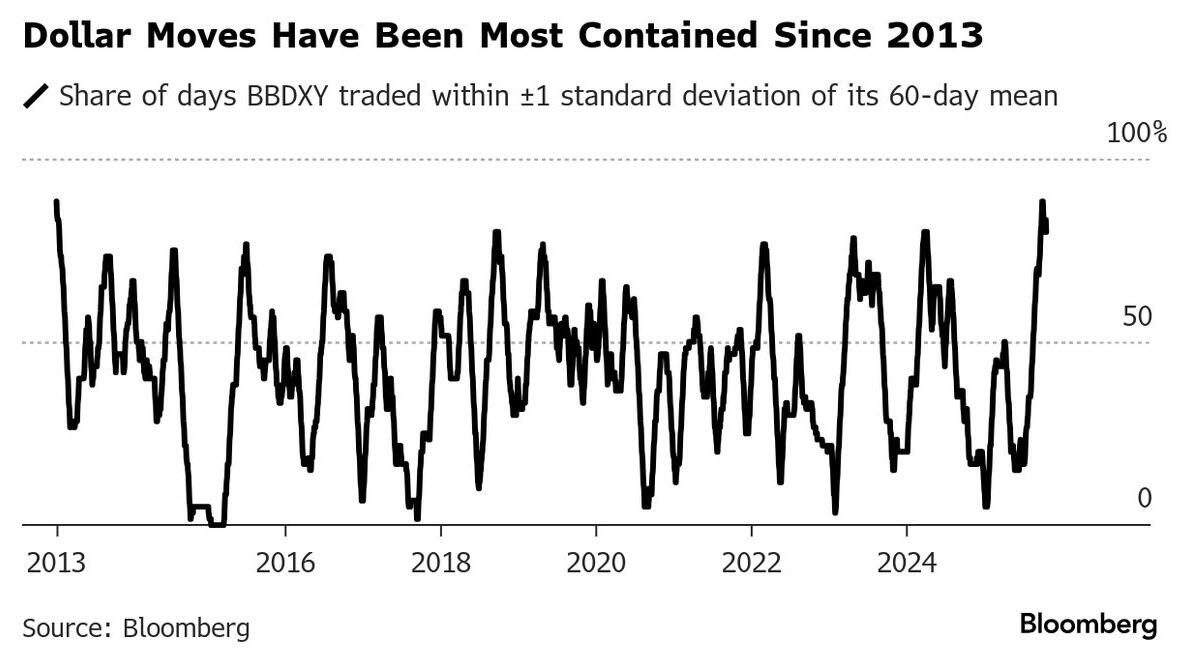
Bond traders are preparing for yields to drop further even as the 30-year sank to its lowest in six months on Tuesday. The cost of protection against a bigger decline in yields across the curve is rapidly rising, according to pricing of options wagers. Traders are piling into some risk-off assets as the US government shutdown becomes the second longest on record and amid renewed concerns over the credit market. Meanwhile, dollar trading has become unusually subdued, with the Bloomberg Dollar Spot Index remaining within one standard deviation of its average for about 80% of the time over the past 60 trading days, according to data compiled by Bloomberg.
In Europe, the Stoxx 600 index dipped, with consumer products and services leading declines after results from L’Oreal SA, Hermes International SCA and Adidas AG failed to meet lofty expectations. Energy stocks led gains as crude oil rose. UK stocks got a boost with the FTSE 100 rising 0.7% after UK CPI surprised to the downside as traders ramp up bets on an interest-rate cut by the Bank of England before year end. Among companies reporting in Europe on Wednesday, Barclays Plc gained after raising its earnings guidance and unveiling a £500 million buyback. Akzo Nobel NV slumped after the paintmaker lowered its earnings outlook, with customers more hesitant to spend amid rising global tariffs and softer economic conditions. Here are the biggest movers Wednesday:
- Precious metals miners in South Africa and Europe rose on Wednesday as gold and silver prices steadied, after suffering their steepest selloffs in years.
- Barclays shares rise as much as 4.1% after the UK lender increased its 2025 guidance and announced a £500 million share buyback, with investors looking beyond an increased provision for motor finance
- Heineken shares rise 2.3% as analysts say a soft quarterly print was no worse than expected. The company’s move of Ebit growth guidance to the lower end of the range had been foreseen, according to consensus views
- Handelsbanken gains as much as 2.1% after posting a slight beat to net interest income (NII) in its third-quarter report. Lower-than-expected costs also contributed to a solid showing from the Swedish lender
- European chipmakers slip on Wednesday after US peer Texas Instruments forecast 4Q sales below estimates, signaling a delay in the rebound of the automotive and industrial chip sector
- ITV shares plummet as much as 12% after the broadcaster’s largest shareholder Liberty Global cut its stake in half after offering shares at a discount
- L’Oreal shares fall as much as 8%, the steepest drop in a year, after the cosmetics company reported third-quarter like-for-like sales that fell short of elevated market expectations
- Hermes falls as much as 5% after sales at constant exchange rates for the third quarter showed double-digit growth in most regions, but key division leather goods slightly missed estimates, while valuation premium is stretched, according to analysts
- DNB Bank shares drop as much as 4.3%, the most since July, after the Norwegian lender posted a disappointing third-quarter report, according to analysts, who flagged misses on net interest income (NII) and fee
- Adidas shares dip as analysts say the sportswear maker’s increased full-year earnings forecast was only in-line with consensus and note a slight miss in third-quarter sales
- TeamViewer shares slump as much as 24% to a record low after the software maker reduced its annual recurring revenue guidance for this year and sales outlook for next year
Asian stocks fell, weighed down by technology shares as investors rushed to lock in gains amid doubts about the sector’s staying power. The MSCI Asia Pacific Index dropped as much as 0.6% before paring some losses, with TSMC, SoftBank Group and Alibaba among the biggest drags. Shares in Hong Kong and Vietnam declined, while South Korea’s Kospi rose. Chipmakers and other AI-related stocks in Asia, including SoftBank, declined after Texas Instruments presented a disappointing outlook, which added to concerns that the sectors’ shares may have been running too hot. Precious-metal stocks also tumbled after gold and silver posted their steepest selloffs in years. The slide in Hong Kong and mainland Chinese stocks came despite a bullish long-term call from Goldman Sachs Group Inc., which predicted key stock gauges may gain 30% by the end of 2027. The strategists argued the upside will be supported by pro-market policies, rising profits and strong capital flows. Here Are the Most Notable Movers
- Bangkok Bank shares advance after the lender’s third-quarter net income rose 11% on year, beating the average analyst estimate, partly driven by investments.
- LG Chem Ltd. shares surged by the most in five years after Palliser Capital UK disclosed a stake in the firm and urged changes, in a sign that overseas activists are starting to wade back into South Korea.
- IHI shares climb as much as 5.5% to ¥2,995 after Mizuho Securities raised its target price to ¥3,300 from ¥1,071, saying it expects growth in the civil aero engines business and expansion of defense-related operations.
- Laopu Gold shares fall as much as 8.1%, the most since Sept. 10, after the Chinese jewelry seller agreed to issue about 3.71 million new H shares at HK$732.49 apiece in a placement.
- Pop Mart shares rise as much as 7.9% after the toymaker’s third quarter sales growth of as much as 250% year-on-year came amid investor worries over the possible fading popularity of its collectible toys.
- Innovent Biologics shares rise as much as 9.9% in Hong Kong after the company said it will receive a $1.2 billion upfront payment, including an equity investment, as part of a strategic collaboration with Takeda Pharmaceutical to develop cancer therapies.
- Meituan shares drop 0.5% as JPMorgan cuts its target price, saying the company may face worst-than-expected pressure in its 3Q and 4Q results due to competition in China’s food delivery market and its expansion overseas.
- Taiheiyo Cement shares gain as much as 6% in early Tokyo trading, the most since April 10, following a report in Nikkei that Palliser Capital has taken a stake of over 3%.
In FX, the Bloomberg Dollar Spot Index rose 0.1%, taking gains into a fourth straight day; the index’s thin gains were led by the US currency’s advance versus the pound, which stumbled after data showing steady UK inflation raises speculation of an interest-rate cut in December. A 1% slide in gold prices also supported the greenback, suggesting that investors still see the currency as a viable haven. The pound fell 0.4% against the dollar and is the clear G-10 underperformer.
In rates, treasury yields sliding again, dropping more than 4bps with 10-year around 3.93%, near Tuesday’s low. They trail steep gains for gilts, where 2-year yields fell more than 10bp to 14-month low after UK headline, core and services CPIs fell short of estimates. UK yield curve is notably steeper as market prices in an increased 70% chance Bank of England cuts rates a quarter-point by December. The US session includes 20-year bond reopening: the $13 billion 20-year bond reopening, first coupon auction in more than a week, has WI yield near 4.510%, about 10bp richer than last month’s 20-year sale, which stopped through by 0.2bp
In commodities, WTI crude oil futures are up about 2%, which along with the 20-year auction creates resistance to lower Treasury yields. Oil is higher on report that US and India are nearing an accord that could lead India to reduce imports of Russian crude. Spot gold is down $50, having recovered from an earlier nosedive toward $4,000/oz. Silver dips 0.7% while Bitcoin is down 2.4%.
The US economic calendar calendar is blank, and Fed’s external communications blackout ahead of the Oct. 29 Fed policy decision began Saturday. Earnings after the close include Tesla and IBM.
Market Snapshot
- S&P 500 mini little changed
- Nasdaq 100 mini -0.2%
- Russell 2000 mini -0.2%
- Stoxx Europe 600 -0.2%
- DAX -0.3%, CAC 40 -0.6%
- 10-year Treasury yield -1 basis point at 3.96%
- VIX +0.1 points at 17.96
- Bloomberg Dollar Index little changed at 1212.96
- euro little changed at $1.1596
- WTI crude +1.7% at $58.19/barrel
Top Overnight News
- The US government shutdown is now the second-longest in history, and with Trump expected to head to Asia later this week, lawmakers and congressional aides see a real possibility of the closure extending into November. BBG
- US companies are beating earnings expectations at the highest rate in over four years, with 85% surpassing profit estimates in the third quarter so far. BBG
- Trump said he won't meet with Democratic leaders unless the government is reopened.
- Trump's administration plans to release over USD 3bln in aid to US farmers previously frozen due to government shutdown: WSJ.
- US has offered energy companies access to nuclear waste that they can convert into fuel for advanced reactors in an attempt to break Russia’s stranglehold over uranium supply chains: FT.
- Bessent is facing mounting pressure to justify Washington’s multibillion dollar rescue of Argentina as a political backlash builds over the administration’s efforts to support Milei. The Treasury secretary has taken the lead in managing Trump’s effort to provide financial support for Milei’s libertarian government, which the US sees as a crucial Latin American ally, through a package of measures designed to prop up its economy and its currency, the peso. FT
- China is demanding some US semiconductor firms submit sensitive information about their sales in the world’s largest chips market as part of its probe of American suppliers. BBG
- As Japan's new premier Sanae Takaichi got to work on Wednesday, her government began finalising a purchase package, including U.S. pickups, soybeans and gas, to present to President Donald Trump in trade and security talks next week, two sources said. RTRS
- Japan's new Prime Minister Sanae Takaichi is preparing an economic stimulus package that is likely to exceed last year's $92 billion to help households tackle inflation, government sources familiar with the plan said on Wednesday. RTRS
- Indonesia unexpectedly leaves rates unchanged at 4.75% (the Street was anticipating a cut to 4.5%). BBG
- India and the United States are nearing a long-stalled trade agreement that would reduce U.S. tariffs on Indian imports to 15% to 16% from 50%, India's Mint reported on Wednesday citing three people aware of the matter. The deal, which hinges on energy and agriculture, may see India gradually scale back its imports of Russian crude oil. RTRS
- The U.K.’s annual rate of inflation in September unexpectedly held at the pace of the previous month, raising the chance that Bank of England policymakers could cut interest rates later this year, despite price rises remaining at a level still well above the central bank’s target. CPI comes in cooler than anticipated at +3.8% Y/Y on the headline (vs. the Street +4%), +3.5% on core (vs. the Street +3.7%), and +4.7% on services (vs. the Street +4.8%). WSJ
Trade/Tariffs
- US President Trump reiterated that the November 1st tariffs on China will be about 155% and that higher tariffs on China won't be sustainable for them, while Trump also said he spoke with India's PM Modi on Tuesday and talked about trade.
- South Korean chief presidential policy aide said South Korea and the US stand apart on a couple of matters in tariff talks.
- South Korea Minister for Trade Yeo expressed concern in a call with China's Li Chenggang regarding Beijing's shipbuilding curbs, while he asked Li to swiftly lift sanctions on South Korea shipbuilder Hanwha Ocean and discussed China’s rare earths export restrictions.
- India and the US are closing in on a long-pending trade deal that could slash current tariffs from Indian exports to between 15-16% from 50%, according to Mint citing three people aware of the matter.
A more detailed look at global markets courtesy of Newsquawk
APAC sto