

Futures Flat Ahead Of Two Huge Days As Gold Slides
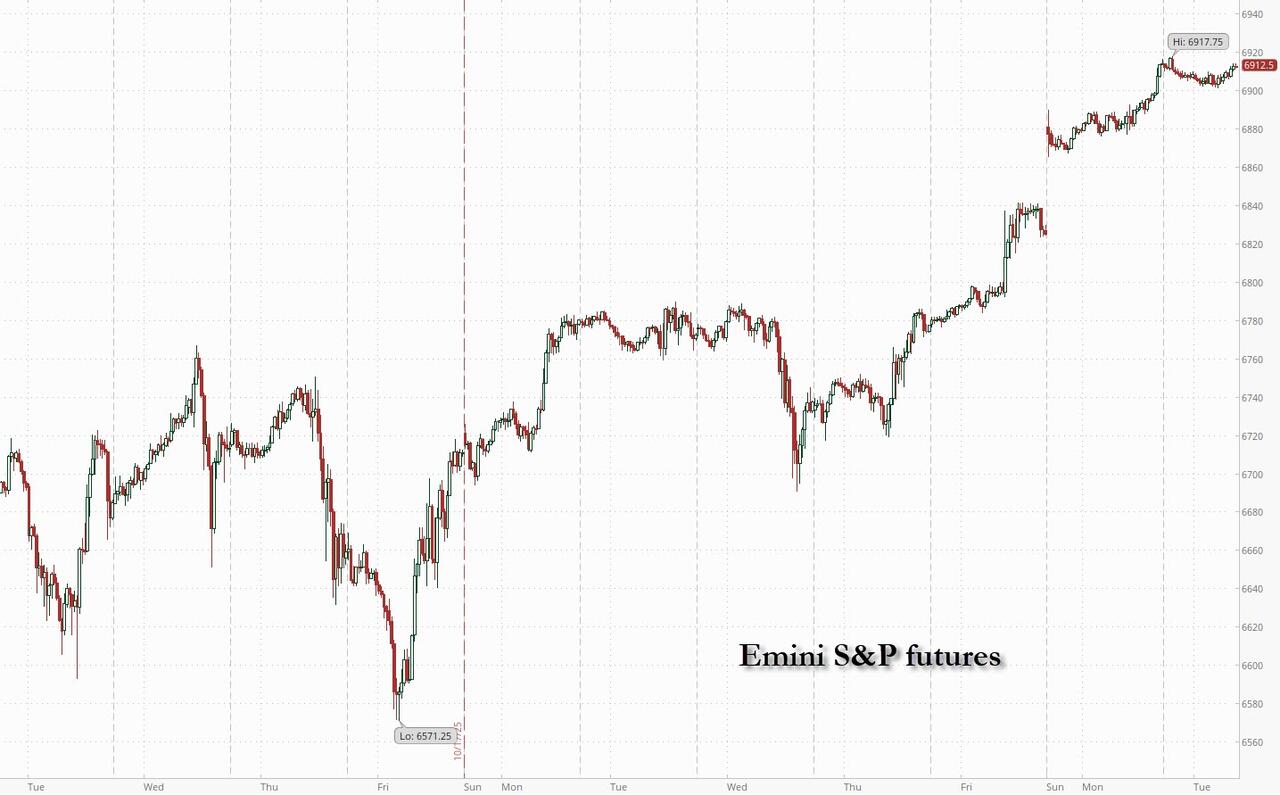
The record-busting stock rally paused ahead of two huge days which include an avalanche of Mag7 earnings, central bank meetings, and the Trump-Xu summit summit. As of 8:00am ET, S&P 500 futures are flat with Nasdaq futures up 0.1% as Mag7 names are flat to up small premarket. Cyclicals underperform, dragged by commodity-related Equities. Europe's Stoxx 600 falls 0.3% dragged by real estate, construction and poorly-received results from BNP Paribas and Novartis. The Trump admin and Westinghouse sign $80bn deal to build nuclear reactions with Brookfield / Cameco to construct facilities. Google / NextEra sign a deal to restart a nuclear plant to power Google’s AI needs. Treasuries edge higher while the Bloomberg Dollar Spot Index down, with yen outperforming following the Trump-Takaichi summit and supportive comments on the currency. The commodity complex is weaker as both Energy and Precious Metals are down 1.7% – 2% with Ags / Steel in positive territory. Oil prices slide, with WTI testing $60/barrel and Brent below $65. Gold extends declines, having fallen below $4,000/oz yesterday; it dropped as low as $3,900 before rebounding. Though the government remains shut we are likely to receive regional Fed activity indicators, though these prints have not proven to be market moving. Keep an eye on housing prices given the recent weakness in the CPI’s OER metric
In premarket trading, Magnificent 7 stocks are mostly higher (Amazon +0.8%, Tesla +0.7%, Alphabet +0.4%, Microsoft +0.2%, Meta +0.3%, Nvidia +0.2%, Apple -0.2%)
- Amkor Technology (AMKR) falls 4% after the semiconductor manufacturing company reported third-quarter results that beat expectations and gave an outlook.
- Cameco (CCJ) gains 13% on its involvement in a strategic partnership with the US government and other firms that will see at least $80b of new nuclear reactors constructed in the US.
- Confluent (CFLT) rises 10% after the software company reported third-quarter results that beat expectations and raised its full-year forecast for adjusted earnings.
- Custom Truck One Source (CTOS) falls 6% after the supplier of specialty trucks and equipment posted third quarter revenue that missed estimates.
- NXP Semiconductors (NXPI) is up 2% after the provider of chips for automakers and industrial customers gave a stronger-than-anticipated forecast for the current period.
- PayPal Holdings Inc. (PYPL) rises 15% after the company raised its full-year earnings guidance and announced a tie-up with OpenAI to embed its digital wallet into ChatGPT.
- Qorvo (QRVO) climbs 10% as the Information reported that Apple-supplier Skyworks Solutions held talks in recent months to buy its rival.
- Royal Caribbean (RCL) falls 7% after the cruise operator’s fourth quarter adjusted EPS forecast fell short of the consensus estimate. The company said recent adverse weather, and the unplanned extension of the temporary closure of one of its exclusive destinations in Haiti will impact results.
- SoFi Technologies (SOFI) rises 3% after the online lender boosted its adjusted net revenue forecast for the full year.
- UnitedHealth Group Inc. (UNH) gains 3% after the company beat Wall Street expectations for third-quarter earnings and raised its outlook for the year, a sign that the health conglomerate has stabilized after a major meltdown.
- United Parcel Service Inc. (UPS) jumps 8% after third-quarter profit topped Wall Street’s estimates as the courier’s plan to reshape its delivery network starts to show results. Peer FedEx (FDX) gains 3%.
- Waste Management (WM) is down 3% after the waste management services company said its 2025 revenue outlook is now expected to be approximately $25.275 billion, the low end of the prior guidance range. The reduced guidance trailed the average analyst estimate.
In corporate news, Amazon plans to cut its corporate workforce by about 14,000 roles. Goldman aims to significantly expand its presence in Saudi Arabia, while Jamie Dimon said he continues to cajole JPMorgan staffers into the office because junior bankers aren’t able to learn as much when working from home. Uber is said to be planning to invest in the Hong Kong listings of Pony AI and WeRide.
Easing trade tensions have helped fuel the stock rally, with US companies largely unscathed by tariffs so far. The S&P 500 is on course for the most sales beats in about four years. That optimism faces a reality check this week as investors look to the Fed meeting for clues on the path of rate cuts, while major technology firms including Meta Platforms Inc. and Microsoft Corp. may reveal whether the artificial intelligence-fueled earnings momentum can be sustained.
“My central scenario is that the upward trend holds: there’s lots of liquidity out there, the earnings season is good and a Fed rate cut is expected and priced in,” said Stephane Deo, a senior portfolio manager at Eleva Capital in Paris. “There’s one risk, however, that may lay in the tech sector if analysts keep on aggressively pricing double-digit growth for some mega stocks.”
Overnight, Trump continued his trade tour of Asia and praised Japan’s new PM; Trump hailed the alliance between the US and Japan while the two nations pledged cooperation on defense and shipbuilding. Separately, Goldman’s Solomon, speaking at an investment summit in Saudi Arabia, said he expects the “incredible” pickup in M&A and IPO activity to continue, while recent issues in credit markets have been one-offs. BlackRock CEO Larry Fink said at the same event that the US is the place to be overweight for at least the next 18 months.
Equity bulls seems to agree. According to BBG, they’re lining up to wager that the S&P 500 will surge past the 7,000 level now that it looks as if a bout of volatility has passed. And Nasdaq 100 positioning has increased significantly as investors add new long risk, reversing the fading momentum seen in recent weeks, according to Citigroup strategists.
The most crucial reports of the season are still to come, but so far things are looking good. Almost 70% of S&P 500 members to have reported so far have exceeded sales estimates, according to Bloomberg Intelligence — the highest proportion of positive surprises in about four years. And 85% of benchmark companies have managed to beat on earnings, while just 14% have missed.
In Europe, the Stoxx 600 falls 0.3% as underwhelming quarterly results from heavyweight Swiss drugmaker Novartis and French banking group BNP Paribas weigh on the Stoxx 600 index, while earnings boost Nordex, Capgemini and HSBC. Here are the biggest movers Tuesday:
- Nordex gains as much as 15% after the renewable-energy equipment firm lifted its Ebitda margin forecast for the full year, citing strong operational execution across its projects and service-business segment
- Capgemini shares jumped as much as 9.6%, the most in six months, after the IT services firm raised its full-year revenue guidance and reported a stronger-than-expected third quarter
- HSBC shares rise as much as 3.2% in London, most since May, after the banking firm raised its profitability outlook for 2025 while reporting what analysts say are good quarterly results
- Storytel gains as much as 19%, the most since January 2024, after the Swedish audiobook and publishing group reported earnings which blew past analysts expectations, with a full-year guidance upgrade providing further boost
- Airtel Africa shares surge as much as 11%, hitting an all-time high after the telecoms company posted results ahead of expectations in the first half
- Amundi shares rise as much as 1.5% as the investment management group reports net income ahead of analysts’ forecasts for its third quarter
- Symrise shares drop as much as 6.4%, the most since July, after the diversified chemicals manufacturer cut its organic sales forecast for the full year
- Bucher shares fall as much as 7.9%, hitting the lowest level since April, after the Swiss building materials firm changed the wording of guidance for 2025 operating profit margin to “lower” from “somewhat lower”
- Novartis shares drop as much as 4.1%, the most since April 9, after the Swiss drugmaker reported weaker-than-expected earnings for the third quarter and maintained its outlook for the year
- BNP Paribas shares fall as much 4.3% after the bank reported mixed 3Q figures, where overall revenues fell short, but the lender’s capital position impressed
- Wartsila falls as much as 9.3%, the most since April, before trimming losses. The Finnish marine and energy equipment maker reported its latest earnings, with analysts calling it a mixed report
- Truecaller falls as much as 16%, the most in two years, after the Swedish caller-ID platform reported disappointing third-quarter earnings. Analysts say the results were weighed down by poor advertising sales
Earlier in the session, a key Asian stock benchmark slipped, led by declines in South Korea and Japan, as investors positioned ahead of key interest rate decisions, global megacap earnings and a summit between the leaders of the world’s two largest economies. The MSCI Asia Pacific Index fell 0.5%, pressured by tech names including Samsung Electronics and Tencent. Australian drugmaker CSL was the biggest drag, plunging to a near seven-year low after delaying plans to spin off its vaccines business. Investor enthusiasm was on display Monday as the regional gauge hit a new record high. But with key developments ahead — including policy decisions from the Federal Reserve and Bank of Japan, earnings from five of the US Magnificent Seven, and a potential trade deal between Donald Trump and Xi Jinping — markets now face a moment of pause and reassessment. Shares also slumped in China, Australia and Indonesia. Stocks gained in Vietnam and Singapore.
In FX, Bloomberg Dollar Spot Index down, with yen outperforming following the Trump-Takaichi summit and supportive comments on the currency.
In rates, treasuries are narrowly mixed, keeping yields within a basis point of Monday’s closing levels. US 10-year is little changed at around 3.98% with Germany’s likewise steady and UK’s outperforming by about 1bp; curve spreads are also within a basis point of Monday’s close following muted price action during Asia session and London morning. Gilts outperform as UK borrowing costs approach lowest levels this year amid signs of cooling inflation. Focal points of Tuesday’s US session include 7-year note auction along with housing and consumer confidence data. This week’s Treasury coupon auctions conclude with $44 billion 7-year note sale at 1pm New York time, following good demand for Monday’s 2- and 5-year auctions.
In commodities, gold extends declines, having fallen below $4,000/oz yesterday; it’s currently trading down $77/oz to $3,904/oz.
Today's US economic calendar calendar includes August FHFA house price index and S&P Case-Shiller home prices (9am), October Richmond Fed manufacturing index and Conference Board consumer confidence (10am) and Dallas Fed services activity (10:30am)
Market Snapshot
- S&P 500 mini little changed
- Nasdaq 100 mini little changed
- Russell 2000 mini -0.4%
- Stoxx Europe 600 -0.2%
- DAX -0.1%, CAC 40 little changed
- 10-year Treasury yield -1 basis point at 3.97%
- VIX +0.1 points at 15.88
- Bloomberg Dollar Index little changed at 1211.08
- euro little changed at $1.165
- WTI crude -1.9% at $60.15/barrel
Top Overnight News
- Japan revealed potential projects for its $550 billion US investment fund, including ventures by SoftBank, Toshiba, and Westinghouse in AI, energy and critical minerals. The US will decide which projects will make the cut. BBG
- Daily share price swings worth hundreds of billions of dollars are becoming commonplace on Wall Street, highlighting the risks to investors as the Big Tech companies powering the stock market’s relentless rally grow more volatile. Individual stocks shave gained or lost more than $100bn in market value in a single day 119 times so far this year, the highest annual total on record. FT
- The nation’s largest federal workers’ union called for Congress to end the shutdown, now in its fourth week, putting new pressure on Senate Democrats who have repeatedly blocked a Republican measure that would reopen the government. WSJ
- The Federal Reserve is expected to end a 3 year phase of quantitative tightening this week, easing pressures on banks amid concerns that funding is getting too tight in money markets: FT, after ZH
- US President Trump says he will send in "more than the National Guard" into US cities if required.
- The EU is in talks with anchor investors including Denmark’s EIFO and the Novo Nordisk Foundation for its €5 billion fund to support AI, quantum and other strategic technologies, people familiar said. About €3 billion has already been committed. BBG
- Japanese PM Sanae Takaichi has pledged to reinforce Japan’s defense capabilities as she and President Donald Trump vowed to bring the US-Japan security alliance into a “new golden age.” FT
- South Korea’s economy accelerated at a stronger-than-expected pace in the third quarter, driven by government stimulus and exports’ resilience despite tariff headwinds. South Korea’s Q3 GDP comes in ahead of expectations at +1.7% Y/Y (vs. the Street +1.5%). WSJ
- PYPL +11% pre mkt on news that PayPal and OpenAi have signed an agreement to embed the payments wallet into ChatGPT. Starting next year, PayPal buyer and sellers will be able to complete transactions through the AI tool. BBG
- U.S. air travel turmoil deepened as nearly 7,000 flights were delayed nationwide on Monday, with air traffic controller absences surging as the federal government shutdown reached its 27th day. RTRS
- While the recent short squeeze has been unusually sharp, the still-elevated magnitude of short interest signals more room to run. Data released by FINRA shows that, as of last Wednesday, the median S&P 500 stock carried short interest equal to 2.3% of market cap. This ranks in the 67th percentile of the past 30 years and far above the 1.5% share that marked the peaks of the squeezes in 2000 and 2021. Goldman
Corporate News
- US equity futures (ES U/C NQ U/C RTY -0.3%) are mixed with the ES and NQ trading around the unchanged mark whilst the RTY is subdued. The DJIA saw some modest upticks following strong Q3 results from UnitedHealth, after the Co. beat on headline metrics and upgraded FY guidance.
- UnitedHealth Group Inc (UNH) Q3 2025 (USD): Adj. EPS 2.92 (exp. 2.84), Revenue 113.2bln (exp. 113.05bln), raises FY Adj. EPS to 16.25 (prev. guided 16.00).
- United Parcel Service Inc (UPS) Q3 2025 (USD): Adj. EPS 1.74 (exp. 1.3), Revenue 21.40bln (exp. 20.79bln); sees Q4 revenue around 24bln (exp. 23.87bln).
- Amazon (AMZN) announces organisational changes across the Co. that will impact some teammates; reduction in corporate workforce of approx. 14k roles. "We expect to continue hiring in key strategic areas while also finding additional places we can remove layers, increase ownership, and realise efficiency gains".
- PayPal (PYPL) signs deal with OpenAI to become the first payments wallet in ChatGPT, via CNBC
Trade/Tariffs
- US President Trump and Japanese PM Takaichi signed an agreement on the US-Japan alliance and framework for securing the supply of critical minerals and rare earths. White House said that the US and Japan plan to use economic policy tools and coordinated investment to accelerate the development of diversified, liquid, and fair markets for critical minerals and rare earths. Furthermore, within six months of the framework’s date, Japan and the US intend to take measures to support projects that generate end products for delivery to buyers in the US, Japan, and like-minded nations, while they will work to secure their critical minerals and rare earths supply chains by addressing non-market policies and unfair trade practices.
- Japanese senior government official said Japan and the US governments are preparing to release a fact sheet that includes potential investment projects in the US, while the fact sheet will include power generation and automobile-related products as potential investment projects and is expected to include company names such as Mitsubishi Heavy Industries.
- China and ASEAN signed a free trade area 3.0 upgrade protocol, according to Xinhua.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks failed to sustain the momentum from the record highs on Wall St and were mostly subdued amid some profit taking and positioning ahead of this week's upcoming risk events. ASX 200 retreated in the absence of major catalysts and was dragged lower by weakness in healthcare, tech and miners. Nikkei 225 pulled back from all-time highs amid a firmer currency and despite US President Trump's visit to Japan, where he met with PM Takaichi and signed an agreement on US-Japan alliance and securing supply of critical minerals and rare earths. Hang Seng and Shanghai Comp were choppy ahead of the major risk events later in the week including the central bank decisions and the Trump-Xi meeting, while participants also reflected on recent comments from PBoC Governor Pan that they will resume government bond purchases and sales in the open market, as well as continue to maintain a supportive monetary policy stance and implement a properly loose monetary policy.
Top Asian News
- China releases proposal for 15th five-year plan, according to Xinhua; says China faces difficult challenges in global trade order, economic growth potential to be fully released. Vows to strengthen national security barriers. To combine an efficient market with a proactive government. Tech self-reliance to be greatly improved. To deepen reform and continue high-quality development. Economic growth potential to be fully released. Domestic demand continues to play a stronger role. Economic growth remains within a reasonable range. Faces difficult challenges in the global trade order. To foster emerging sectors and future industries. To improve the level of tech self-reliance. To promote coordinated development of the economy, society. To drive reasonable economic growth in the next five years. Transformation to accelerate breakthroughs. To increase international influence significantly by 2035. To drive a significant consumption rate among residents. Vigorously boost consumption. To build a modernised infrastructure facilities system. Enhancing fiscal sustainability. Give full play to the role of proactive fiscal policy. To form growth model more driven by consumption a