
Futures Rise, S&P Set For 8th Gain In 9 Days
US equity futures rise, trading less than a percent away from a new record high amid signs of a leadership rotation with Big Tech not leading the bounce this time. As of 8:00am ET, S&P and Nasdaq 100 contracts are higher by about 0.1% after climbing in seven of the past eight sessions and extend on Wednesday's gains when bad news was good news as a soft ADP jobs report bolstered expectations for a Fed rate cut next week. Challenger job cuts data for November showed job cuts fell 53% to 71,321 last month from October, but rose 24% from the 57,727 job cuts announced in the same month last year. Pre-market, Mag 7 were up a touch, led by TSLA (+0.9%), META (+0.6%) and NVDA (+0.5%). Salesforce is higher after its forecast beat and it gave a positive view on AI adoption. Bond yields were up modestly, USD unchanged, reversing an earlier drop to a one month low. Commodities are mixed: Oil and base metals are mostly higher; gold/silver are lagging. Bitcoin trades around $93, rebounding almost $10K from its low just days ago. Today's calendar includes November Challenger jobs cuts (7:30am), weekly jobless claims (8:30am) and September factory orders (10am)
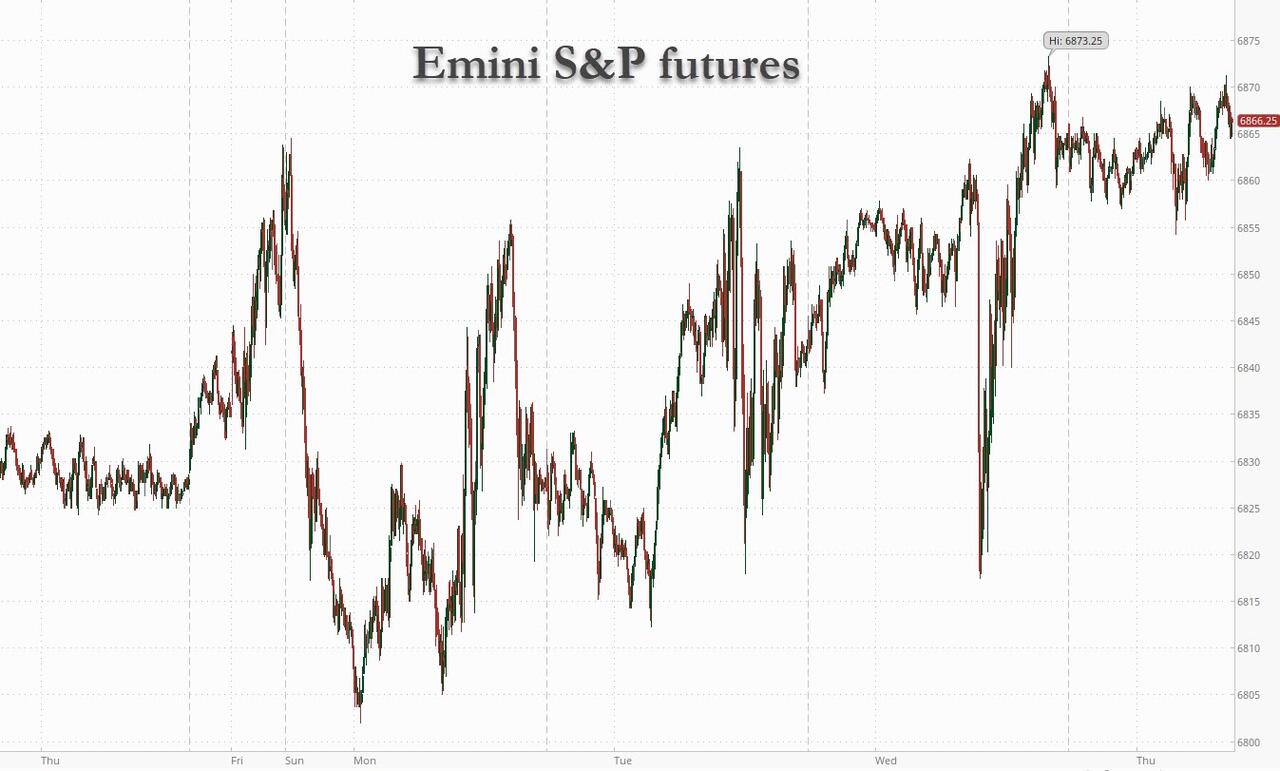
In pre-market trading, tech stocks were broadly steady with all Magnificent Seven megacaps apart from Apple posting modest gains, while Salesforce climbed on signs that customers are embracing its artificial intelligence tools.
- Mag 7 stocks mostly higher (Tesla +0.6%, Nvidia +0.4%, Meta +0.8%, Alphabet +0.6%, Microsoft +0.4%, Amazon +0.1%, Apple -0.04%)
- Axogen (AXGN) rises 5% after the provider of medical and surgical instruments said the FDA approved its biologics license application for its Avance nerve graft to treat peripheral nerve discontinuities.
- Bill Holdings Inc. (BILL) gains 3% after activist investor Barington Capital Group has taken a stake in business payments firm.
- Costco falls (COST) 1.1% after the retailer reported total comparable sales for November that missed the average analyst estimate.
- Dollar General (DG) rises 4% after the company raised its full-year outlook, highlighting value-focused retailers are winning over consumers hunting for deals.
- Guidewire (GWRE) jumps 5% after the software company’s first-quarter results and second-quarter revenue forecast topped analysts’ expectations.
- Hormel (HRL) rises 6% after the protein producer’s 3Q adj. EPS forecast beat the company’s recently lowered guidance, as well as the Street consensus.
- MBX Biosciences (MBX) slips 3% after Goldman Sachs initiated coverage of the drug developer with a sell rating, citing risk to the firm’s data readout in the near term.
- Salesforce Inc. (CRM) is up 1.9% after the software company gave an outlook for revenue in the current period that topped analysts’ estimates, suggesting it is persuading customers to buy its AI tools.
- Snowflake (SNOW) falls 8% after the software company issued a forecast for operating margin in the current quarter that fell short of the average analyst estimate. Analysts noted a deceleration in product revenue growth.
- UiPath (PATH) rises 8% after the software company’s third-quarter results beat expectations. It also gave a forecast.
- UniQure (QURE) falls 13% after saying the FDA indicated that data from its Phase I/II studies of an investigational gene therapy for Huntington’s disease are unlikely to provide primary evidence to support a biologics license application submission.
- ZIM (ZIM) rises 3% after Globes reports that Hapag-Lloyd submitted a bid to purchase the shipping company, without saying where it got the information.
Fed rate-cut expectations have fueled a broad rebound after November’s slump, with investors turning to defensive and other sectors as worries over stretched tech valuations persist. The small-cap Russell 2000 index is now just shy of a record high, while the Nasdaq 100 remains about 2% below its peak.
“We’re expecting a broadening of the rally for sectors that have so far been lagging,” said Amelie Derambure, senior portfolio manager at Amundi SA in Paris. “The Russell is very sensitive to interest rates, so the figures reinforced the market’s idea that the Fed will be able to lower rates, in a non-recessionary context.”
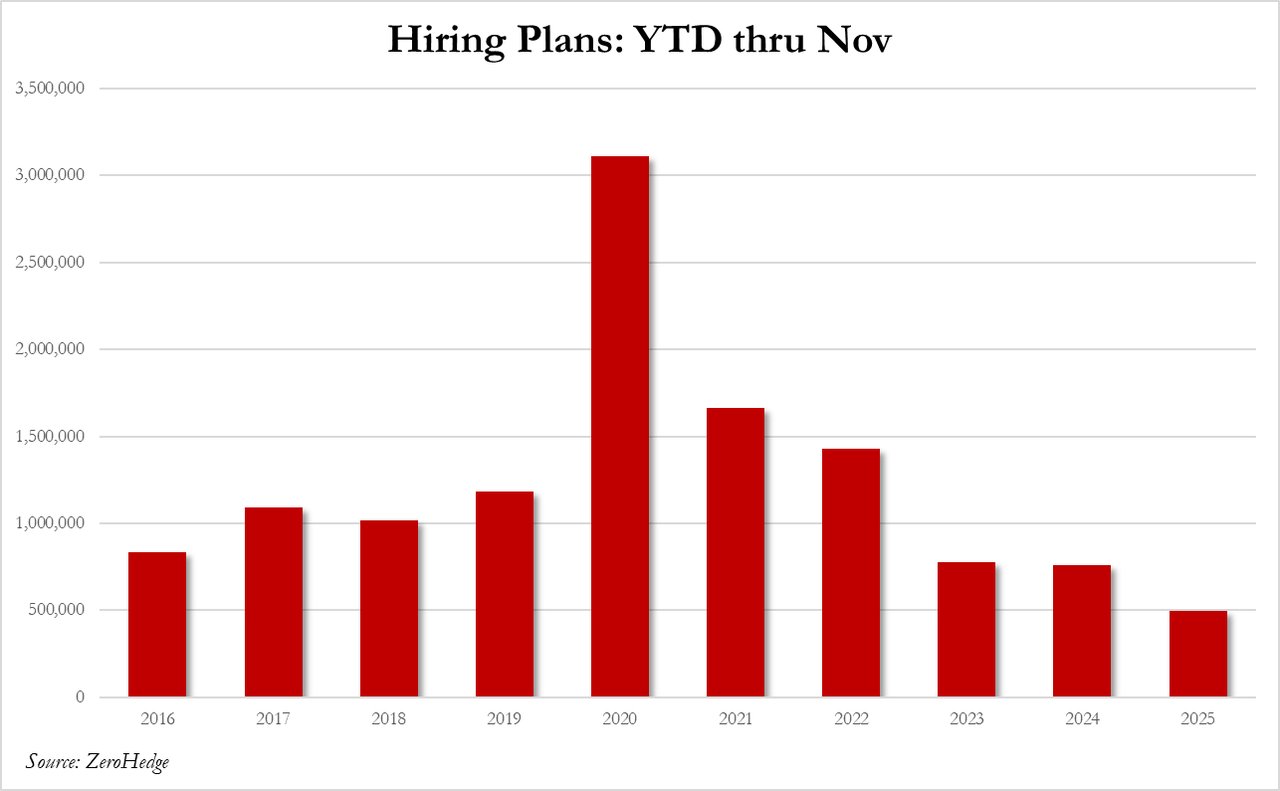
A report on corporate job-cut announcements from Challenger, Gray & Christmas Inc. added to evidence that the US labor market is softening. Announced layoffs fell last month after surging in October, but were still the highest for any November in three years, according to the outplacement firm. Meanwhile, YTD hiring plans are the lowest since 2010.
With official data still delayed, private indicators have increasingly pointed to employment coming under pressure from company belt-tightening and weaker spending. Worries about the jobs market and expectations that President Donald Trump will choose a Fed chair who shares his dovish stance have shifted market pricing toward as many as four rate cuts through 2026. Still, with the broader economy resilient, easier policy should continue to support stocks.
“Retail momentum stocks and crypto are still way below the recent peaks, though both have recovered from the recent lows,” wrote Mohit Kumar, chief economist and strategist for Europe at Jefferies. “We see sentiment remaining positive into year-end.”
Meanwhile, Goldman Sachs is looking past this month’s decision to what it calls a “foggy” Fed rate path in 2026. Risks to its terminal-rate range are skewed to the downside amid labor-market weakness, the bank wrote. They still expect two rate cuts next year. JPMorgan strategists expect the market to be boosted by higher equity demand next year. They project a supply-demand “improvement” of around $700 billion in 2026, which would be the strongest year since 2023.
Europe's Stoxx 600 is 0.3% higher with the DAX outperforming. Autos and industrial stocks are leading the way in Europe while utilities and healthcare dip. Automakers gain as Bank of America upgrades some stocks. Here are some of the biggest movers on Thursday:
- Mercedes, Renault gain as much as 4.4% and 4.8% respectively while holding company Porsche SE rises 5.7%, as Bank of America upgrades the stocks due to a more positive view on the European autos sector.
- Storytel gains as much as 6.5% after SEB initiated coverage of the Swedish audiobook and publishing house with a buy rating, saying the company has improved the quality of its subscriber base and its internal efficiency.
- Cosmo shares rise as much as 5.5%, adding to Wednesday’s 20% jump following positive late-stage trial results for the life science company’s experimental treatment for male hair loss.
- Balfour Beatty shares rise as much as 2.4% after the engineering and construction group said it expects to grow its order book by 20% in 2025 and confirmed more buybacks are on the way in 2026.
- Philips shares drop as much as 8.6% after Citi analysts noted tariff and China challenges for 2026.
- Trustpilot shares fall as much as 21% after Grizzly Research published a report on the consumer-review company.
Earlier in the session, Asian stocks rose for a third straight day, led by gains in Japan as regional tech shares tracked their US peers higher. The MSCI Asia Pacific Index advanced as much as 0.9%, with SoftBank Group and Keyence among the biggest contributors. Shares fluctuated in China and Hong Kong, while South Korean stocks slipped. India’s benchmark struggled to hold early gains even as the rupee strengthened against the dollar. Sentiment across the region is improving on rising expectations of a Federal Reserve rate cut this month after the latest US jobs data. Meanwhile, a slightly weaker yen is providing an extra lift to Japanese exporters. Semiconductor shares are showing signs of weakness, with South Korea’s tech-heavy stock index slipping more than 1% as foreign funds take profit. A Microsoft Corp. update is also weighing on sentiment, after a media report that the firm lowered expectations for business customers buying on the cloud unit’s marketplace for artificial intelligence models and agents.
In FX, the dollar gives up earlier gains, Aussie outperforming on bets the central bank may pivot back to rate hikes.
In rates, global bonds weakened, driven by rising yields in Japan. Sentiment shifted as some senior government officials signaled they wouldn’t oppose a Bank of Japan rate hike this month. Treasury yields are rising across the curve. German bonds falling on growing government uncertainty. Gilts are outperforming after very weak construction activity data sparks a small increase in BOE rate-cut bets.
In commodities, oil prices are higher, albeit with some volatility. Brent is trading around $63/barrel. Gold is recovering ground and now trading close to $4,200/oz. Bitcoin, meanwhile, held above $93,000. The dollar was little changed.
US economic calendar includes November Challenger jobs cuts (7:30am), weekly jobless claims (8:30am) and September factory orders (10am)
Market Snapshot
- S&P 500 mini and Nasdaq 100 mini little-changed
- Russell 2000 mini steady
- Stoxx Europe 600 +0.3%
- DAX +0.8%
- CAC 40 +0.4%
- 10-year Treasury yield +2 basis points at 4.08%
- VIX +0.1 points at 16.17
- Bloomberg Dollar Index little changed at 1212.82
- euro little changed at $1.1668
- WTI crude +0.4% at $59.21/barrel
Top Overnight News
- Donald Trump’s aides are considering having Scott Bessent also head the National Economic Council if Kevin Hassett becomes Fed chair, people familiar said. BBG
- Trump's administration ordered an enhanced vetting of H-1B visa applicants, with new H-1B visa screening based on any involvement in censorship or free speech, according to the State Department memo.
- Trump said he may work out another trade deal with Canada and Mexico. BBG
- Vladimir Putin said Russia didn’t agree with some points of the US peace proposal for Ukraine, Tass reported, citing his interview with a local media outlet. Earlier, Trump called the meeting between Steve Witkoff and Putin “reasonably good” but next steps remain unclear. BBG
- Emmanuel Macron met Xi Jinping in Beijing and urged China to boost investments in France, as both sides look to rebalance their economic ties. BBG
- Cambricon plans to more than triple its production of AI chips to half a million units in 2026, people familiar said. The Beijing-based company aims to rival Huawei in China and fill a void left by Nvidia’s forced exit. BBG
- Bank of Japan Governor Kazuo Ueda said on Thursday there was uncertainty on how far the central bank could raise interest rates due to the difficulty of estimating the country's neutral rate of interest. RTRS
- The Indian rupee will regain some lost ground against the U.S. dollar over the next three months, but a reversal in the currency's fortunes hinges upon India and the U.S. agreeing to a trade deal. RTRS
- Paramount more than doubled its breakup fee to $5 billion in its offer to acquire Warner Bros., signaling confidence it can clear regulatory hurdles. BBG
- Meta Platforms Inc. has been hit by a full-scale European Union antitrust investigation over how its AI features in WhatsApp may be harming competition, in the latest probe into Big Tech’s dominance on the continent. The bloc’s digital chief signaled she wants to conclude several ongoing investigations into tech giants this month including Elon Musk’s X. BBG
- For all the focus on ADP (historically very noisy), the Indeed Hiring Lab data actually picked back up in the last couple of weeks (need more data). Notable was the a re-acceleration in open jobs in construction (see below). What if AI adoption is slower or less transformative in the near term… the labor market re-accelerates… and inflation proves hotter in 2026? Not at all my base case but inversion an in important part of the process: Goldman
Trade/Tariffs
- US President Trump said they will either let the USMCA expire or maybe work out another deal with Mexico and Canada.
- US halted plans to sanction the Chinese spy agency to maintain the trade truce, and the Trump administration will also not enact any major new export controls against China, while the Trump admin is preparing to hold a high-level meeting to decide whether to provide licenses to allow NVIDIA (NVDA) to export the H200 to China, according to FT.
- Chinese Commerce Ministry, on rare earth export controls, said as long are export license applications are for civilian use, they will be approved.
- Chinese President Xi said in a meeting with French President Macron that China and France are far-sighted, responsible and independent major countries, while he added that China and France should uphold multilateralism and that China is willing to eliminate interferences and stick to equal dialogues with France. Xi also commented that both countries should support each other on core interests and agreed to expand practical cooperation, as well as consolidate cooperation on airspace and nuclear energy. Furthermore, he said both countries aim to expand two-way investment and that China will expand domestic demand in the 15th five-year plan and will also expand market access and opening-up.
- India's Trade Minister said exports of autos, electronic goods, textiles and machinery to Russia are expected to increase. India also aims to expand and diversify exports to Russia to address the trade imbalances. India has secured a USD 2bln submarine deal, Bloomberg reported during the visit of Russian President Putin.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mostly higher following the positive momentum from Wall St, where all major indices rose amid a weaker dollar and softer yield environment, but with some of the gains in the region capped amid a quiet calendar and lack of major fresh macro catalysts. ASX 200 edged higher in rangebound trade with strength in materials and resources offsetting the losses in the real estate and consumer sectors, while the mining industry was among the outperformers aside from the gold-related stocks. Nikkei 225 rallied above the 50k level as the tech-related momentum in Japan continued, despite higher yields and bets for a December BoJ rate hike. Hang Seng and Shanghai Comp were mixed amid weakness in auto names and after another liquidity drain by the PBoC, while PBoC Governor Pan noted in an Op-Ed that China must maintain prudent monetary policy and should avoid excessive policy adjustments.
Top Asian News
- PBoC Governor Pan said in a People's Daily op-ed that China must maintain prudent monetary policy and should avoid excessive policy adjustments, while he also suggested preventing overreach from leading to long-term side effects of policies.
BOJ
- BoJ is likely to raise interest rates in December, a decision Japan's government will likely tolerate, according to sources cited by Reuters.
- Key members of Japanese PM Takaichi's government would not try to prevent a BoJ hike in December, Bloomberg reports, citing sources.
- BoJ is carrying out an assessment of the level of neutral interest rate, according to Jiji.
- BoJ Governor Ueda reiterated that they can only estimate the neutral rate with a wide range thus far, while he added they cannot specify a terminal rate and are working on narrowing the estimate on the neutral interest rate, with the findings to be disclosed if successful. Furthermore, he said for now, they have to work with the current estimate set in a fairly wide range, and there is uncertainty on how far interest rates can eventually be raised.
European equities opened higher, reflecting positive APAC momentum, though morning news flow has been light. Markets expect Kevin Hassett to be named the next Fed Chair, with some concerns that he could be influenced by President Trump on rates. Meanwhile, Reuters and Bloomberg reported hawkish signals suggesting the BoJ is likely to raise rates in December with government approval. Sectors are mixed with a positive tilt: Autos, Industrial Goods & Services and Technology lead. At the bottom: Utilities, Basic Resources and Health Care.
Top European News
- BoE Decision Maker Panel Survey (Nov): Expectations for year-ahead CPI inflation remained unchanged at 3.4%; Expected year-ahead wage growth rose slightly, by 0.1ppt to 3.8% in the three months to November
FX
- DXY is trading near the lower end of its 98.798–99.029 intraday range, pressured by JPY strength after Reuters and Bloomberg reported the BoJ is likely to hike rates in December with government approval. Money markets were already pricing a 66% chance of a hike following Governor Ueda’s recent hawkish remarks. USD/JPY slipped from 155.54 to a 154.77 low, with next support at the 1 December trough of 154.66.
- AUD is firmer amid continued hawkish repricing of RBA expectations.
- G10 FX is otherwise mostly flat and taking its cue from the USD, with few fresh drivers. EUR and GBP were little moved by Construction PMI releases.
- PBoC set USD/CNY mid-point at 7.0733 vs exp. 7.0554 (Prev. 7.0754)
- Chinese State-owned banks reportedly bought USD on the onshore spot market this week in a bid to rein in CNY strength, according to Reuters sources.
- RBI to tolerate a weaker rupee as dollar inflows diminish, according to Reuters sources.
Fixed Income
- Fixed income benchmarks are lower following the hawkish BoJ reports, though the associated softening in risk sentiment has provided a modest haven bid as the morning has unfolded.
- JGBs underperformed, falling as much as 42 ticks to a new contract low of 134.08. The move pushed the 20yr yield to its highest since June 1999 and the 30yr yield to a record high, with selling driven by reports that boosted December BoJ hike odds to above 65%.
- The bearish tone extended into USTs and Bunds (now trading the Mar’25 contract), which hit lows of 112-27 and 128.46, down eight and 16 ticks respectively. European newsflow was limited; French and Spanish supply saw no major reaction, with Spain’s auction strong and France’s slightly softer versus prior.
- For USTs, focus beyond the BoJ remains on the Fed Chair narrative. The FT noted bond investors have expressed concern to the Treasury over Hassett