
Futures Rise As Bitcoin Extends Rally For 2nd Day, Copper Hits Record
US equity futures are higher again, led by small cap stocks. As of 8:20am ET, S&P futures are up 0.2% (they dropped following a very ugly ADP print at 8:15am), the same as Nasdaq 100 futs, with Mag 7 stocks mostly higher premarket led by NVDA (+0.4%) and AMZN (+0.3%); MRVL is up +10% post-earnings given the robust long-term guidance. Europe's Stoxx 600 is also higher led by tech and energy sectors. Bond yields are lower, the move accelerating after the ADP print; the USD is also lower. Commodities are mixed: Oil higher, while copper hit a fresh record high above $11,350/ton following the largest surge in orders since 2013. Bitcoin extended a tentative rebound on Wednesday, rising as high as $94,000, though sentiment remains fragile. On the news front, increment updates were relatively muted overnight except for MRVL’s positive earnings that trigger the rebound in global tech. The US economic calendar includes November ADP employment change (8:15am), September import/export price index (8:30am), September industrial production (9:15am), November final S&P Global US services PMI (9:45am) and November ISM services (10am).
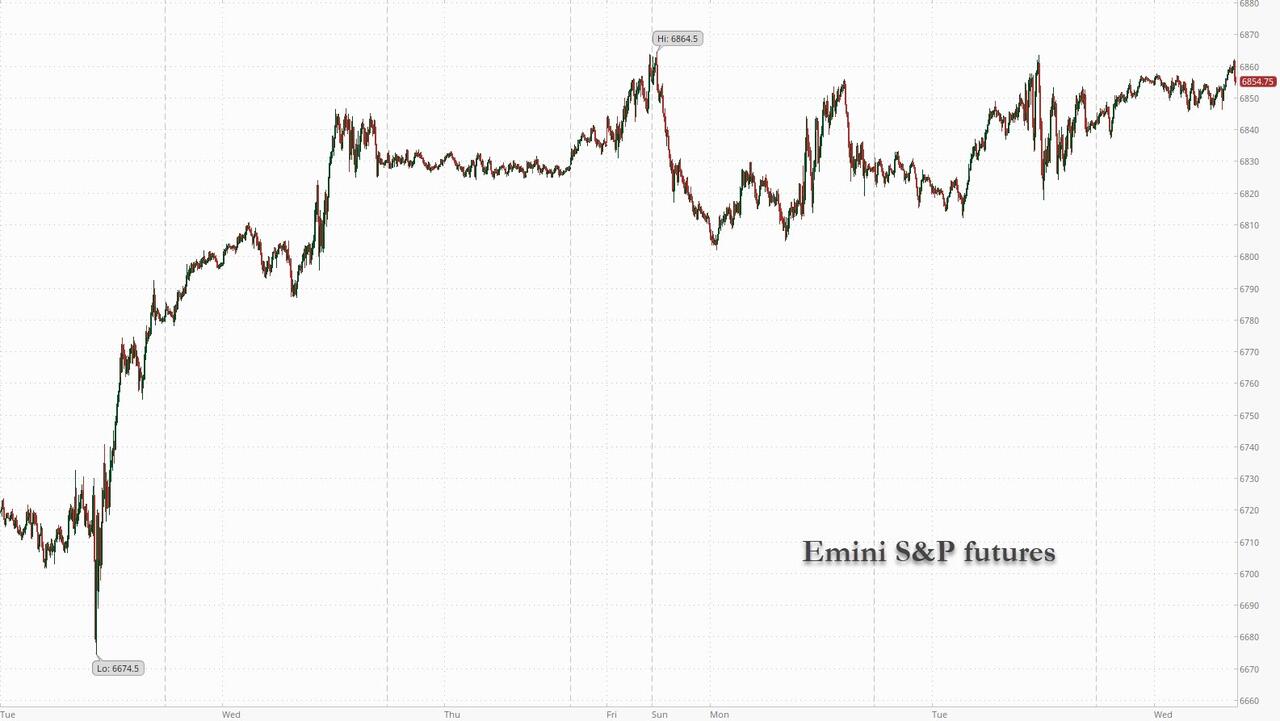
In premarket trading, Mag 7 stocks are mostly higher (Nvidia +0.8%, Amazon +0.4%, Alphabet +0.3%, Tesla +0.1%, Microsoft -0.1%, Apple +0.04%, Meta +0.06%)
- Acadia Health (ACHC) slumps 29% after the psychiatric-hospital chain cut its adjusted earnings per share guidance for the full year.
- American Eagle (AEO) surges 12% after the apparel retailer raised its comparable sales guidance for the full year and reported net revenue for the third quarter that topped the average analyst estimate.
- Astera Labs (ALAB) rises 7% as analysts note that Amazon’s AWS Trainium artificial intelligence chip is a positive for the semiconductor manufacturing company. Amazon’s cloud unit raced to get the latest version of its AI chip Trainium3 to market and unveiled Trainium4.
- GitLab (GTLB) falls 8% after the software company’s results and forecast were seen as underwhelming. Bloomberg Intelligence wrote that the report reinforces concerns about AI.
- Marvell Technology (MRVL) rises 9% after the chipmaker’s CEO assuaged investor concerns with positive trends at its custom chip-design unit. The company also announced plans to acquire startup Celestial AI for about $3.25 billion.
- Microchip (MCHP) is up 2% after the semiconductor device company forecast adjusted earnings per share for the third quarter that beat the average analyst estimate.
- Oracle (ORCL) gains 1.6% as Wells Fargo starts coverage of the tech giant with a recommendation of overweight, describing the firm as an “emerging leader in the AI super-cycle.”
- Okta (OKTA) is down 4% after the software company’s results and forecast were seen as underwhelming.
- Pharvaris (PHVS) jumps 18% after the drug developer said a late-stage trial of its investigative therapy for hereditary angioedema (HAE) — a rare genetic condition that causes severe swelling — met its main goal
- Pure Storage (PSTG) declines 14% after the computer hardware and storage company reported higher operational expenditure in the third quarter.
Stocks rose for a second day, but eased back after ADP reported that US companies shed payrolls in November by the most since early 2023, adding to concerns about a more pronounced weakening in the labor market. Private-sector payrolls decreased by 32,000, according to ADP Research data released Wednesday. Payrolls have now fallen four times in the last six months. The median estimate in a Bloomberg survey of economists called for a 10,000 gain.
The data may add some support for the December rate-cut case, although markets are already treating a cut as a sure thing. Trump said he plans to announce his selection to lead the Fed in early 2026 and teased chief economic adviser Kevin Hassett as his possible choice. Traders are piling into bets that a new chair will support Trump’s calls for lower rates.
As Fed policymakers gather next week, the debate among officials will largely center on the job market and whether rates should be reduced for a third straight time. While the latest government report showed a larger-than-expected rise in payrolls, the gain was concentrated in just a few industries. The unemployment rate ticked up to an almost four-year high, and there’s been a steady drumbeat of layoff news from companies.
“Right now, the data argues for additional Fed funds rate cuts. US labor demand is weak, consumer spending is showing early signs of cracking, and upside risks to inflation are fading,” said Elias Haddad at Brown Brothers Harriman.
Also due today are ISM services data for November, as well as delayed import price index and industrial production numbers for September.
Elsewhere, traders continue to weigh conflicting signals in the AI story. The AI story and how much further it can power the market, continues to be top of mind. Marvell shares are soaring after its prediction for data center revenue to grow 25%, with further fuel to bulls coming from AI-power darling Vistra, which was raised to investment grade by S&P.
At the same time, Oracle credit default swaps closed at the highest level since the financial crisis. And Sam Altman seems to be worried about competition — he was said to declare a ‘code red’ to speed up improvements to OpenAI’s ChatGPT.
The SEC is said to have issued a flurry of warning letters to nine providers of highly-leveraged ETF plans, effectively blocking the introduction of such products. CME is working to improve client communications after Friday’s outage that disrupted multiple financial markets. Crypto giant Binance appointed co-founder Yi He as co-CEO.
European stocks are broadly firmer with the Stoxx 600 index up 0.2%. The FTSE 100 is lagging, trading lower by 0.2% alongside a firmer pound and losses in index-heavyweight HSBC. Here are some of the biggest movers on Wednesday:
- Stellantis gains as much as 8.4% after UBS analyst Patrick Hummel raised his recommendation on the carmaker to buy from neutral and following a report that the White House will announce new fuel efficiency standards for automobiles.
- European semiconductor stocks with data‑center and 5G exposure advance after US peer Marvell Technology reassured investors that its custom chip-design unit is winning repeat orders, signaling continued growth as the company benefits from runaway spending on AI computing.
- European defense stocks rise on Wednesday morning. The Kremlin said President Vladimir Putin held “very useful” talks with US envoys Steve Witkoff and Jared Kushner, though the sides failed to reach agreement on a plan to end Russia’s war in Ukraine.
- Inditex rises as much as 8.9% after releasing third-quarter results that beat consensus estimates.
- Cosmo Pharmaceuticals shares soar as much as 24% after the company said two late-stage studies of its experimental treatment for male hair loss reached statistically significant endpoints.
- Tomra shares advance as much as 6.3% as Pareto Securities flagged that the Norwegian recycling equipment company’s upcoming fourth-quarter earnings due on Feb. 13 “could be the inflection point,” with current consensus overlooking margin effects from recent changes.
- Bloomsbury Publishing shares rise as much as 5.2% after the firm struck a new strategic collaboration with Google on AI-powered learning and core publishing infrastructure. Berenberg said this is another example of the benefits AI is having on the publisher.
- Hugo Boss slumps as much as 11% after the luxury branded-clothes retailer announced its strategy plan through 2028.
- Eutelsat shares slump as much as 9.6% after Softbank, the satellite firm’s fifth biggest shareholder, offered rights at a discount as it opts not to take up more shares in the French company.
- Spire Healthcare shares drop as much as 15% after the private UK hospital operator gave a forecast for 2026 adjusted Ebitda that RBC called a “substantial” profit warning.
- Trainline falls as much as 12% as the online train ticketing platform receives its only sell-equivalent rating following a JPMorgan downgrade to underweight from neutral.
Earlier in the session, Asian stocks traded in a narrow range as investors awaited key data that will provide clues on the global economic outlook. The MSCI Asia Pacific Index edged down 0.1%, weighed by Alibaba and Tencent. TSMC and some Japanese tech firms were among the biggest boosts for the gauge. Stocks advanced in South Korea and Taiwan, while benchmarks in Hong Kong and India declined. The MSCI Asia gauge has been trading sideways over the past week, though it is still on track to cap its best year since 2017. The outlook for the artificial intelligence trade that has contributed much to the region’s gains in 2025 got a fresh tailwind from Marvell’s upbeat projections. Tech investors also digested details of Amazon.com’s new chip and continued to be enthusiastic over Apple’s AI advances.
In FX, the pound sits near the top of the pile with an upward revision to final UK PMIs giving the currency an additional boost. The Bloomberg Dollar Spot Index is down 0.3%.
In rates, 10Y Treasuries are a touch firmer extending Tuesday’s advance and outperforming European bond markets with no real bias on the US curve. Yields are richer by 2bp-3bp, keeping curve spreads within a basis point of Tuesday’s closing levels. 10-year is near 4.06%, about 2bp richer on the day and outperforming bunds by 1.5bp. Gilts are marginally outperforming US and German peers. IG dollar bond issuance slate empty so far and expected to slow following a strong start to the week. Eight firms sold a combined $5.65 billion Tuesday — the second-straight session with that many borrowers — taking the weekly haul past dealers’ forecasts of around $20 billion. Focal points of US session include November ADP employment and services PMI gauges, along with anticipation of US government labor-market data releases that were held up by the shutdown and US President Trump’s announcement of Fed Chair Powell’s successor. In commodities,
In commodities, copper has hit a fresh record high above $11,350/ton following the largest surge in orders since 2013. Spot gold trades flat around $4,200/oz. WTI crude oil futures are up 1.4% as traders weigh continued talks between the US and Russia that have so far failed to end the war in Ukraine. Bitcoin extended a tentative rebound on Wednesday, rising as high as $94,000.
Today's US economic calendar includes November ADP employment change (8:15am), September import/export price index (8:30am), September industrial production (9:15am), November final S&P Global US services PMI (9:45am) and November ISM services (10am).
Market Snapshot
- S&P 500 mini +0.2%
- Nasdaq 100 mini +0.1%
- Russell 2000 mini +0.3%
- Stoxx Europe 600 +0.3%
- DAX +0.3%
- CAC 40 +0.3%
- 10-year Treasury yield -1 basis point at 4.08%
- VIX -0.1 points at 16.51
- Bloomberg Dollar Index -0.3% at 1214.12
- euro +0.3% at $1.1657
- WTI crude +1.5% at $59.54/barrel
Top Overnight News
- Trump posted that "Any and all Documents, Proclamations, Executive Orders, Memorandums, or Contracts, signed by Order of the now infamous and unauthorized “AUTOPEN,” within the Administration of Joseph R. Biden Jr., are hereby null, void, and of no further force or effect. Anyone receiving “Pardons,” “Commutations,” or any other Legal Document so signed, please be advised that said Document has been fully and completely terminated."
- Marathon Russia-U.S. Meeting Yields No Ukraine Peace Deal: WSJ
- Kremlin says Putin accepted some US proposals on Ukraine and is ready to continue talking: RTRS
- Republican Wins Closely Watched House Special Election in Tennessee: WSJ
- US paused all immigration applications filed by immigrants from 19 countries it restricted from travel to the US earlier this year: NYT.
- Trump’s Aides Cancel Fed Chair Interviews as President Homes In on Pick: WSJ
- Trump Says He Doesn’t Want Somali Immigrants in U.S. as ICE Plans Operation: WSJ
- US judge blocked the Trump admin from enforcing a law depriving Planned Parenthood of Medicaid funding in 22 states.
- Airbus Sees Setbacks and Boeing Rebounds as Script Quickly Flips: BBG
- The AI frenzy is driving a new global supply chain crisis: RTRS
- A Newly Confident China Is Jockeying for More Global Clout as Trump Pulls Back: WSJ
- HSBC Names Chairman After Yearlong Search: WSJ
- Harvard’s Big Wager on Bitcoin Came Right Before the Bust: WSJ
- Nvidia’s Fat Margins Are Google and AMD’s Opportunity: WSJ
- BofA Total Card Spending (w/e Nov 29th) +0.2% (prev. +2.4% avg. in October); highlights that the slowdown was broad based and higher core goods inflation meant real spending was ever weaker.
Trade/Tariffs
- US President Trump said they will give refunds out of the tariffs and believes they won't have income tax to pay in the near future.
- US President Trump thanked Chinese President Xi for soybean purchases. It was separately reported that at least six shipments of US soybeans for China are to load at Gulf Coast terminals through mid-December, while the first US sorghum cargo to China since March is also loading at the Gulf Coast terminal, and a second cargo is due next week.
- US President Trump posted that he had a very productive call with Brazilian President Lula and "Among the things discussed were Trade, how our Countries could work together to stop Organized Crime, Sanctions imposed on various Brazilian dignitaries, Tariffs, and various other items." Trump added he believes "it set the stage for very good dialogue and agreement long into the future… Much good will come out of this newly formed partnership!"
- EU is said to be pushing for 70% of critical goods to be made in Europe, according to FT.
- Annual negotiations between Chinese copper smelters and Antofagasta (ANTO LN) have not progressed, as Chinese smelters remain determined to avoid negative fees, via Bloomberg citing sources
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mixed, with the region only partially sustaining the positive momentum from Wall St, where tech and crypto rebounded. ASX 200 traded marginally higher but with gains limited as participants also reflected on disappointing Australian GDP data. Nikkei 225 rallied to back above the 50k level as it benefitted from tech-related momentum. Hang Seng and Shanghai Comp declined after the Chinese tech giants failed to join in the spoils seen in global peers and after the PBoC continued to drain liquidity through its daily open market operations, while participants also digested the latest Chinese RatingDog Services and Composite PMI data, which continued to show an expansion in activity, albeit at a slower-than-previous pace.
Top Asian News
- China was reported to unveil a plan to boost tourism and aviation sectors and will strengthen inbound tourism air routes, while it will continue to ease entry and travel for foreign tourists and will boost tourism through coordinated consumption policies.
- DigiTimes reports that memory spot prices surged in November, despite Samsung Electronics' (005930 KS) RDIMM release marginally easing shortages, as suppliers hiked contract prices significantly. "Some industry insiders reveal that after Samsung halted pricing quotes in October, it resumed DRAM chip quotations mid-November with average contract price increases of 30-40%." "Sources indicate US-based NAND giants raised prices repeatedly, with November quotes 100-150% above October." "Expectations point to even steeper hikes in the first quarter of 2026."
- "Samsung Electronics' (005930 KS) final HBM4 samples are scheduled to undergo 2.5D packaging and finished product testing starting this month," via zdnet citing sources
- China is reportedly likely to maintain the annual growth target of around 5% in 2026, via Reuters citing sources; some advisors cited proposed a 4.5-5.0% target
- India's Chief Economic Adviser says he's not losing sleep over the INR weakening
European bourses (STOXX 600 +0.4%) opened with modest gains, following on from a positive session on Wall St. in Tuesday's session. Price action this morning has been mixed, with a few indices trading rangebound whilst others have gradually edged higher. European sectors are split down the middle. Retail leads the pile (buoyed by Inditex +8.50% post-earnings), whilst Energy and Tech complete the top three. Sentiment for the latter has been boosted after positive results from Marvell, which gains in pre-market trade. To the downside resides Insurance, and Optimised Personal Care.
Top European News
- French Parliamentary debate on the increases to the General Social Contribution on capital income, part of the Social Security Financing Bill (PLFSS), will be discussed later this week after the revenue component, Politico reports.
- ECB's Lane says they have a clear orientation for monetary policy conduct. On inflation "…a sufficiently large and persistent deviation from the target requires a monetary policy response, regardless of its origin". "In summary, this discussion has emphasised that the appropriate monetary policy response to an inflation deviation from the target is context specific and requires a careful analysis of a broad set of considerations. Of course, the capacity to consider “looking through” some types of inflation deviations depends on a strong institutional commitment to delivering the symmetric inflation target over the medium term, underpinning firmly-anchored medium-term inflation expectations".
FX
- DXY is softer today and trades towards the lower end of a 98.99 to 99.30 range. G10s are mostly stronger vs the Dollar, albeit to varying degrees. For the USD specifically, all focus has been on Fed developments, and in particular, President Trump hinting that White House NEC Director Hassett as the “potential” next Fed Chair. Moreover, it was reported in the WSJ that Trump aides have cancelled a number of Fed Chair interviews, after the POTUS said he had made up his mind. JD Vance was reportedly scheduled to meet with more candidates today, though those were cancelled, with the WSJ sources suggesting that it was currently unclear if they would be rescheduled. Odds of a Hassett chair nomination currently reside around 86% vs 75% earlier this week, on Kalshi. Ahead focus turns to US ADP National Employment and then ISM Services.
- EUR firmer and trades at the upper end of a