
Futures Rebound As Bitcoin Halts Plunge
After Monday's dismal start to December, US equity futures are higher (if only for the time being), although lacking conviction with few major catalysts on deck today. As of 8:15am, S&P 500 futures are up 0.3% and Nasdaq 100 contracts add 0.4%. Pre-market, Mag 7 are mostly higher led by META (+0.6%) and AMZN (+0.4%). Bond yields are unchanged and the USD is flat. Commodities are mostly mixed: Oil is flat; base metals are all higher (aluminum +0.9%), while precious metals are lower. After the latest post-BOJ bloodbath, bitcoin has managed to hold a modest bid and was trading above $87,000. The US economic calendar is blank for scheduled data releases.
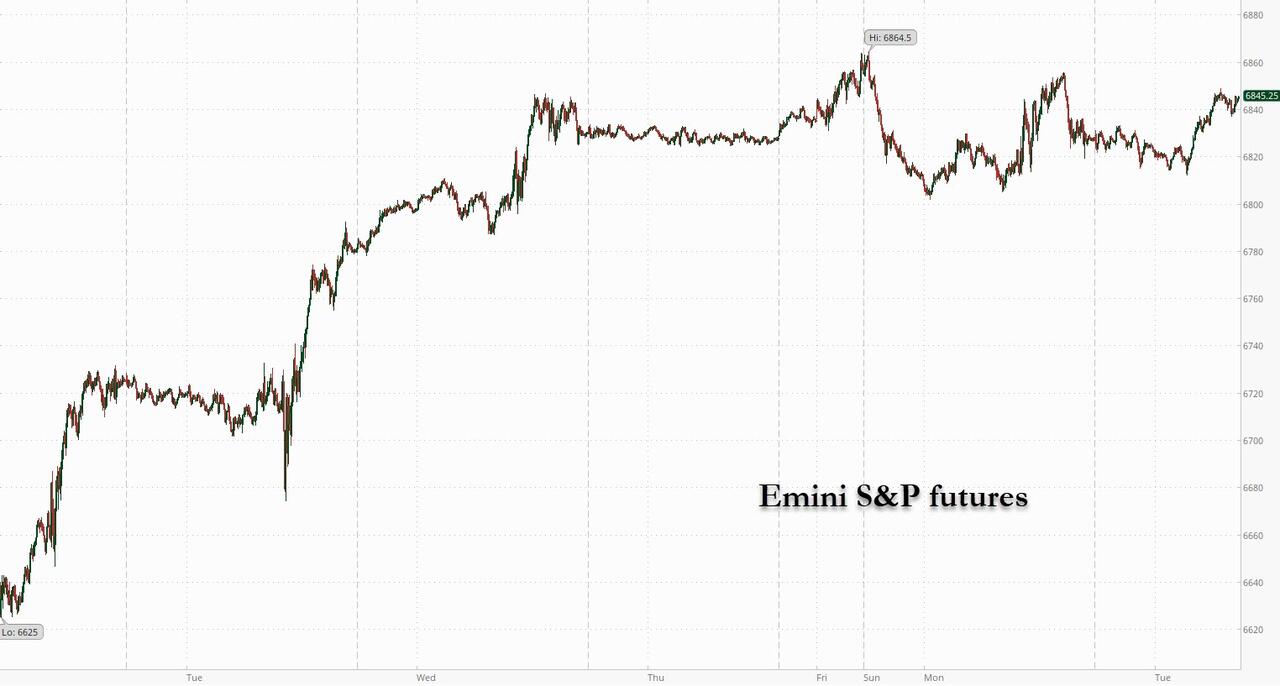
In premarket trading, Mag 7 stocks are mostly higher (Meta +0.6%, Alphabet +0.5%, Nvidia +0.8%, Amazon +0.7%, Tesla +0.3%, Microsoft +0.05%, Apple -0.1%).
- Cloudflare Inc. (NET) gains 2% after Barclays launched coverage on the infrastructure software company with an overweight rating and a $235 price target.
- Credo Technology (CRDO) rises 18% after the communications equipment company’s second-quarter results came in much stronger than expected. It also gave a strong forecast. Shares of competitor Astera Labs (ALAB) gain 5%.
- MongoDB (MDB) rallies 23% after the database software company reported stronger-than-expected results. It also raised its full-year forecast.
- Six Flags Entertainment (FUN) gains 3% after Truist Securities upgraded the theme park operator’s stock to buy from hold.
- Solaris Energy Infrastructure Inc. (SEI) rises 4% after the data center power generator was initiated at Morgan Stanley with a recommendation of overweight on power supply demand.
- Warner Bros. Discovery Inc. (WBD) inches 1.1% higher. The company was fielding a second round of bids on Monday, including a mostly cash offer from Netflix Inc., in an auction that could wrap up in the coming days or weeks, according to people familiar with the discussions.
In corporate news, The Information reported that Amazon is planning a new ultrafast grocery delivery offering in major US urban areas, sending shares of Instacart lower. Warner Bros. Discovery was said to be fielding a second round of bids on Monday, including a mostly cash offer from Netflix. The Commerce Department agreed to invest as much as $150 million in xLight, a chip technology startup tied to former Intel CEO Pat Gelsinger.
With the market stuck in a holding pattern until the next leg higher or lower, investors are awaiting eco data later this week, and the Fed is now in a blackout period. Black Friday and Cyber Monday offered some clues on the economy, with Bloomberg describing “anxious but still active” consumers, and Salesforce data showing Cyber Monday spending grew more slowly in the US than Europe for the first time as tariffs stung American shoppers.
“For long-only investors like we are, I’d say in the absence of any major catalyst, it’s very much wait-and-see until the Fed meeting, while keeping an eye on US jobs and inflation data,” said Karen Georges, a fund manager at Ecofi Investissements in Paris.
Much now depends on the Fed’s decision at next week’s meeting. Disappointment would pose a risk for equities, though confidence in a cut is virtually certain, with market odds of a cut at 100% following softer labor and inflation data and a run of dovish comments from officials.
“Dips continue to present attractive buying opportunities,” wrote Michael Brown, senior research strategist at Pepperstone. “The narrative behind that bull case remains an attractive one, with earnings growth solid, the underlying economy resilient, a calmer tone on trade continuing to prevail, and the monetary backdrop growing looser.”
Bitcoin is steady today after a more than 5% plunge on Monday which saw almost $1 billion of leveraged crypto positions liquidated. Crypto retail investors who piled into exchange-traded funds tracking Strategy’s volatile stock have paid a heavy price. Both MSTX and MSTU – which offer double the daily return – have dropped more than 80% this year, among the 10 worst-performing funds in the entire US ETF market.
While bitcoin longs were hammered again, so were stock short sellers: they were down $80 billion in mark-to-market losses in the final week of November, wiping out the bulk of what had been nearly $95 billion in month-to-date profits prior to last week, per data compiled by S3 Partners. “Being short here requires high confidence in a much weaker economic backdrop or a significant change in the outlook for AI capex,” said Dennis Debusschere, co-founder and chief market strategist at 22V Research.
Ahead of next week’s Fed decision, Barclays strategists noted that S&P 500 implied moves ahead of FOMC meetings have declined since early 2023, with realized moves hovering near zero recently. It’s a trend that underscores the fading influence of monetary policy, they wrote.
After hitting a record high just shy of $60, silver pulled back modestly with a technical gauge showing that a six-day rally had pushed the metal into overbought territory. Copper also retreated amid signs that softer Chinese demand heading into winter might help to ease a looming global supply crunch.
Elsewhere, Bloomberg found that among the 14 largest markets, the US currently ranks 5th from last in local-currency terms and 4th from last in dollar terms this year. That raises questions about whether the AI theme will lead it to victory or whether volatility tied to nascent tech exposure is doing more harm than good.
European stocks and US equity futures hold modest gains; the Stoxx 600 rises 0.2%, led by gains in banks, utilities and construction. Bayer soars after the Trump administration urged the Supreme Court to take up the company’s appeal of the Roundup case. Here are some of the biggest movers on Tuesday:
- Bayer shares surge as much as 15% after the US solicitor general urged the high court to consider the German company’s appeal targeting thousands of lawsuits blaming its Roundup weedkiller for causing cancer.
- Bilfinger shares rise as much as 6% after the German company said it aims to achieve an advanced average revenue growth of 8% to 10% annually, elevate its Ebita margin to 8% to 9%, and ensure a cash conversion rate of at least 90% until 2030.
- Victrex shares jump as much as 11% after JPMorgan said the thermoplastic maker cleared a low bar by beating expectations in the second half. Jefferies noted that a feared dividend cut hasn’t materialized.
- Biotalys shares rise as much as 8.8% after the Belgian agricultural technology company received regulatory approval from the US Environmental Protection Agency for its first biofungicide, called Evoca.
- Compagnie des Alpes rises as much as 6.9% following 2025 results from the French ski resort and theme park operator, which CIC Market Solutions describes as “excellent.”
- Swissquote shares tumble as much as 8.6% after one of its investors offered shares at a discount to the last closing price. Shares fell below the offer price before paring losses.
- Scandic Hotels drops as much as 8.8% as Morgan Stanley downgrades to underweight from equal-weight, saying the country’s acquisition of Dalata’s hotel operation may not be as profitable as previously expected.
- Foresight Group shares decline as much as 8.2% after the UK infrastructure and private equity investment management services company’s interim results, with Peel Hunt noting impact from margin compression.
- Pantheon Resources shares drop as much as 28% after the company’s update on work at the Dubhe-1 well. Canaccord Genuity said markets are still waiting for representative flow rates and that the cost of the work has come in higher than previously forecast.
Earlier in the session, Asian stocks gained, snapping a two-day decline, helped by a rally in tech-heavy markets of South Korea and Taiwan. The MSCI Asia Pacific Index rose as much as 0.5%, before paring gains. TSMC, Samsung Electronics and SK Hynix were among the biggest boosts to the gauge’s climb. Shares eked out small gains in Japan as banks extended advances on speculation of a Bank of Japan interest-rate hike this month. Growing expectations of an interest rate cut in the US is aiding risk-on in the region. A stabilization in bitcoin also helped sentiment after a selloff in cryptocurrencies led declines in global risk assets on Monday. Shares drop in India, as the rupee hit a record low. Concerns over the lack of a trade deal with the US is weighing on the currency. Benchmarks in China also traded lower.
In FX, the yen is the weakest of the G-10 currencies, falling 0.4% against the dollar and pushing USD/JPY above 156. The euro loses a few pips with little reaction to a surprise uptick in euro-area CPI. The pound is down 0.2%.
In rates, treasury yields are higher, within two basis points of Monday’s close with 10-year trading around 4.11%. Bund and gilts are little changed. In Asia, JGBs were supported after Tuesday’s 10-year auction drew solid demand. The corporate issuance slate is expected to grow following a heavy day on Monday. The IG dollar bond issuance slate is empty so far. Tuesday is expected to bring more US investment-grade bond issuance after around $16 billion of new deals on Monday, led by Merck’s acquisition-related $8 billion eight-part offering.
In commodities, spot gold falls $45 and back below $4,200/oz. US crude futures are treading water at $59.30 a abrrel.
The US economic calendar is blank for scheduled data releases. Fed members are in external communications blackout ahead of the Dec. 10 policy announcement
Market Snapshot
- S&P 500 mini +0.2%
- Nasdaq 100 mini +0.3%
- Russell 2000 mini +0.5%
- Stoxx Europe 600 +0.2%
- DAX +0.5%
- CAC 40 +0.2%
- 10-year Treasury yield unchanged at 4.09%
- VIX -0.4 points at 16.85
- Bloomberg Dollar Index little changed at 1219.09
- euro little changed at $1.1604
- WTI crude little changed at $59.34/barrel
Top Overnight News
- Trump's schedule noted he will host a Cabinet meeting on Tuesday at 11:30am and will make an announcement at 2:00pm. Some expect he could announce Kevin Hassett as next Fed Chair (Hassett's odds are up to 79% on Polymarket).
- Senators have about a week before they’re set to vote on soon-to-expire Affordable Care Act subsidies. Most of them already believe the chances for a bipartisan breakthrough by then are roughly zero. Politico
- US envoy Steve Witkoff is set to meet Vladimir Putin to discuss a Ukraine peace plan as Russia claimed its forces seized Pokrovsk on the Donetsk frontline. A fourth Russia-connected tanker in less than a week was attacked today. BBG
- Officially, the search for a new Federal Reserve chair is still under way. A handful of finalists are scheduled to sit down for interviews beginning this week with Vice President JD Vance and senior White House staff. Unofficially, the process seems to be all but over, with President Trump appearing to favor longtime adviser Kevin Hassett. If Hassett does end up the nominee, it will be because he met Trump’s two key criteria: loyalty, and credibility with the markets. WSJ
- OpenAI Chief Executive Sam Altman told employees Monday that the company was declaring a “code red” effort to improve the quality of ChatGPT and delaying other products as a result. OpenAI plans to launch a new reasoning model next week that the company claims outperforms Gemini 3. WSJ
- The world economy is weathering Trump’s trade tariffs better than expected, the OECD said. It raised its US and euro-area growth forecasts. Still, it continues to predict global growth will slow to 2.9% in 2026, from 3.2% in 2025. BBG
- China is expected to ramp up US soybean purchases this month to meet a pledge to buy at least 12 million tons by year-end, led by state firms like Cofco, traders said. So far, only about 3 million have been booked. BBG
- Strong demand for Japanese government bonds helped to steady Asian markets on Tuesday, a day after hawkish comments from the central bank governor sparked a global selloff. FT
- Europe’s headline CPI for Nov ran a bit warmer than anticipated at +2.2% (vs. the Street +2.1% and up from +2.1% in Oct) while the core number was inline at +2.4% (and steady vs. Oct). BBG
- Members of the House of Representatives are quitting Congress at a record rate, with Republican retirements and resignations outpacing Democrats by a nearly 2-to-1 ratio in the first 11 months of the year. In previous cycles, the party with more departures tends to lose seats — if not the majority. Axios
- Apple plans not to follow the order by the Indian government to preload phones with a state-run cyber safety app, according to Reuters, citing sources; Co. to voice its concerns around privacy and security following new app order
Trade/Tariffs
- Chinese rare-earth magnet companies are reportedly finding workarounds to their government’s export restrictions, as they seek to keep sales flowing to Western buyers, according to WSJ.
- China reportedly issues first rare earth magnet general export licence after the Trump-Xi meeting, according to Reuters sources
- Exxon (XOM) is reportedly in talks with Iraq over purchasing Lukoil's stake in the West Qurna 2 oilfield, via Reuters citing sources.
- Russia's Kremlin Spokesperson Peskov says that Russia continues to be an important supplier of energy to India on a competitive basis. Looking at possibilities to increase imports from India. A decrease in oil trade volumes can be decreased for a brief period of time.
A more detailed look at global markets courtesy of Newsqsuawk
APAC stocks were predominantly in the green as the region shrugged off the weak lead from Wall Street, but with the upside capped amid quiet macro catalysts and in the absence of any tier-1 data. ASX 200 eked mild gains with the help of outperformance in energy, resources and mining, but with gains limited by underperformance in tech and utilities, while data was uninspiring with a larger-than-expected contraction in building approvals. Nikkei 225 nursed some of the prior day's losses but with the rebound contained amid risks of a BoJ December hike. Hang Seng and Shanghai Comp mostly traded mixed as participants reflected on a slew of monthly auto sales updates, while the mainland lagged after the PBoC's open market operations resulted in a net daily drain of CNY 146bln.
Top Asian News
- RBNZ Governor Breman said she will discuss with the MPC the possibility of being more transparent with how members vote, while she added that the mandate is very clear that we should focus on keeping inflation low and stable. Breman said that they aim to support a healthy, strong and growing economy, but keep inflation low and stable. It was separately reported that the RBNZ is to begin weekly open-market operations from December 4th and will update changes to the format in Q1 2026.
- Samsung Electronics (005930 KS) has completed development of its 6th-gen HBM4 and is entering full-scale mass production, via AJUNews.
European bourses (STOXX 600 +0.2%) started the session flat/incrementally firmer before then catching a bid as the morning progressed; no clear driver for the upside, but a move which has sustained as indices reside near peaks. European sectors hold a slight positive bias. Banks take the top spot, with gains broad-based across the UK and Europe, but traders may also be digesting the latest update via the BoE, where it lowered capital requirements for UK banks as they pass stress tests. Media is found at the foot of the pile, joined closely by Travel & Leisure.
Top European News
- Confederation of British Industry said Britain's private sector expects output to decline during the next three months in the gloomiest outlook since May as cautious consumer spending and cost pressures continue to weigh on businesses.
- BoE Financial Policy Committee Record: System-wide level of Tier 1 capital requirements is now around 13% of risk-weighted assets, 1ppt lower than its previous benchmark of around 14%. CCyB maintained at 2%. "The Committee has also identified areas for further work, including on buffer usability, the implementation of the leverage ratio in the UK, and initiatives by the Bank to respond to feedback on interactions, proportionality, and complexity. Committee supports the Bank’s plans for a private markets system-wide exploratory scenario (SWES)".
- OECD sees global growth of 3.2% in 2025 (maintained from prev. forecast), 2.9% in 2026 (maintained), 3.1% in 2027 (new forecast).
- UK OBR's Miles says it was not misleading for Chancellor Reeves to have said that the situation with public finances was very challenging.
- BoE Governor Bailey says he expects banks to support the economy through lending following recent capital changes.
FX
- DXY and most G10 FX are uneventful in relatively quiet trade, with a similar lack of macro drivers seen during APAC hours. Specifically, DXY resides in a narrow 99.38-99.52 parameter, with ING calling for a lower dollar this week – "we expect that the remainder of the week will validate the market’s dovish pricing for next week’s Fed meeting". As it stands, the index trades at the upper end of the mentioned ranges, with recent strength thanks to some pressure seen in the GBP.
- EUR traded flat ahead of the EZ HICP metrics, and then was little moved on the release itself. Headline printed a touch above expected at 2.20% (exp. 2.10%) whilst the Services figure also ticked higher from the prior month. Overall, given the figures were near enough in line with expectations, there was little follow-through into the single-currency and held within a 1.1604 to 1.1616 range, before then touching 1.1600 as the USD picked up a touch.
- USD/JPY outperforms amid a pick-up in risk sentiment and after the pair's volatile Monday session, which saw a slump to 154.66 lows before bouncing back up and clear of 155.50 and then 156.00, with the pair eyeing yesterday's 156.15 peak as the near-term resistance level, and thereafter Black Friday's 156.58 high.
- GBP traded flat against the USD, before then moving lower in recent trade. Nothing behind the latest bout of pressure, but it does come after Cable breached 1.3200 to the downside, and then continued to tumble to make a fresh trough at 1.3180 (though it is a moving target).
- AUD outperforms after ANZ removed its call for an RBA cut in H1-2026, now sees the RBA on an "extended pause" through 2026. As a reminder, CBA and NAB also expect the RBA to be on hold for an extended period of time/foreseeable future. Westpac continues to expect two 2026 cuts, touting May and August for those. AUD/NZD marginally eclipsed 1.1450, from a 1.