
Stocks Extend Rally Into 7th Month As AI Bubble Rally Just Won't Stop
US equity futures are signaling a solid start to November, led by Tech with small caps flat, as traders gauge the durability of a seven-month global equity rally fueled recently by strong tech earnings and easing US–China trade tensions. S&P 500 futures were up 0.2% while Nasdaq 100 futs rose 0.6% as of 8:00 am ET. Pre-market, Mag7 are all higher with Semis also bid; Cyclicals poised to lead Defensives with both higher. European and Asian equities also rose. Global bonds softened, with the 10-year US Treasury yield at 4.11%. Commodities are mixed with Ags leading, Metals weaker, and Energy mostly lower ex-natgas. Oil fluctuated after OPEC+ signaled that it’ll pause output increases next quarter ahead of expected demand declines / supply glut. China suspended curbs on rare earths and suspends chips investigation. Gold first dropped but then rebounded back over $4k after China imposed a 7% value-added tax on gold for jewellery and industrial use. Today SCOTUS will hear IEEPA tariff challenges with JPM noting that the market expects those tariffs to be struck down and later replaced by sectoral tariffs and could trigger a near-term squeeze/broadening subject to moves in the bond market. We also get US manufacturing PMI (9:45am) and October ISM manufacturing (10am); US government data continue to be postponed by shutdown that began Oct. 1. Fed speaker slate includes Daly (12pm) and Cook (2pm). Earnings from Palantir and Diamondback Energy follow later in the day.
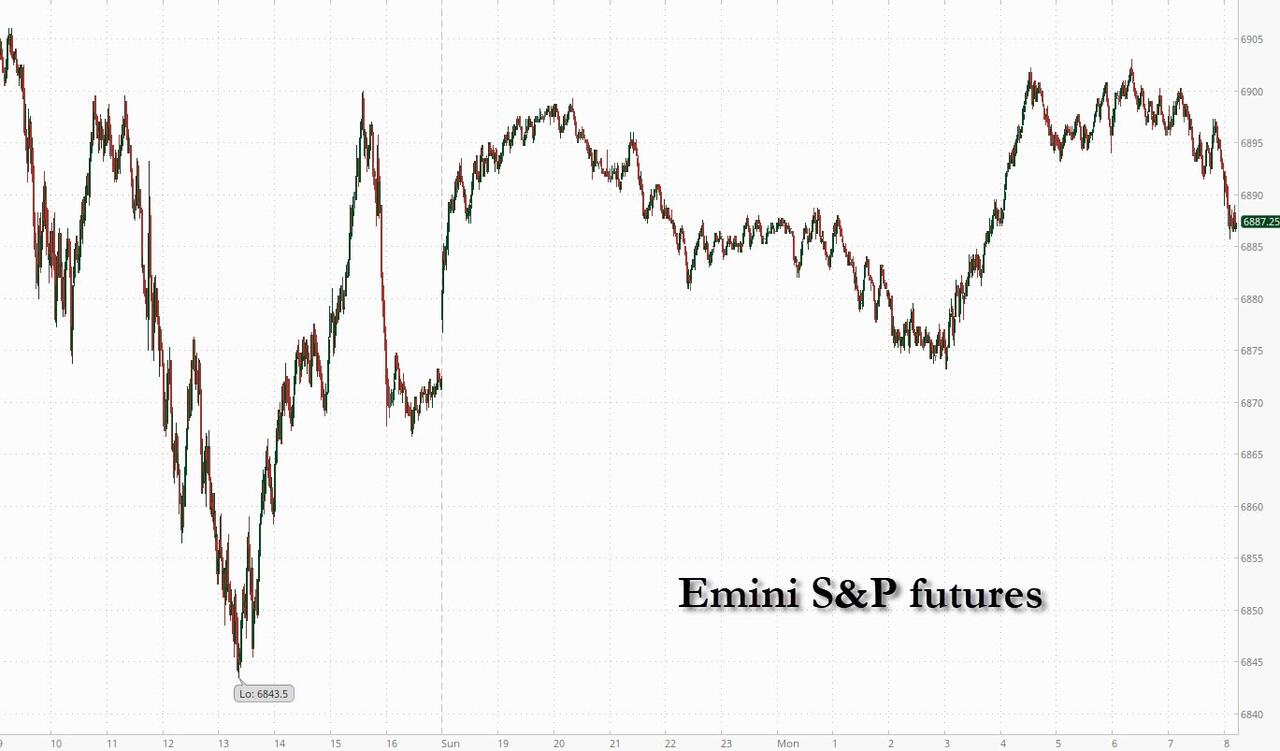
In premarket trading, Mag 7 stocks are all higher (Nvidia +1.8%, Meta +0.9%, Alphabet +0.5%, Amazon +0.2%, Tesla +0.5%, Apple +0.01%, Microsoft +0.4%).
- Alvotech (ALVO) plunges 23% after the drugmaker said the FDA rejected its biologics application for a biosimilar candidate to Johnson & Johnson’s Simponi, and cut its 2025 outlook as a result.
- Cipher Mining (CIFR) rises 21% after signing a $5.5 billion, 15-year lease agreement with Amazon to provide turnkey space and power for AI workloads.
- Eaton (ETN) slips 1% after agreeing to buy the Boyd Thermal business of Boyd Corp. from Goldman Sachs for $9.5 billion.
- IREN Ltd. (IREN) soars 22% after Microsoft Corp. signed an approximately $9.7 billion deal to purchase AI cloud capacity from the Australian company, becoming its largest customer.
- Kenvue (KVUE) jumps 19% after Kimberly-Clark agreed to buy the struggling Tylenol maker in a deal worth roughly $40 billion. Kimberly-Clark (KMB) shares slump 15%.
- Liquidia (LQDA) rises 11% after the drugmaker reported revenue for the third quarter that exceeded the average analyst estimate. The company also reported loss per share for the quarter that was lower than expectations.
- New Gold Inc. (NGD) climbs 10% after agreeing to be acquired by Coeur Mining Inc. for about $7 billion in an all-stock deal.
- SM Energy Co. (SM) and Civitas Resources Inc. (CIVI) agreed to combine in an all-stock transaction, the latest move to consolidate the US shale industry. Shares of SM Energy are up about 1%, while the stock of Civitas Resources (CIVI) rises 2%.
- Vertiv (VRT) rises 1.8% after entering into an agreement to buy Purge Rite Intermediate from Milton Street Capital LLC for ~$1b in cash at closing plus the potential additional consideration of up to $250 million in cash based on achieving certain 2026 performance metrics.
In corporate news, Pfizer sued Metsera and Novo Nordisk to block Novo’s rival bid for the obesity startup. Alphabet is expected to raise a total of at least €3 billion ($3.5 billion) in six euro-denominated bonds, to help fund AI expansion. BP agreed to divest stakes in US shale assets to Sixth Street for $1.5 billion as it seeks to shore up its balance sheet and win back investor confidence.
The six-month bull run in US stocks is set to continue as markets brush aside concerns over stretched valuations, with earnings beating expectations and big tech fueling optimism around AI. Investors are gearing up for earnings from Palantir and a slate of private economic reports for fresh direction on the path for interest rates. Palantir, one of the year’s biggest beneficiaries of the artificial-intelligence boom with a 165% gain, was poised rally further ahead of results due after the close.
Investors are set to again rely on private data this week given the government shutdown, which includes the ISM manufacturing index on Monday and ADP employment figures on Wednesday. While there is a risk that a flood of economic data could hit once the shutdown is over and reignite volatility, the subdued VIX gauge has seen call buying at a high pace. And speaking of the shutdown, it is on track to become the longest in history.
"Earnings growth is there, the momentum is there and on a macro level — although it’s still very volatile — things are moving in the right direction,” said Andrea Gabellone, head of global equities at KBC Global Services. “I don’t see any reason for the rally not to consolidate and even go higher.”
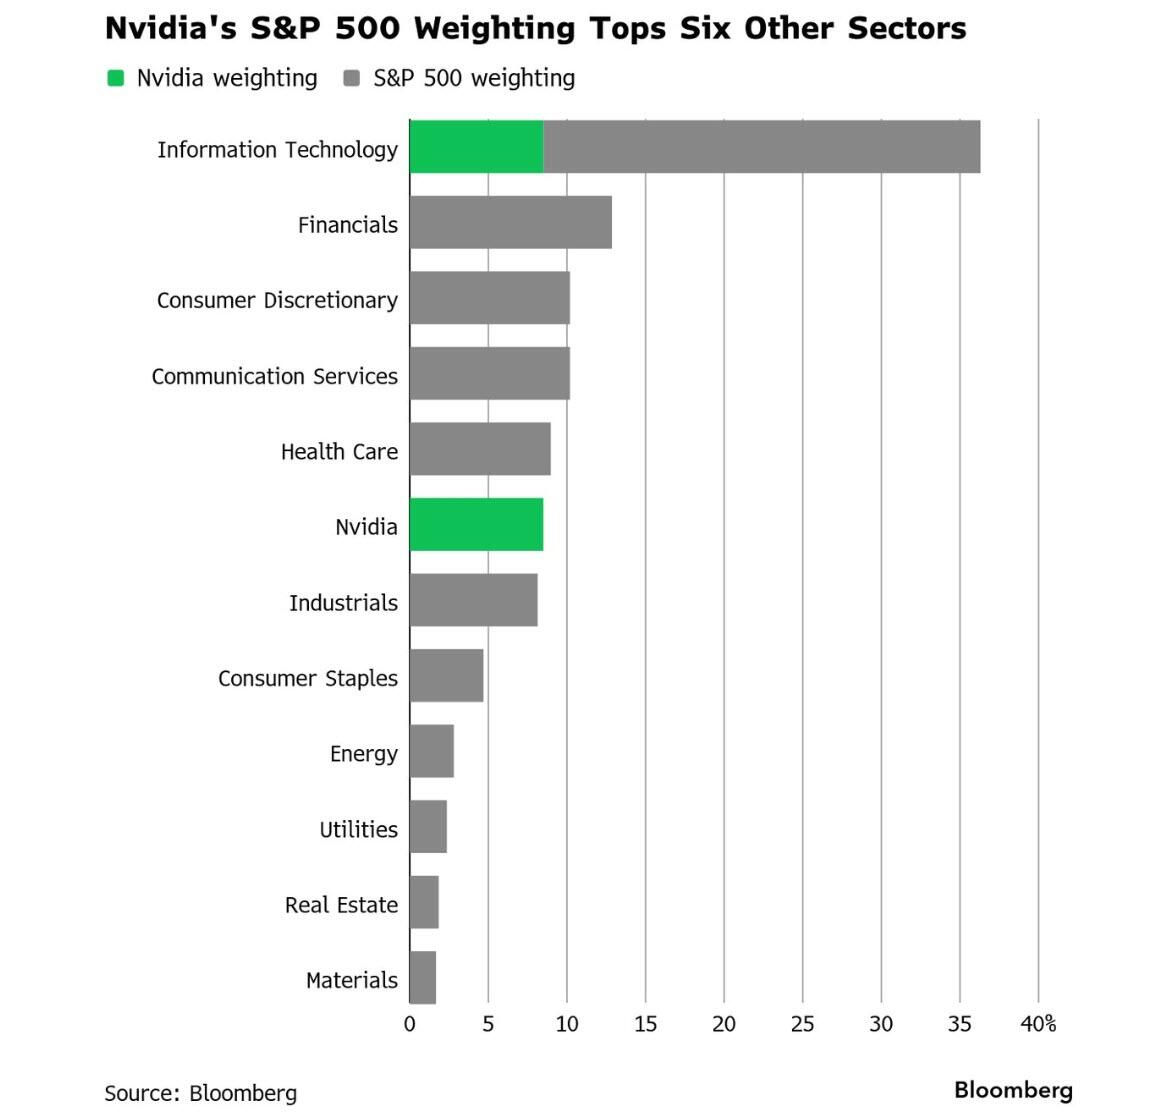
With earnings in from six of the Mag-7, quarterly profit growth is tracking at ~27% for the group, compared with 15% expansion anticipated before the reporting season started, according to data compiled by Bloomberg Intelligence. Nvidia is now larger than six of the 11 sectors in the S&P 500 Index and all but five of the world’s stock markets.
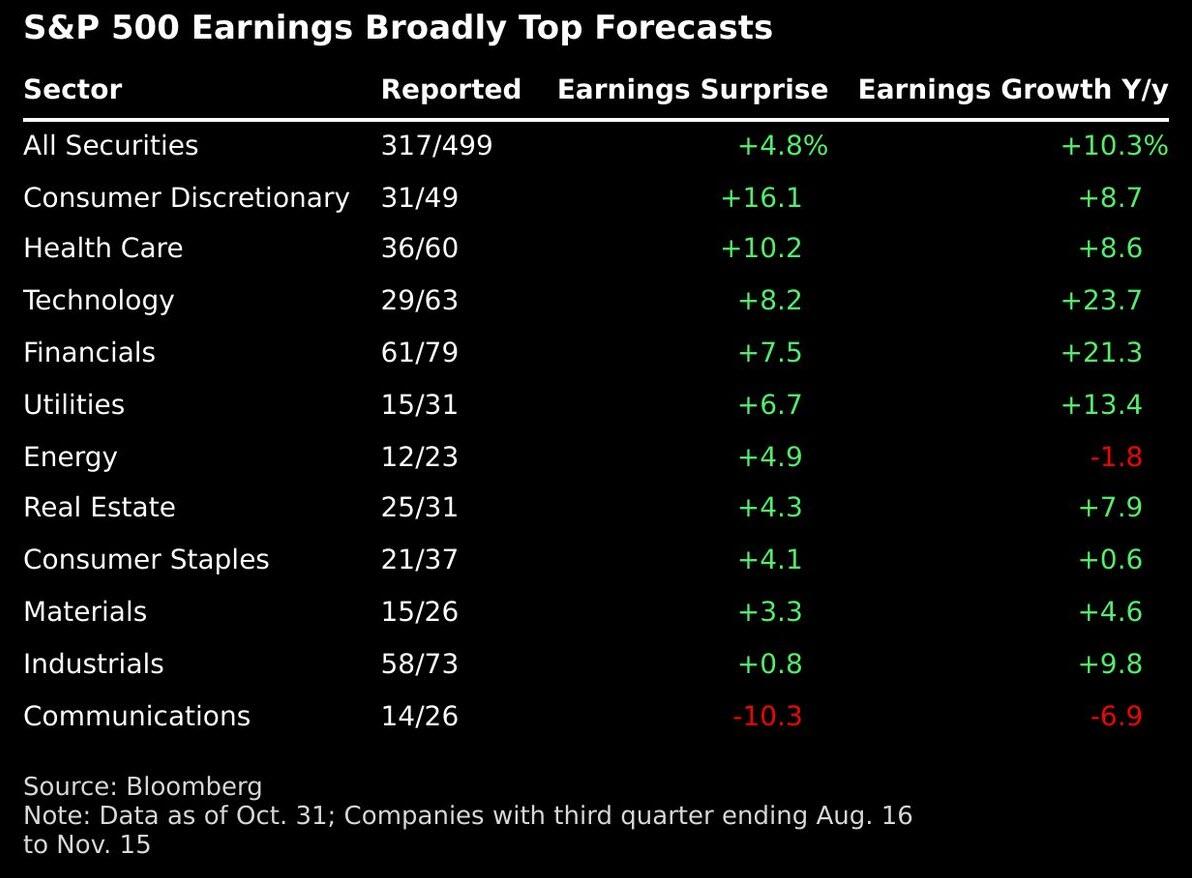
Out of the 318 S&P 500 companies that have reported so far in the earnings season, 83% have managed to beat analyst forecasts, while 13% have missed. The S&P 500 is on pace for 13% earnings growth, up from 7.2% expected at the beginning of October. US earnings are surging across the board with the median stock in the Russell 3000 tracking its fastest growth since 3Q21, Morgan Stanley said, supporting a view that a new cycle and bull market began in April. Goldman Sachs’ David Kostin sees earnings beats as unprecedented except the Covid reopening in 25 years of data.
As reported over the weekend, Berkshire Hathaway’s cash pile soared to a record $381.7 billion in the third quarter, while the firm declined to buy back shares for a fifth straight quarter. Operating earnings surged 34% as its insurance underwriting profit more than tripled.
In trade, China ended a gold tax break, in a setback for consumers in one of the world’s top bullion markets. The US is expected to suspend port fees for a year on China-linked vessels starting next week. China is said to seek buying US wheat for the first time in a year.
In Europe, the Stoxx 600 is up 0.4%, with automakers leading gains after it was announced China would ease its chip export ban. Energy shares advance alongside oil prices as OPEC+ is set to pause its output increases in the first quarter of next year. Autos gain after it was announced China would ease its chip export ban. Here are some of the biggest movers on Monday:
- GTT advances as much as 6.2%, to a new record high, following an upgrade to its guidance after the market close on Friday.
- European energy companies are outperforming this morning as oil prices advanced after OPEC+ signaled that it’ll pause output increases next quarter, following a modest hike for next month.
- A2A gains as much as 6.4% as Morgan Stanley upgrades to overweight, saying the firm is an “under-the-radar” potential beneficiary of any Milan-region data center build-out.
- European autos shares rise after it was announced China would ease its chip export ban in a decision that should “alleviate short-term supply risk for OEMs and their suppliers,” say Oddo BHF analysts.
- MFE-MediaForEurope’s Class A shares gain as much as 5.7% as JPMorgan initiates coverage with an overweight rating.
- BFF Bank surges as much as 11%, the most since May, after the Italian firm said the Bank of Italy has lifted the ban on the distribution of profits, which analysts at Deutsche Bank say is fueling a relief rally in the shares.
- Paradox Interactive gains as much as 12% after video-game critics published their reviews of the Swedish studio’s key 2H 2025 release, strategy game Europa Universalis V.
- Davide Campari-Milano shares fall as much as 6%. Italian prosecutors have ordered the seizure of around €1.3 billion in shares from the holding company that controls Campari as part of an alleged tax-fraud probe, according to a statement late Friday.
- Ryanair shares fall as much as 3.6%, taking a breather after ongoing strength in share performance. Europe’s largest budget airline reported post-tax profit in the second quarter that topped estimates, driven by in-line fare growth and strong cost control.
- FLSmidth falls as much as 4.6% after Nordea cut its recommendation on the Danish industrial equipment firm to hold from buy.
Asian stocks rose, lifted by gains in South Korea’s chipmakers after a slew of technology partnerships bolstered sentiment. Equities in Hong Kong extended their advances in afternoon trading. The MSCI Asia Pacific excluding Japan Index climbed as much as 0.9%, rebounding after two sessions of losses. Gauges in South Korea were the biggest gainers in the region, with the benchmark Kospi hitting a fresh record high. Shares on mainland China reversed early losses to close higher, while those in the Philippines fell. A series of partnerships between Nvidia and some of South Korea’s biggest companies has reinforced optimism in the country’s equities, supported by an improving relationship with the US. Sentiment in Asia also got a boost following several trade deals struck during US President Donald Trump’s tour of the region last week.
In rates, treasuries are marginally cheaper across the curve, following similar price action in German bonds while gilts outperform slightly. US yields are as much as 3bps cheaper on the day with the curve slightly steeper. 10-year near 4.11% outperforms Germany’s and trails UK’s, each by about 1bp. US session includes manufacturing PMIs and at least two Fed speakers. IG dollar issuance slate includes two items so far and is expected to grow, with underwriters anticipating $55 billion this week and around $120 billion for November; Treasury auctions resume next week with 3-, 10- and 30-year new issues. Google announced another massive, 8-part debt deal as the funding scramble to use debt to pay for datacenters continues.
In FX, the Bloomberg Dollar Spot Index is steady while the Swiss franc is the weakest of the G-10 currencies, falling 0.3% against the greenback. Spot gold slips back below $4,000/oz.
In commodities, oil prices are near flat after giving up earlier gains seen after OPEC+ said it planned to pause output increases in the first quarter of 2026. WTI crude futures are just below $61 a barrel. Gold trimmed early gains but remained above $4k as haven demand faded, while the dollar held steady. On Friday, China ended a gold tax break, in a setback for consumers in one of the world’s top bullion markets.
Today's economic calendar slate includes October S&P Global US manufacturing PMI (9:45am) and October ISM manufacturing (10am); US government data continue to be postponed by shutdown that began Oct. 1. Fed speaker slate includes Daly (12pm) and Cook (2pm)
Market Snapshot
- S&P 500 mini +0.3%
- Nasdaq 100 mini +0.5%
- Russell 2000 mini little changed
- Stoxx Europe 600 +0.4%
- DAX +0.8%
- CAC 40 little changed
- 10-year Treasury yield little changed at 4.08%
- VIX +0.4 points at 17.8
- Bloomberg Dollar Index little changed at 1221.48
- euro -0.2% at $1.1515
- WTI crude little changed at $60.96/barrel
Top Overnight News
- The Trump administration has begun detailed planning for a potential new mission to send U.S. troops and intelligence officers into Mexico to target drug cartels. NBC
- More than 735,000 New Yorkers cast early ballots ahead of Tuesday’s mayoral election, the highest ever early in-person turnout for a nonpresidential vote in the city. NYT
- US Democratic and Republican Senators are talking and focused on finding agreement on FY26 spending bills; the hope being that a spending agreement could help to resolve the shutdown. On spending, talks continued over the weekend and there is some optimism around a resolution. However, there are no signs from Trump/Republicans around giving ground on extending the expiring premium Obamacare subsidies: PunchBowl
- Fed’s Miran (voter) warned that the Fed risks a recession if it doesn’t cut rates rapidly: NYT
- President Trump says that Chinese President Xi Jinping has given him assurances that Beijing would take no action toward its long-stated goal of unifying Taiwan with mainland China while the Republican leader is in office. CNBC
- Trump threatened to take military action in Nigeria and cut off US aid if the government doesn’t halt militants’ “killing of Christians.” The country’s dollar bonds tumbled, suffering the biggest losses across emerging markets. BBG
- Trump urged Senate Republicans to terminate the filibuster rule. Trump separately commented that they will ask the courts how they can legally fund SNAP benefits as soon as possible.
- Bessent said the Trump administration will not appeal the judge’s ruling on SNAP benefits, while he also commented that the Fed should be cutting rates if inflation is dropping, according to an interview with CNN.
- NVDA’s most advanced chips will be reserved for U.S. companies and kept out of China and other countries, U.S. Trump confirmed in 60 Minutes last night. RTRS
- A private gauge of China’s manufacturing activity showed Chinese factories continued to expand production in October, albeit at a slower pace, signaling weaker growth momentum heading into the fourth quarter of the year. China’s RatingDog manufacturing PMI for Oct came in at 50.6, down from 51.2 in Sept and a bit below the consensus forecast of 50.7. WSJ
- China is seeking to buy US wheat in what would be the first purchase in more than a year, following last week’s trade truce between the two nations. BBG
- China will suspend implementation of additional export controls on rare-earth metals and terminate investigations targeting US companies in the chip supply chain, the White House said. BBG
- Microsoft and Alphabet plan more deals to build out their AI infrastructure. Microsoft signed a $9.7 billion agreement to buy cloud capacity from Australia’s IREN, giving it to access more Nvidia chips, while Alphabet plans to raise at least €3 billion in a debt offering, a person familiar said. IREN also said it agreed to buy equipment from Dell for $5.8 billion. Shares of both firms jumped in premarket trading. BBG
Trade/Tariffs
- US President Trump commented on Friday about China, in which he stated that he would love to get rid of the extra 10% tariff and that the meeting with China was incredible, while he believes the deal with China will be long-lasting. It was also reported that US President Trump told Chinese President Xi that chip sales are "between you and NVIDIA".
- US President Trump said the US will not let China have NVIDIA's (NVDA) most advanced chips, while he also commented that he will not attend Supreme Court tariff case arguments and doesn't want to do anything to deflect the importance of that decision. Furthermore, Trump posted that the case on tariffs is one of the most important in the history of the country, and if a President is not allowed to use tariffs, the US will be at a major disadvantage against all other countries throughout the world, while he warned if they lose the decision, the US could be reduced to almost third-world status.
- US Treasury Secretary Bessent said China has shown itself to be an unreliable partner in many areas, while he also commented, “we’ll see” if a 10% tariff will be enacted on Canada after the Reagan advertisement, and he is not planning on going to the Supreme Court arguments on trade policy on Wednesday, according to CNN.
- China’s Commerce Ministry said it will consider exemptions for the Nexperia chip export ban. It was separately reported that Nexperia’s Dutch headquarters said it welcomes announcements lifting the block on shipping chips, while the Dutch government said that China talks continue regarding a constructive way forward in Nexperia.
- Chinese President Xi proposed that China and South Korea properly manage differences through friendly consultations, while he called for the sides to strengthen strategic communication and consolidate the foundation of mutual trust. Xi also called for deepening China and South Korea cooperation in emerging sectors such as AI and biopharmaceuticals, as well as urged South Korea to work with China to practice true multilateralism and safeguard the multilateral trading system.
- South Korea’s presidential office said South Korea and China signed 7 MOUs, including a currency swap. It was also reported that a South Korean presidential adviser said they agreed with China to cooperate on stabilising supply chains and will continue working-level communication on China’s ban on Korean culture, while South Korea and China were said to have made progress on China’s effective ban on Korean culture.
- Japanese PM Takaichi said they agreed with Chinese President Xi to build a constructive and stable relationship, while she said they reaffirmed a strong US-Japan alliance through US President Trump’s visit. Furthermore, Takaichi said they are not planning to renegotiate the USD 550bln investment package with the US even after seeing the US-South Korea package.
- Canadian PM Carney met with Japanese PM Takaichi on the APEC sidelines and discussed the potential to expand a productive economic relationship between the two countries, building on USD 32bln in annual two-way merchandise trade, while the Canadian PM’s office said they stand ready to negotiate an even better trade deal for both Canada and the US.
- China’s MOFCOM says China and the EU held in-depth and constructive talks on mutual export control concerns; both sides agreed to maintain dialogue to support stable and smooth supply chains between the economies.
- China is said to be seeking to buy US wheat for the first time in a year, according to