
Futures Rebound Lifted By Strong Amazon, Apple Earnings
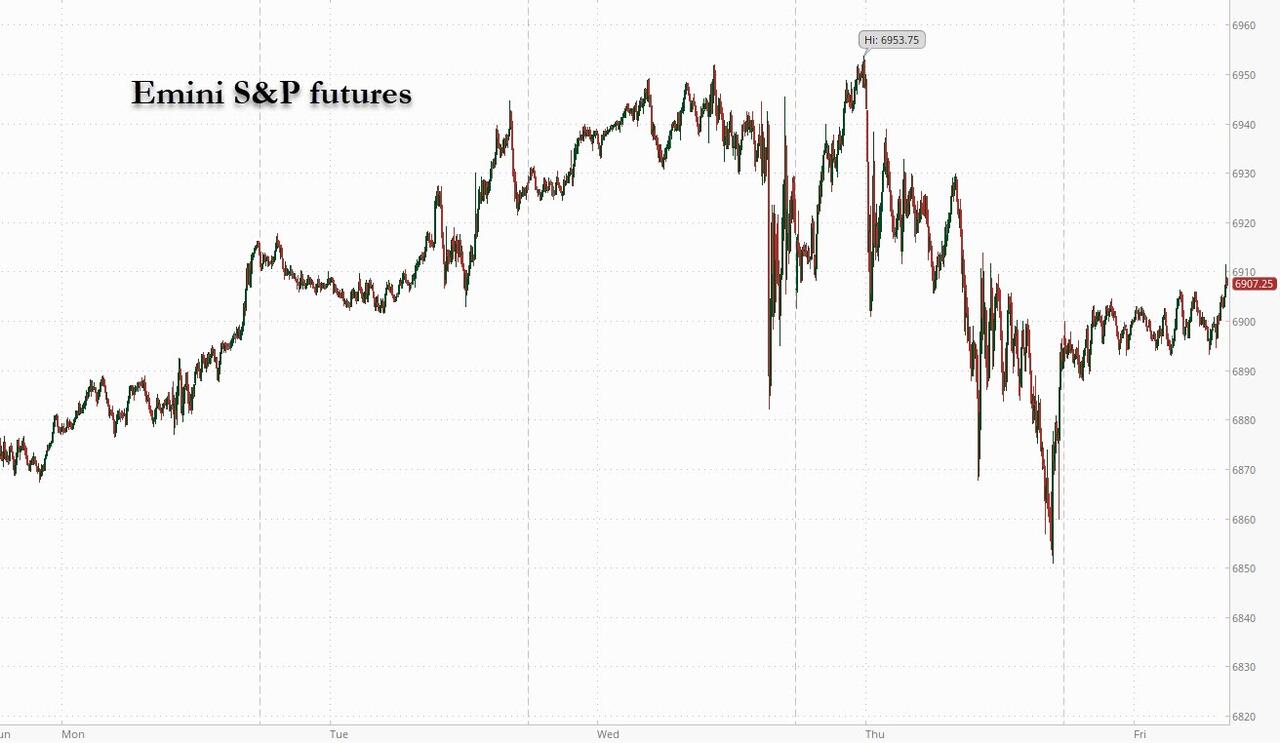
US equity futures rebound from the Thursday drop, led by Mag 7. As of 8:00am ET, S&P futures are 0.8% higher and Nasdaq futures gain 1.2%, on pace for sixth and seventh straight monthly gains respectively, with all Mag 7 names higher premarket, led by AMZN (+12.7%) and AAPL (+1.9%) after their robust earnings release (AWS sales growth of 19.7%, best since 2022 and AAPL’s revenue guidance) yesterday after-close. Europe's Stoxx 600 fell for a fourth day, putting the gauge on track for its longest losing streak since July; in Japan, the tech-heavy Nikkei 225 closed up and notched its best month since 1990. Bond yields are flat, the USD is higher. Commodities are mostly lower; copper fell -2.4%. Today's calendar slate includes October MNI Chicago PMI at 9:45am (several minutes earlier for subscribers); US government data continue to be postponed by shutdown that began Oct. 1. Fed speaker slate includes Dallas Fed President Logan (9:30am) and Cleveland Fed President Hammack and Atlanta Fed President Bostic (12pm). Both CVX and XOM reporting earnings this morning.
In premarket trading, Mag 7 stocks are all higher: Amazon.com (AMZN) jumps 12% after the company’s cloud unit posted the strongest growth rate in almost three years, reassuring investors who were concerned that the largest seller of rented computing power was losing ground to rivals. Apple Inc. (AAPL) is up 2% after the company predicted a major sales surge during the holiday season after releasing new iPhones, helping assure investors that its flagship product remains a growth engine (Nvidia (NVDA) +2%, Alphabet (GOOGL) +1.2%, Meta Platforms (META) +1.4%, Tesla (TSLA) +1.2%, Microsoft (MSFT) +0.4%)
- Brighthouse Financial (BHF) soars 22% after the Financial Times reports that Aquarian Holdings is in advanced talks to take the US life insurer private.
- Charter Communications (CHTR) falls 5% after posting third-quarter results.
- Cloudflare (NET) rises 8% after the software company forecast revenue for the fourth quarter that beat the average analyst estimate.
- Coinbase (COIN) advances 4% after the largest US crypto exchanged reported third-quarter revenue that exceeded estimates following an uptick in trading as token prices climbed to record highs.
- Dexcom (DXCM) sinks 12% after the glucose-monitor company cut its adjusted gross margin forecast for the full year.
- Floor & Decor (FND) shares are up 7% after the home products retailer reported adjusted earnings per share for the third quarter that beat the average analyst estimate.
- Illumina (ILMN) gain 6% after the gene-sequencing company boosted its adjusted profit and operating margin for the full year. Analysts note the better-than-expected results for the third quarter should help ease investor concerns.
- Netflix Inc. (NFLX) gained more than 2% in premarket trading. The company approved a 10-for-1 stock split to make its share price more accessible for employees who participate in the company’s stock option program. Separately, Reuters reported the company is exploring a bid for Warner Bros. Discovery’s studio and streaming businesses.
- Pony.ai (PONY) is up 4% after the autonomous vehicle technology company said it’s been granted Shenzhen’s first citywide permit for fully driverless commercial robotaxi operations.
- Reddit (RDDT) gains 10% after the social-media company reported third-quarter results that beat expectations and gave an outlook that is above the analyst consensus.
- Roku (ROKU) shares are down 4% after the streaming-video platform company reported its third-quarter results and gave an outlook. While analysts are broadly positive, they said the results aren’t enough to meet high expectations.
- Western Digital (WDC) rises 9% as the computer-storage company reported better-than-expected 1Q results and its current quarter forecast came in largely ahead of estimates.
In corporate news, Exxon Mobil outperformed Wall Street expectations for a sixth consecutive quarter after beginning operations at its fourth oil-production project in Guyana. Chevron beat earnings estimates as profits from the $53 billion Hess Corp. acquisition were included in the results for the first time, boosting oil production and cash flow. Nvidia CEO Jensen Huang still hopes to sell chips from the company’s Blackwell lineup to customers in China, though he has no current plans to do so, he told reporters Friday. Millennium Management is raising $5 billion in a new fund to invest in private market opportunities.
US stock gains offered investors a respite from Thursday’s bruising session, amid lingering doubts over whether heavy AI spending will pay off. The S&P 500’s advance has increasingly relied on a group of tech megacaps – recent record highs were hit on record negative breadth – with warnings over lofty valuations following a blistering rally.
“Volatility has become a feature rather than a bug — day-to-day swings now regularly move major stocks by hundreds of billions of dollars,” said Ulrich Urbahn, head of multi-asset strategy and research at Berenberg. “The feedback loop of investor sentiment, speculative positioning, and rapid news-driven reactions amplify these moves.”
On Friday, futures rose as Amazon jumped 13% in premarket trading, a move set to add about $300 billion to its market value after reporting the fastest cloud-unit growth in nearly three years. Apple also climbed on a revenue beat and upbeat holiday forecast. Nvidia meanwhile, unveiled new partnerships with South Korea’s biggest firms, extending a global push to expand artificial intelligence infrastructure. Friday's market gains will seal the index’s longest monthly winning streak since August 2021, capping a rally that has withstood global trade tensions and geopolitical risks.
Earnings season remains top of mind with more than 60% of S&P 500 companies having reported to date, and a further 150 expected today and next week. Contrast of earnings receptions to AI spending has diverged within big tech, as investors seek quantification of how investments are benefiting related businesses. Earnings have also broadly topped forecasts, with about 80% of S&P 500 companies that have reported so far beating expectations.
According to BofA's Michael Hartnett, global equities drew $17.2 billion in inflows in the week to Oct. 29. Hartnett added that AI’s leadership remains firmly in place. Market breadth remains a concern for traders, and divergence notable between US and European equities. Michael Burry, the man who made his name shorting the US housing market, sent what appears to be a cryptic warning to retail investors about market exuberance. Equity performance in 2025 has been characterized by extreme concentration of volatility episodes, according to Barclays strategists.
“The risks are mainly flows. They have been the main driver, much more than EPS growth,” said Karen Georges, an equity fund manager at Ecofi. “If flows begin to halt on risky assets, then there will be a genuine selloff. But it’s like a black swan, you never know when it’s coming.”
On the trade front, Treasury Secretary Scott Bessent said he expects the US to return to the negotiating table with China in a year. That came after Donald Trump and Xi Jinping agreed to a tariff truce, roll back export controls and reduce other trade barriers. Xi also warned against “breaking supply chains” in his first public remarks after meeting with Trump. “A comprehensive deal still looks far away and while trade tensions have eased for the time being, they have the potential to resurface,” said Mohit Kumar, chief economist and strategist at Jefferies International.
In Europe, the Stoxx 600 fell for a fourth day, putting the gauge on track for its longest losing streak since July. Telecoms, insurance and construction stocks are dragging. Treasuries and European bonds relatively steady, with small outperformance at the short-end in gilts. Here are the biggest movers Monday:
- Puig shares rose as much as 9.8% with trading volume almost 10 times the 20-day average after the Spanish group reported better-than-expected 3Q sales and upgraded its guidance for the last three months of the year
- Fuchs shares gain as much as 12%, the most since March 2020, after the chemicals company reported a stronger-than-expected Ebit as North and South American markets improved from previous softness
- Danske Bank gains as much as 2.8%, the most in a month, after the Danish lender reported solid third-quarter numbers, with analysts flagging strong core revenues and a slight beat to net interest income (NII)
- Interpump shares rise as much as 6.8%. Equita analysts upgraded the Italian hydraulics and pumps manufacturer as they expect the stock to outperform thanks to improving margins and organic trends and see M&A opportunities
- Kongsberg shares gain as much as 4.9% after a slew of analysts upgraded the stock following the Norwegian company’s results-driven declines on Thursday, leaving the firm with no sell or equivalent recommendations
- UMG shares rise as much as 1.8% after the world’s largest record label delivered a beat on both revenue and adjusted Ebitda in the third quarter, with growth in the important subscription unit ahead of expectations
- Erste shares rise as much as 4.1% as the Austrian lender raised its net interest income growth and CET1 capital ratio guidance. The bank sees its deal to buy Santander’s Polish unit on track to close around the year-end
- Viridien shares rose as much as 26%, the biggest jump since 2020, after the French group reported operating profits well above expectations
- Scor shares fall as much as 8.2%, the most since July, as analysts grew concerned about the reinsurance company’s solvency ratio and real estate amortization after it reported third-quarter results
- Spie shares fall as much as 5.9% to the lowest since May as the France-based engineering services company’s third-quarter organic growth came up short
- AXA shares dropped as much as 2.5% after the French insurer reported nine-month results. Jefferies highlighted the Solvency II ratio as the biggest news from the results, while Citi saw the update as uneventful
- Saint-Gobain falls as much as 3.2%, to the lowest since mid-April, after reporting third-quarter like-for-like sales that missed consensus estimates, and expected to trigger small downgrades to consensus numbers
- Acerinox falls as much as 3.4% after the stainless steelmaker said fourth-quarter Ebitda is expected to be lower than in the third quarter. Analysts see potential double-digit downgrades to full-year consensus
- Elis shares fall as much as 1.2% after the French cleaning services group reported growth in Central Europe that missed estimates due to softness in Germany. This morning, the firm also said it will buy Larosé
- Drax shares fall as much as 3.7% after UBS initiated coverage of the chemicals firm with a sell rating, saying too much optimism is priced in for the shares
Earlier in the session, Asia’s benchmark also pared its monthly advance.
In FX, the Bloomberg Dollar Spot Index is little changed Friday, set to gain 1.5% in October, which would be its second monthly advance this year. USD/JPY fell to 153.65 as inflation in Tokyo rose at a faster pace in October, backing the case for a Bank of Japan rate hike. It has since reversed losses, trading little changed around 154.12. In addition to Tokyo inflation, Japan’s better-than-expected industrial output in September also supported the yen earlier. Spot hit the session low after Finance Minister Satsuki Katayama said the government is monitoring the yen with a strong sense of urgency
In rates, US Treasuries steadied after two sessions of sharply higher yields; most yields were within a basis point of Thursday’s closing levels. US 10-year around 4.105% is just below Thursday’s high; bunds and gilts in the sector keep pace. Curve is slightly steeper, widening 2s10s and 5s30s spreads by less than 1bp on the day. Price action in European bonds is similarly muted following French and euro-area inflation data for October.
In commodities, gold lower and hovering around $4,000/oz. Oil falling, with Brent short of $65/barrel. Oil set for a third monthly loss.
US economic calendar slate includes October MNI Chicago PMI at 9:45am (several minutes earlier for subscribers); US government data continue to be postponed by shutdown that began Oct. 1. Fed speaker slate includes Dallas Fed President Logan (9:30am) and Cleveland Fed President Hammack and Atlanta Fed President Bostic (12pm)
Market Snapshot
- S&P 500 mini +0.7%
- Nasdaq 100 mini +1.2%
- Russell 2000 mini little changed
- Stoxx Europe 600 -0.3%
- DAX -0.4%
- CAC 40 -0.1%
- 10-year Treasury yield +1 basis point at 4.1%
- VIX -0.8 points at 16.15
- Bloomberg Dollar Index little changed at 1218.88
- euro little changed at $1.157
- WTI crude -0.6% at $60.18/barrel
Top Overnight News
- Trump Urges Republicans to End the Filibuster to Reopen Government. WSJ
- Elon Musk’s SpaceX Set to Win $2 Billion Pentagon Satellite Deal. WSJ
- Private Credit’s Rising Pile of ‘Bad PIK’ Points to Default Woes. BBG
- A narrow Pacific waterway is at the heart of U.S. plans to choke China’s vast navy. RTRS
- China’s factory activity slumped for the longest streak in more than nine years, prompting fresh calls for greater policy support even as the country reached a trade truce with the US. BBG
- Trump's exit is Xi's cue to take centre stage at APEC. RTRS
- More Home Purchases Are Falling Through in an Uncertain Economy. WSJ
- King Charles strips brother Andrew of titles and his mansion. RTRS
- The great AI buildout shows no sign of slowing. RTRS
- Disney Channels Go Dark on YouTube TV. WSJ
- Big Tech Is Spending More Than Ever on AI and It’s Still Not Enough. WSJ
- China signals sharper pivot to consumption as imbalances worsen. RTRS
- The Japanese government is monitoring the yen with a strong sense of urgency, Finance Minister Satsuki Katayama said, sending her first clear warning on currency movements since taking on her role. BBG
- Inflation in Tokyo rose at a faster pace, supporting the case for the Bank of Japan to keep raising interest rates gradually and giving the yen a boost. BBG
- Japan’s new Prime Minister Sanae Takaichi told China’s President Xi Jinping her concerns over his country’s rare earth export restrictions in their first formal meeting, as tensions spanning from trade to security continue to simmer between the two countries. BBG
- US President Trump's administration fired Fannie Mae ethics officials, according to WSJ.
- NVIDIA (NVDA) CEO Huang told reporters that he hopes to sell the Blackwell chip to China, but as it stands there are no plans to do so. Sales were not a topic of discussion during the meeting with China's Council for the Promotion of Trade. Co. has been growing quickly, but in the last six months this has accelerated "quite substantially".
Trade/Tariffs
- Chinese President Xi called for safeguarding multilateral trade at the APEC summit and urged members to practice true multilateralism, while he called on APEC to keep industrial and supply chains smooth and stable. Xi said APEC should promote an open regional economic environment and called for promoting trade and investment liberalisation, as well as urged members to jointly promote the digitalisation and greening of free trade.
- China's top trade negotiator Li Chenggang said they will conduct studies on international standards, economic and trade rules, and continue to meet them in terms of green standards. Li said export volume of photovoltaic products exceeded CNY 200bln for four consecutive years, and that export volume of electric vehicles exceeded 2mln units for the first time last year. Furthermore, he said green vehicles such as locomotives have also maintained strong growth and that China will continue to adapt to the global trend of green and low-carbon development.
- South Korean President Lee said they are at a critical inflection point of change in global order, and global trade uncertainty is deepening.
- EU officials will today be informed about a visit by US Commerce Secretary Lutnick to the EU on November 24th for trade talks, via Politico.
- Japan's PM Takaichi to Chinese President Xi says she would like to confirm basic direction of Japan-China relation, including building constructive and stable ties.
A more detailed look at global markets courtesy of Newqsuawk
APAC stocks traded mixed as the region digested recent earnings releases and a data deluge at month-end. ASX 200 was flat as gains in mining, materials and resources were offset as defensives lagged. Nikkei 225 outperformed and climbed above the 52,000 level to print a fresh all-time high after recent currency weakness and the lack of immediate rate hike signals from the BoJ, while participants digested a slew of data, including a higher Unemployment Rate, hot Tokyo CPI and a rebound in Industrial Production. Hang Seng and Shanghai Comp were amid losses in tech stocks, and after Chinese Manufacturing PMI data missed expectations and showed a faster pace of contraction in factory activity
Top Asian News
- Japanese Finance Minister Katayama said discussions on lowering gasoline prices have progressed, including sources for funding, while she added that the Bank of Japan’s recent decision was extremely reasonable and that monetary policies are up to the BoJ to decide. Katayama also commented that they are recently seeing one-sided and rapid moves, as well noted, it is important for currencies to move in a stable manner reflecting fundamentals and they are closely watching foreign exchange moves with a high sense of urgency.
European bourses (STOXX 600 -0.4%) opened mostly lower and have traded with a negative bias throughout the morning. Pressure which lacks a fresh catalyst, but follows on from a tentative APAC session. European sectors hold a strong negative bias, with only a few sectors managing to hold afloat. Banks buoyed by upside in the likes of Danske Bank (+1.8%) and Caixabank (+1.4%), post-earnings. Construction & Materials is found right at the foot of the pile, pressured by losses in Saint-Gobain (-1.9%), after it missed on its Q3 revenue figure.
Top European News
- ECB's Rehn says keeping interest rate unchanged is justified due to uncertainty about inflation outlook in the coming years. The impact of tariffs on inflation appears to be disinflationary.
- ECB's Muller says economic situation has gradually improved and current interest ra