
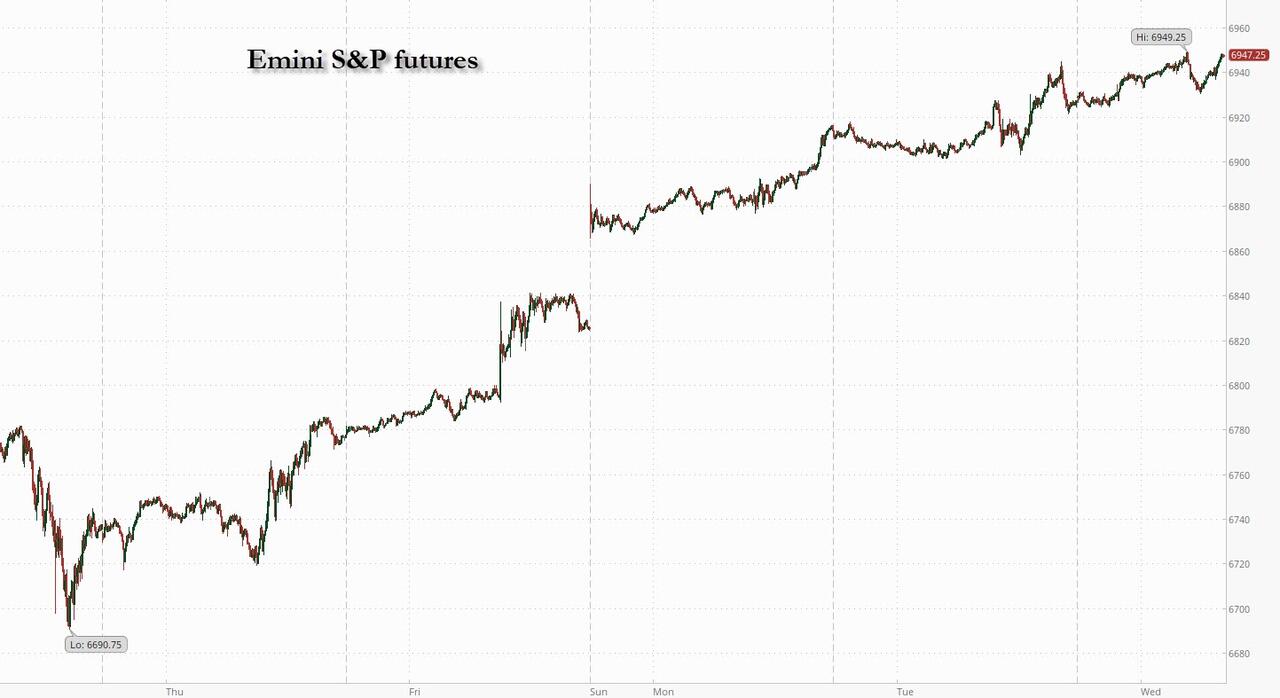
Futures Push To New Record, Nvidia Above $5 Trillion Ahead Of Fed Rate Cut And Mag 7 Earnings
With the year-end performance chase officially open…
remove the almost https://t.co/wECpqhB3sL pic.twitter.com/3A7iAxOIjV
— zerohedge (@zerohedge) October 29, 2025
… US futures march higher into today's Fed and Mag7 earnings (GOOG, META, MSFT adding up to more than $9TN in market cap) on relentlessly positive AI news, optimism about trade and expectations of a cut from the Fed later. As of 8:00am ET, S&P futures are up 0.3% and Nasdaq futures gain another 0.5%, with both indexes in record territory. Nvidia rose 3% premarket after Trump said he’ll discuss its Blackwell processors with China’s Xi Jinping (during their 3 hour meeting confirmed for tomorrow morning), setting the AI giant on course to become the first public company worth $5 trillion when it opens for trading. There are also reports that the US-China deal will include a reduction in the fentanyl tariffs from 20% to 10%, boosting overall sentiment. All Mag7 names are higher with Semis also bid. Bloomberg reported that China is set to purchase its first cargoes of US soybeans this season, while Trump also said that US and SKorea have reached a trade deal. Cyclicals are mixed despite a rebound in Metals / Miners abut Defensives are being dragged lower by Staples. Commodities are mixed but Precious / Base Metals are rallying after gold / silver look to form a level after correcting 10% and 15% (gold trading back over $4000) while copper hit a record above $11K amid a series of supply setbacks at leading mines. Bond yields are up 1bps across the curve and the USD is bid for the first time this week. Today's big event is the Fed decision as well as earnings by 3 of the Mag 7; we also get September pending home sales at 10am.
In premarket trading, all Mag 7 stocks are all higher: Nvidia is up 4% after US President Donald Trump said he’ll discuss the chipmaker’s Blackwell artificial intelligence processors with Chinese leader Xi Jinping, putting the company on track to become the first $5 trillion business by market value (Apple +0.3%, Tesla +0.9%, Alphabet +0.2%, Microsoft +0.4%, Meta Platforms (META) +0.1%, Amazon (AMZN) + 0.1%.
- Avantor (AVTR) tumbles 17% after the maker of laboratory supplies reported net sales for the third quarter that fell short of the average analyst estimate. The firm also recorded a non-cash goodwill impairment charge of $785 million related to its Distribution reporting unit.
- Bloom Energy (BE) gains 18% after the company reported adjusted earnings per share for the third quarter that beat the average analyst estimate.
- Caterpillar Inc. (CAT) rises 4% after posting higher third-quarter revenue, with its energy and transportation business boosting earnings amid rising demand for equipment needed to fuel data centers for artificial intelligence.
- Enphase Energy (ENPH) declines 11% after the firm’s fourth-quarter revenue forecast missed the average analyst estimate. Several price target cuts from analysts including JPMorgan and Evercore.
- Etsy (ETSY) falls 9% after the online marketplace company reported its third-quarter results. It also named Kruti Patel Goyal, currently chief growth officer, to the CEO job, effective Jan. 1.
- Fiserv (FI) tumbles 27% after it slashed its outlook for full-year earnings and said it’s overhauling its top leadership committee.
- Generac (GNRC) plunges 9% after the power-equipment company cut its adjusted Ebitda margin and net sales growth forecast for the full year. The firm also posted adjusted profit and net sales for the third quarter that fell short of expectations. .
- Mondelez (MDLZ) is down 5% after the snack-food company cut its adjusted earnings per share forecast for the full year.
- Seagate Technology (STX) is up 5% after the computer hardware and storage company reported first-quarter results that beat expectations and gave an outlook.
- Stride Inc. (LRN) tanks 42% after the online education company gave an outlook that was much weaker than expected, prompting a downgrade. The company cited technical issues during the rollout of a new learning management system that fueled student withdrawals.
- Teradyne (TER) rises 20% after the company forecast adjusted earnings per share for the fourth quarter above the average analyst estimate.
- Varonis Systems (VRNS) plunges 29% after the data-security software company’s updated full-year revenue forecast came in below the average analyst estimate. It also reported third-quarter revenue that missed expectations.
Traders are gearing up for two pivotal days featuring a Fed decision, US-China trade talks, and earnings from five of the Magnificent 7, while Nvidia is set to be the world’s first $5 trillion public company. NVDA haares rallied after Trump said he expects to discuss Nvidia’s flagship Blackwell AI chip in Xi talks on Thursday. Trump also said he expects to lower tariffs the US imposed on Chinese goods over the fentanyl crisis as leaders of the world’s biggest economies seek to ease tensions in a meeting on Thursday. Meanwhile, China was reported to purchase first cargoes of US soybeans this season.
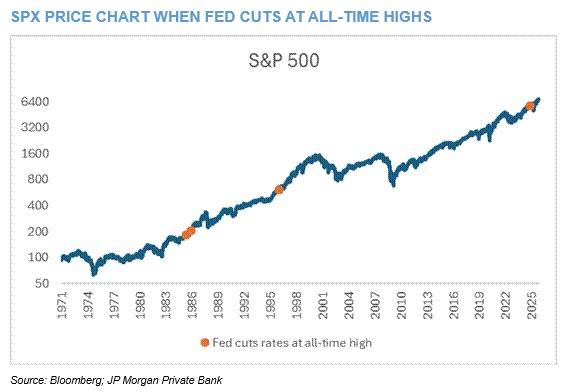
Looking ahead, JPMorgan this morning reminds us that "today will be the fifth time that the Fed cuts rates with the S&P 500 at all-time highs. All prior instances the S&P 500 was higher a year later with an average return of 20%. The worst one-year return was a 15% gain which occurred last year."
In other trade news, Trump said he had reached a deal with South Korea, though he later tempered the comment by saying the agreement was close to being finalized. Futures on South Korea’s Kospi 200 stock index rose.
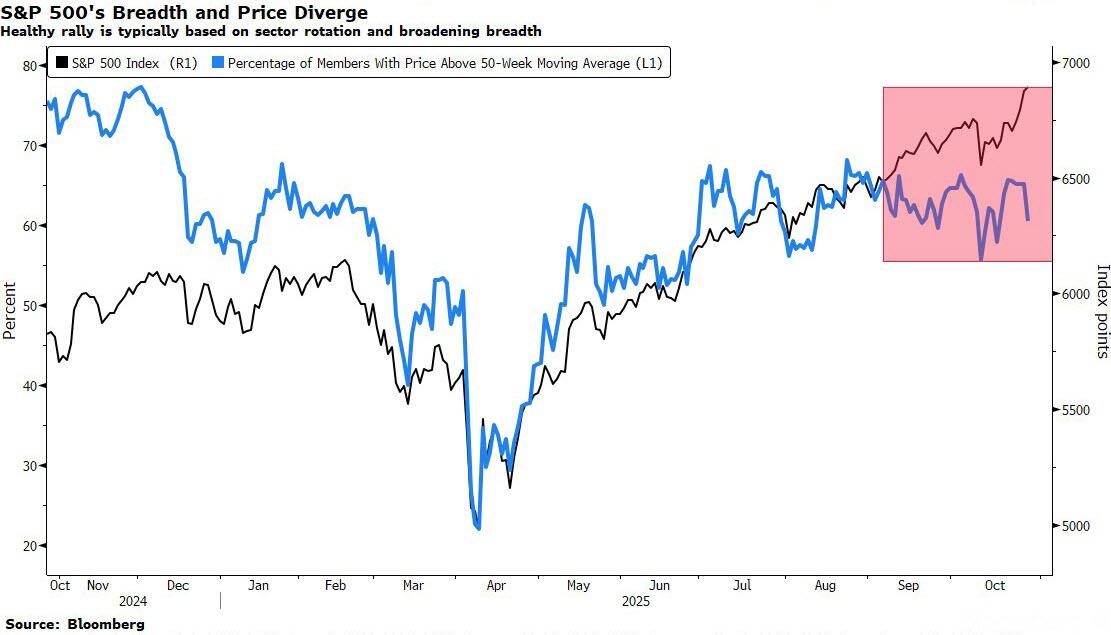
There are some clouds in the sky: the breadth of the S&P 500’s gain on Tuesday was the narrowest since at least 1993, replicated overnight by Japan’s benchmark Nikkei 225, adding to the theme of concentration with a strong gain generated by a relatively low number of advancers. BofA technical analyst Paul Ciana notes “the ghosts and goblins of Sept-Oct are fading away as we head into the most wonderful time of year,” while cautioning healthy bull markets are built on breadth and rotation “both of which have waned.”
“From an investment standpoint, while the narrative for US equities remains ‘bullish with conviction,’ sustaining this uptrend will require patience and disciplined risk management,” wrote Linh Tran, market analyst at XS.com. “Monetary policy decisions, trade developments, and corporate earnings are set to become the key catalysts driving the next phase of the market.”
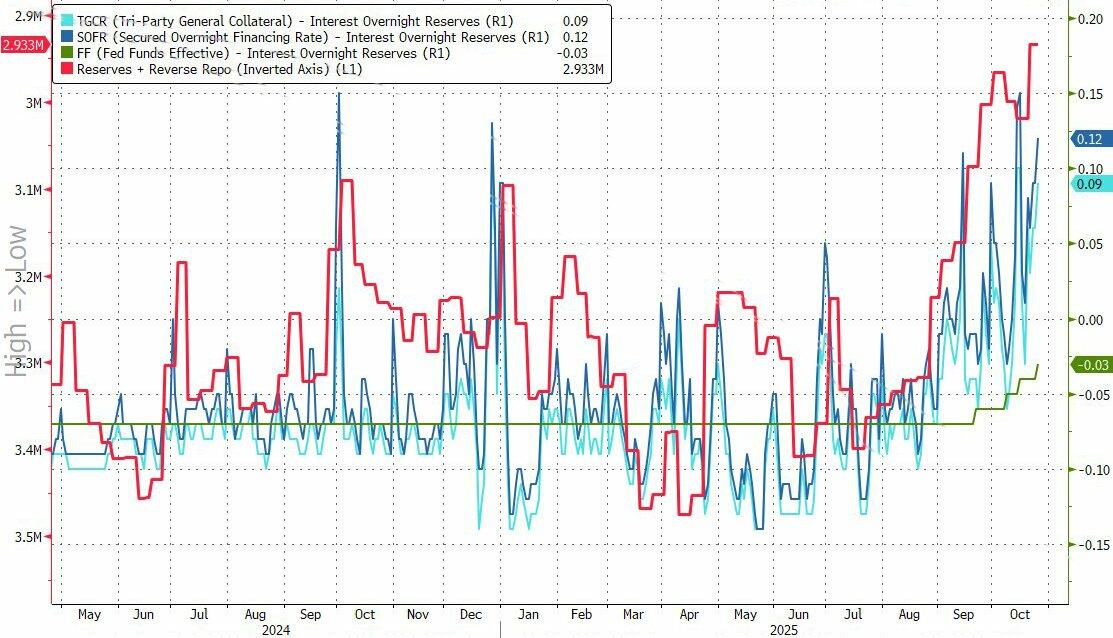
Turning to the main event, the Fed is set to cut by 25 basis points, and is likely to announce an end to Quantitative Tightening (QT) as there are increasing signs that bank reserves in the last two weeks have transitioned from an “abundant” to an “ample” level – the stopping point for QT, according to guidance from Powell (our full preview is here).
“The decisive factor will be Powell’s press conference and how he assesses the current situation with regard to the labor market, because we are not getting any real data at the moment due to the government shutdown,” said Unicredit strategist Christian Stocker. “The economy will continue to develop solidly if we get some interest rate cuts next year. That would certainly be very, very decisive for the stock market.”
Besides the Fed, attention will be on the first batch of Mag 7 companies reporting after the close including GOOG, META, MSFT (full preview to follow). We also get earnings from ServiceNow, Starbucks, Chipotle, KLA, and eBay after the close. So far earnings season is very strong: of the 197 S&P 500 companies that have reported so far in the earnings season, 85% have managed to beat analyst forecasts, while 14% have missed. Boeing, Caterpillar, CVS, Fiserv, Phillips 66 and Verizon are among companies expected to report results before the market opens. Analysts have noted that, while tariffs and subdued demand have weighed on 2025 profitability, strong backlogs should provide Caterpillar a cushion, and tailwinds in power generation should support growth in the coming years.
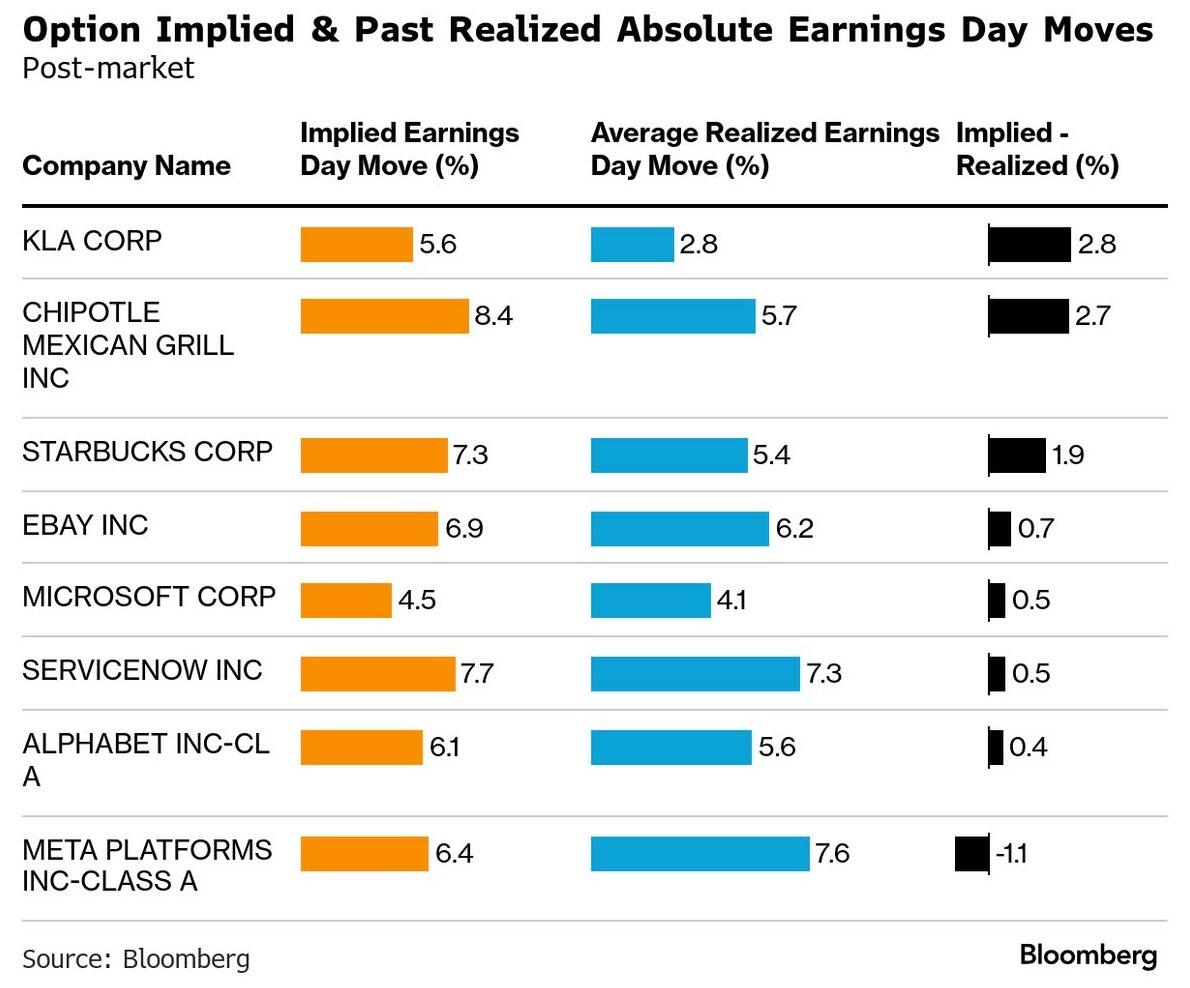
The Magnificent Seven are projected to post third-quarter profit growth of 14%, nearly double the 8% expected for the broader S&P 500.
“The story of AI is still intact,” said Anthi Tsouvali, a multi-asset strategist at UBS Global Wealth Management. “The fact that the Fed is cutting rates — and we do expect that the Fed will cut another 25 points — is very good for the economy. It’s easing financial conditions, boosting growth.”
In Europe, the Stoxx 50 also at a record after copper hit an all-time high on the London Metal Exchange. The metal — a bellwether for global growth — has surged as the US and China move closer to a trade deal. Automakers also gained after Mercedes-Benz Group AG’s upbeat earnings signaled confidence in its cash generation despite trade hurdles. Among other movers in Europe, Glencore Plc rose after saying it’s on track to hit full-year production targets. Banco Santander SA and Deutsche Bank AG gained after earnings beats. Adyen NV surged after the payments solutions company exceeded analysts’ revenue estimates. UBS Group AG fell on legals risks arising from a Swiss court ruling. Here are the biggest movers Tuesday:
- Deutsche Bank shares rose 4.6%, the best performer on the Stoxx 600 Banks Index, after the German lender beat estimates as revenue from fixed-income trading exceeded analysts expectations
- Temenos shares jump as much as 16%, the most in three months, after the software company reported beats across metrics in its third quarter and raised its Ebit forecast for the full year
- Neste shares gain as much as 9.7%, the most since July, after the Finnish energy group reported its latest earnings. Analysts highlight a strong Ebitda beat, and while the renewables segment performed well
- Sweco soars as much as 13%, the most since May 2024, after the Swedish engineering consultancy delivered third-quarter Ebita ahead of expectations
- Straumann shares rise as much as 10%, the most in over six months, after the dental implant maker reported organic growth ahead of expectations in the third quarter
- Mercedes-Benz shares rise as much as 7.9% to their highest intraday since March after the German carmaker confirmed its full-year outlook and said it plans to proceed with a €2 billion share buyback
- Next shares rise as much as 7.5% after the British clothing and homewares retailer boosted its profit guidance for the fourth time this year, to a level ahead of estimates and analysts say results were “impressive”
- OMV gains 3% after the Austrian oil and gas company reported its latest earnings, which analysts say is a solid showing, with a quarterly beat driven by an outperformance for its Fuels & Feedstock division as refining strength
- Moncler shares fell as much as 4.6% after the company reported “lackluster” third-quarter sales, according to Oddo BHF, whose analyst noted the Italian luxury group’s cautious tone for the rest of the year
- UBS shares declined as much as 2.4%, reversing earlier gains of much as 4%, after investor focus turns to potential legal risk from a Swiss court ruling canceling the controversial writedown of Credit Suisse bonds
- Epiroc falls as much as 8.1%, the most since July, after the Swedish mining equipment maker reported disappointing 3Q, with analysts flagging continued margin struggles and the print coming up short against elevated expectations
- Nordic Semiconductor shares fall as much as 8.8% after the chipmaker gave a 4Q sales guidance that met analyst estimates, but failed to inspire investors that had already pushed the stock up over 60% this year prior to the result
- Telenor shares drop as much as 4.9% after the telecom operator reported results that met expectations but flagged several risk factors in Asia, including an upcoming spectrum renewal at the Grameenphone subsidiary in Bangladesh
- SKF shares drop as much as 5.5%, pulling back from a four-and-a-half year high, after analysts at Citi said the maker of bearings and sealing systems pointed to weaker growth in the final quarter of the year
- Electrolux Professional falls as much as 10% after the company reported its latest earnings, with DNB Carnegie flagging misses on quarterly sales and Ebitda, with the latter weighed down by continued currency headwinds
Earlier in the session, Asian stocks also advanced, boosted by the technology sector on AI-driven earnings strength, as investors awaited a meeting between Donald Trump and Xi Jinping. The MSCI Asia Pacific Index gained 0.5%, with Nvidia suppliers Advantest and SK Hynix among the biggest boosts after reporting strong outlooks. Japan’s Nikkei 225 climbed 2%, with gains also notable in South Korean and Taiwanese benchmarks. Trump arrived in South Korea, with which his administration is slated to sign a deal Wednesday on bolstering cooperation in AI and other areas. The US president will meet his Chinese counterpart Xi on the sidelines of the Asia-Pacific Economic Cooperation summit on Thursday as they look to finalize a sweeping trade agreement. Onshore Chinese equities advanced, while Hong Kong’s market was closed for a holiday. Equities declined in Australia, Singapore and Malaysia.
In FX, the dollar is strengthening after recent bout of weakness, with Bloomberg Dollar Spot Index up 0.1%. Sterling underperforms.
In rates, treasuries edge lower across the curve, underperform European bonds as markets brace for a busy session that includes Federal Reserve rate decision and ongoing Asia trade negotiations. Yields at 1bp-2bp cheaper across a slightly steeper curve, the 10-year near 3.99%, trailing German and UK counterparts by 1bp and 2bp. Fed-dated OIS contracts fully price in a 25bp rate cut for today’s policy announcement and a combined 47bp by year-end, a period including just one additional decision in December; today’s meeting is anticipated also to include guidance on Fed’s plans to stop shrinking its holdings of Treasuries. A decision on that has potential to drive outperformance by Treasuries vs interest-rate swaps, benefiting a recently popular trade.
In commodities, gold rises back above $4,000/oz and oil prices remain volatile. Brent futures holding above $64/barrel. Copper hits a new record high amid broad gains for base metals.
Looking ahead, today’s key events include the Fed and BoC decisions. Data releases feature US September advance goods trade balance, wholesale inventories, and pending home sales; UK September net consumer credit; Italy’s September PPI and hourly wages; and Sweden’s September GDP indicator. Earnings are due from Microsoft, Alphabet, Meta, SK Hynix, UBS, and others. The US will auction $30bn in 2yr FRNs. And we also have the early general election in the Netherlands.
Market Snapshot
- S&P 500 mini little changed
- Nasdaq 100 mini +0.3%
- Russell 2000 mini -0.2%
- Stoxx Europe 600 +0.1%
- DAX little changed
- CAC 40 little changed
- 10-year Treasury yield +1 basis point at 3.99%
- VIX -0.1 points at 16.33
- Bloomberg Dollar Index +0.2% at 1212.15
- euro -0.2% at $1.1628
- WTI crude -0.3% at $59.96/barrel
Top Overnight News
- Trump said he expects to lower fentanyl-linked tariffs on China as Beijing confirmed a high-stakes meeting between Chinese President Xi Jinping and the American leader. Trump said he might discuss Nvidia’s advanced AI chips with China soon. CNBC
- Trump announces trade breakthrough with South Korea on Asia trip: RTRS
- Trump said he threatened India and Pakistan with 250% tariffs to help spur the resolution of their conflict earlier this year. BBG
- China has started purchasing American soybeans according to Reuters, a sign of easing trade tensions between Washington and Beijing. RTRS
- Trump said they have secured commitments of over $18tln in new investments and that probably USD 21tln–22tln of investment is coming into the US by the end of the second term. Trump said he expects 4% GDP growth next quarter and that factories are booming in the US, while he commented that they will not have the Federal Reserve raising rates.
- The Republican-led Senate on Tuesday delivered a rare bipartisan rebuke of President Trump in a vote to terminate the emergency powers he has used to set tariffs on Brazil, part of a larger push to rein in the administration's efforts to install trade barriers. This may prove to be just symbolic since Speaker Mike Johnson