
Futures Rise Ahead Of Key CPI Print
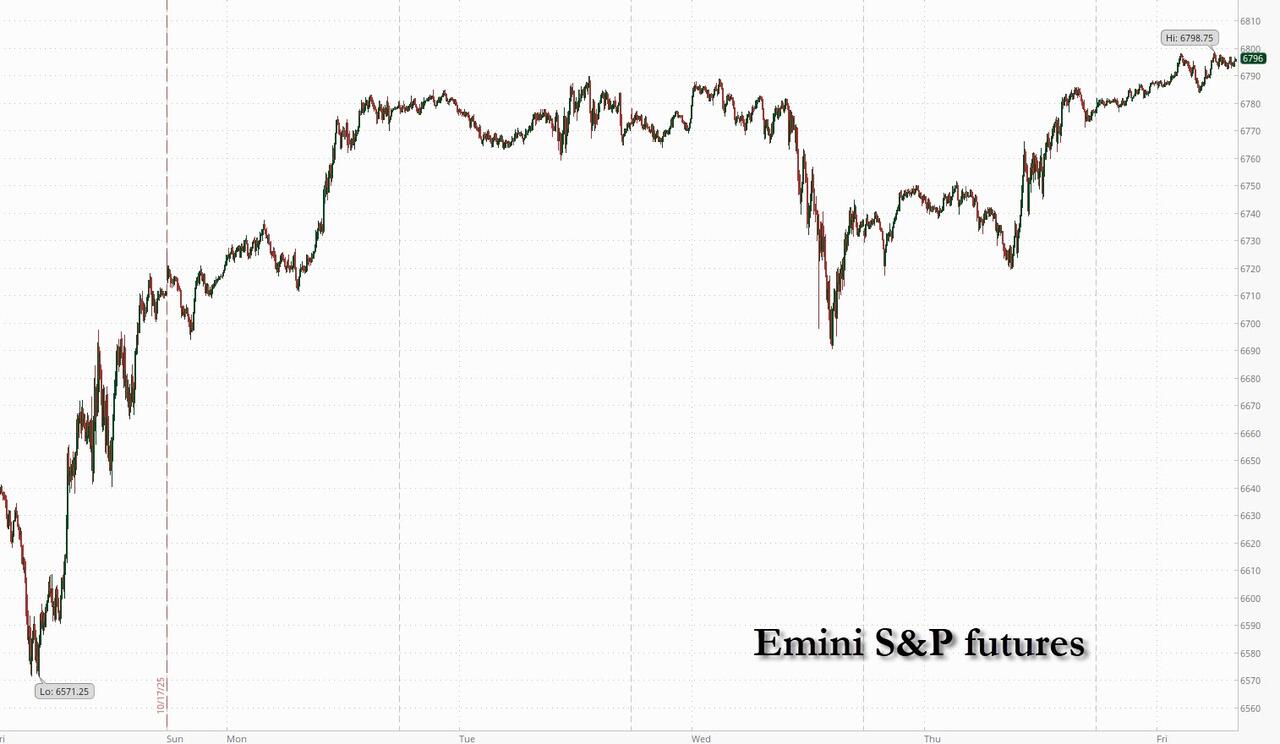
US equity futures are higher ahead of a Trump-blessed CPI print that is broadly expected to print in line or lower than expected, with optimism growing the meeting planned for next week between Trump and Xi will succeed in reducing trade tensions. With the wait nearly over for inflation data that’s will be key for the Fed’s to justify a rate cut next week, as of 8:00am S&P futures are 0.3% higher and Nasdaq futures gain 0.4%. Pre-market, Intel soared 8% after an upbeat revenue forecast. Ford gained 3% after signaling it will largely bounce back next year from a devastating fire that hobbled a key supplier. Newmont slumped after the precious-metals miner’s guidance disappointed investors.Mag 7 names are mostly higher led by GOOGL and NVDA. 10Y bond yields are fractionally higher, just above 4.0% as the USD trades near session highs. Commodities are mixed: base metals are outperforming, while precious metals are lagging and gold slides by about $100 to $4,050. Incremental macro news since Thursday’s close were mostly muted, but earnings announcements were mostly positive. Trump announced that all trade talks with Canada are finished over what he called a deceptive video ad featuring Ronald Reagan disapproving of tariffs. Today, the key focus will be CPI release at 8:30am ET and PMIs at 9:45am ET.
In premarket trading, Mag7 stocks are mostly higher (Alphabet +1.2%, Nvidia +0.6%, Microsoft +0.1%, Meta Platforms +0.4%, Apple +0.3%, Amazon -0.1%, Tesla -0.5%)
- Booz Allen (BAH) falls 8% after the defense contractor cut its adjusted earnings per share guidance for the full year.
- Deckers Outdoor (DECK) falls 12% after the owner of the Ugg and Hoka brands forecast 2026 net sales below the average analyst estimate. Analysts note the management annual outlook might be conservative.
- Ford Motor Co. (F) climbs 4% after the company reported third-quarter results that included a beat on profit and as traders weigh a 50,000 unit boost to pickup truck production against a $1.5 billion-$2 billion hit to Ebit from the Novelis aluminum plant fire.
- HCA Healthcare (HCA) rises 2% after boosting its revenue forecast for the full year
- Intel (INTC) gains 7% after the chipmaker returned to profitability and gave an strong revenue forecast, indicating signs of a comeback gaining traction.
- Mohawk Industries (MHK) falls 4% after the flooring manufacturer provided a disappointing fourth quarter earnings outlook.
- Newmont (NEM) is down 7% after the precious metals miner guided attributable gold production for 2026 that’s expected to be within the same guidance range provided for 2025.
- NEXTracker (NXT) is up 13% after the renewable energy equipment company reported adjusted earnings per share for the second quarter that beat the average analyst estimate.
- Procter & Gamble (PG) climbs 2% after reporting better-than-expected sales for its latest quarter as consumers snapped up the company’s Gillette razors and Secret deodorant.
Overnight, Trump said he is halting all trade talks with Canada for its “egregious behavior” over an ad comprising clips from a 1987 address by former President Ronald Reagan in which he defended free trade and slammed tariffs as an outmoded idea. At the same time, Trump has already been talking up the prospects for a trade deal with China, dangling an extension to the pause on higher tariffs on Chinese imports in exchange for a resumption of China’s purchases of American soybean, a crackdown on fentanyl and Beijing backing off restrictions on rare-earth exports. China’s Commerce Minister sounds optimistic, too.
Turning back to markets, Wall Street rediscovered an appetite for growth and momentum stocks, pushing indexes steadily higher during the back half of Thursday’s session. Confirmation came of a Trump-Xi sit-down next week, the first face-to-face meeting between the leaders of the world’s two biggest economies since Trump took back the keys to the White House in January.
At 8:30 a.m. markets deprived of economic data by the US govt shutdown now in its 24th day (yet with everything still working just fine) will finally get a look into the trajectory of consumer prices, which the median estimate sees rising 3.1% for both headline and core. September’s CPI report should give the Fed a green light to cut interest rates next week (see our CPI preview). Into the CPI data, Fed-dated OIS, steady over recent weeks, almost fully price in 25bp rate cuts at the October and December policy meetings
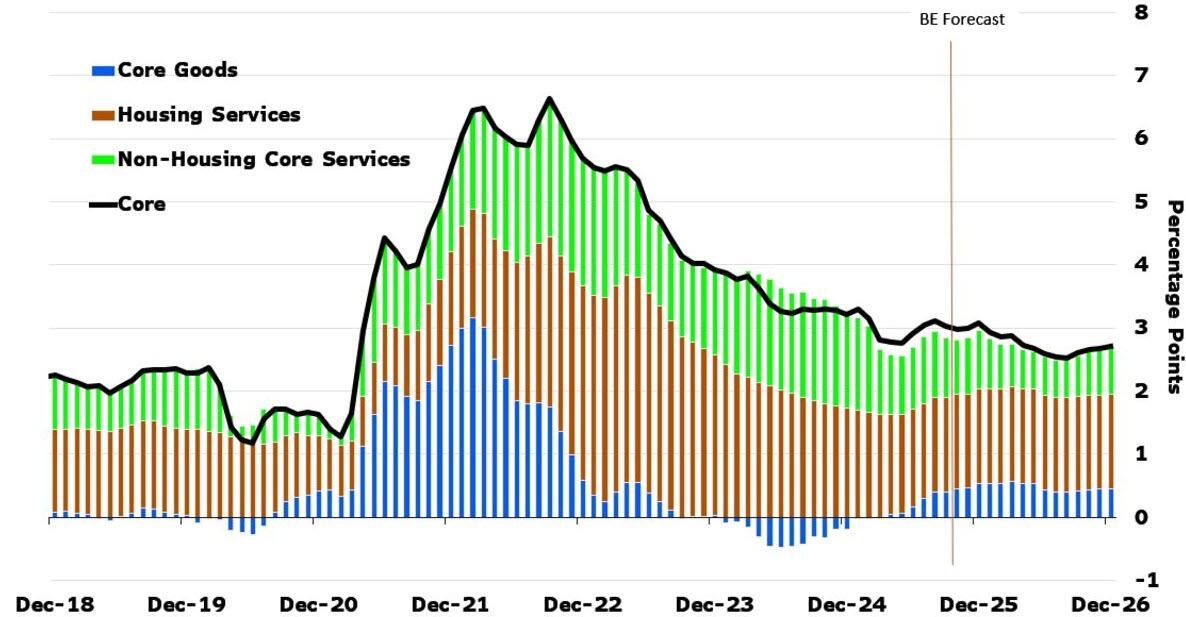
“Whatever the print looks like, it won’t deter the FOMC from delivering a 25 basis-point cut next week, or at the December meeting, even if there will probably be some knee jerk volatility as the data crosses,” said Michael Brown, a senior research strategist at Pepperstone Group Ltd.
"The risk sits firmly with a topside surprise," said Nick Twidale, chief market analyst at AT Global Markets. A soft print is unlikely to impact Fed rate cut expectations at next week’s meeting or into 2026, he said
Next week is shaping up to be the busiest of this earnings season, with companies speaking for nearly 44% of the S&P 500’s market value slated to report. With earnings season approaching its apex, just 5% of companies in the S&P 500 Index that have released earnings this season so far have cut their forward guidance, a mere fraction of the 14% that did so by this stage of the reporting cycle in the past two quarters, according to data compiled by Citigroup.
The strong earnings season so far has helped markets to ride out geopolitical and trade tensions. With nearly quarter of the reporting done, year-on-year growth in earnings-per-share has been 4% in Europe and 14% in the US, better than expected, according to Barclays Plc strategists. The real test will come with big-tech results starting next week, they said. Alphabet Inc. and Meta Platforms Inc. are slated to report on Oct. 29 and Apple Inc. the day after.
“We do not think that we are out of the volatility period and market sentiment still feels fragile,” said Mohit Kumar, chief economist and strategist at Jefferies International Ltd. “Investor positioning has shown some signs of cleanup, but overall positioning still remains on the long side. Thus, we are keeping our low-risk mode for now, while maintaining our medium term bullish view.”
Europe's Stoxx 600 reversed an opening gain, now down by 0.1%, with real estate and utilities shares leading declines, while technology and financial services stocks outperformered. Among companies reporting earnings in Europe, French drugmaker Sanofi SA, UK lender NatWest Group Plc, Swiss cement producer Holcim AG and Swedish defense firm Saab AB gained after beats, as did automobile component maker Valeo. Aluminum supplier Norsk Hydro ASA, Dutch lights manufacturer Signify NV and elevator specialist Schindler Holding AG dropped after missing analysts’ estimates. Here are the biggest movers Friday:
- Valeo shares rise as much as 8.5% to their highest intraday since May 2024 after the French firm posted revenue for the third quarter that beat estimates
- Lifco gains as much as 11% after the Swedish industrial conglomerate reported better-than-expected third-quarter earnings, with organic revenue growth of 4.9% coming in well ahead of consensus estimates of 0.2%
- Saab gains as much as 7.8%, the most since July, after the Swedish defense firm boosted its full-year sales guidance as well as posted a sales and Ebit beat in the third quarter
- Safran shares fall as much as 2.1% as the engine manufacturer’s third guidance increase this year is already largely reflected in estimates, according to analysts. The stock remains close to all-time highs
- Sanofi shares rise as much as 5.2% to the highest since May 29 after the French drugmaker reported sales and profit for the third quarter that beat market expectations
- GSK shares drop as much as 3.3% in London. FDA approval of the British pharma company’s blood cancer drug for a later-than-expected treatment line raised concerns about the medicine’s sales potential
- Kering shares drop as much as 3.6%, pulling back from the highest since April 2024 as HSBC downgrades the luxury-goods company following a strong rally in the share price
- Sika shares fall as much as 2.8% after the specialty chemicals company reported results that were “worse than feared,” with sales declining 1.2% compared to last year — the first quarterly organic decline since 2020
- Schindler shares drop as much as 2.6%, after the elevator and escalator specialist posted a drop in order intake during the third quarter, which analysts at Bloomberg Intelligence said could drag on its recovery
- Bravida falls as much as 11%, the most since May, after the Swedish building installations group reported its latest earnings. DNB Carnegie says poor margins in its core Swedish market disappointed
Earlier in the session, Asian stocks advanced, as confirmation of a meeting next week between US President Donald Trump and his Chinese counterpart Xi Jinping bolstered investor mood. The MSCI Asia Pacific Index rose as much as 0.6%, on course to end a three-day losing streak. SK Hynix, Samsung Electronics and Alibaba were among the top contributors to the advance. Most markets were in the green, with notable gains in South Korea, Japan and China. Taiwan’s market was closed for a holiday. Hopes for a thaw in trade tensions are rising ahead of a planned meeting between Trump and Xi next Thursday on the sidelines of the Asia-Pacific Economic Cooperation summit. Chinese stocks got an extra lift from the nation’s renewed emphasis on technological self-reliance at a key political gathering this week. “The plenum confirms the market expectations of the next five years, and the recent signs of deescalation from both sides is supporting risk sentiment,” said Hao Hong, chief investment officer at Lotus Asset Management in Hong Kong. Elsewhere, South Korea’s Kospi rose 2.5% to touch a fresh high on gains in its big chipmakers. Japanese stocks also rose as Intel’s bullish sales outlook lifted semiconductor-related shares, including Advantest, and optimism increased over corporate earnings.
In FX, the Bloomberg Dollar Spot Index rose 0.1%, on track for a 0.5% gain this week. Overall, the dollar was bolstered as USD/JPY rose 0.3% to 153.06, after Japan’s finance minister signaled that it may be necessary to issue additional debt to fund Prime Minister Sanae Takaichi’s upcoming economic package. USD/CAD rose 0.3%, as the Canadian dollar took a hit after President Donald Trump said he would stop trade negotiations with Canada, citing a Canadian advertisement against US tariffs.
In rates, treasuries hold small losses following Thursday’s sharp selloff triggered by jump in oil prices. US yields remain within 1bp of Thursday’s closing levels, the 10-year just over 4%, with Germany’s lagging by almost 3bp and UK counterpart outperforming slightly. European bonds are falling after resilient euro-zone PMI readings, bolstered by German private sector activity at the strongest since 2023. That overshadowed a miss for French PMIs, hit by the recent political turmoil. German 10-year yields are up by three basis points, French yields by four basis points. UK retail sales also beat estimates. Focal point of US session is the delayed September CPI release at 8:30am New York time. Next week’s Treasury auctions are on an accelerated and compressed schedule before the Oct. 29 FOMC decision, beginning Monday with 2- and 5-year notes sales and concluding with 7-year notes Tuesday
In commodities, gold prices down by $56 to $4,070/oz. Oil prices stable following the surge in the previous session, with Brent holding around $66/barrel.
US economic calendar calendar includes September CPI (8:30am), October S&P Global US PMIs (9:45am), September new home sales and October final University of Michigan sentiment (10am) and October Kansas City Fed services activity (11am).
Market Snapshot
- S&P 500 mini +0.3%
- Nasdaq 100 mini +0.5%
- Russell 2000 mini +0.4%
- Stoxx Europe 600 -0.1%
- DAX little changed, CAC 40 -0.4%
- 10-year Treasury yield +1 basis point at 4.01%
- VIX -0.2 points at 17.12
- Bloomberg Dollar Index +0.1% at 1214
- euro little changed at $1.161
- WTI crude little changed at $61.8/barrel
Top Overnight News
- Trump says talks with Canada off after ad invokes Reagan as free-trader: RTRS
- Former Bundesbank chief Axel Weber has warned the coming disruption from artificial intelligence could usher in the rise of a new global elite that profits disproportionately from the adoption of the cutting-edge technology while leaving the rest worse off" BBG
- Hobbled by US tariffs, carpet weavers in India's Kashmir struggle to stay afloat: RTRS
- After soaring as a global safe haven bet, the Swiss franc is wrapping up a volatile week against the euro with speculation the Swiss National Bank has intervened to curb the currency’s strength: BBG
- China’s New Strategy for Trump: Punch Hard, Concede Little: WSJ
- Investors Love Intel Again. That Still Doesn’t Solve Its Problems: WSJ
- Data-starved bond traders risk seeing the October rally in Treasuries spoiled by the key inflation figures they’ve been waiting for: BBG
- Strong Earnings Reassure Jittery, Data-Deprived Investors: WSJ
- White House Deputy Chief of Staff Blair made the case that, regarding the shutdown, US President Trump wants to spend time and political capital putting together a broader overhaul of healthcare. Blair says there will be a "number" of publicly traded pharmaceutical companies who’ll be “coming to the table” to “get the cost of prescription drugs down in the United States.”: Politico.
- A Turkish court dismissed a case that could topple the leader of the country’s main opposition party, offering relief to investors concerned about renewed political instability: BBG
- US states warn food aid benefits will halt if federal shutdown drags on: RTRS
- Fed has reportedly requested a formal consultation into a banking ruling around the treatment of cross-border loans for EZ banks: BBG
- JPMorgan to Allow Bitcoin, Ether as Collateral in Crypto Push: BBG
- Target to Eliminate 1,800 Roles, 8% of Headquarters Team: BBG
- Applied Materials to Cut 4% of Global Staff After Sales Slow: BBG
- Rivian Cuts About 600 Jobs in Latest Setback for EV Maker: BBG
- ConocoPhillips to Lay Off Canada Employees in November: Reuters
- Will India and China Be Able to Resist U.S. Sanctions on Russian Oil: WSJ
Trade/Tariffs
- US Trade Representative Greer is to travel to Malaysia, Japan and South Korea.
- South Korea's Industry Minister said South Korea wants the US investment package to be smaller than USD 350bln as part of the tariff deal, while it was separately reported that South Korea and the US remain far apart on key sticking points in trade negotiations, although some progress has been made, according to a senior presidential aide.
- China's Commerce Minister said regarding ties with the US, that dialogue and cooperation is the only right choice and can find a solution and correct way of coexistence. The minister also noted regarding FDI that they will not will not engage in zero-sum games in opening up and attracting investment, while they will further lower market access barriers to foreign investors.
- US President Trump posted "Canada has fraudulently used an advertisement, which is FAKE, featuring Ronald Reagan speaking negatively about Tariffs…They only did this to interfere with the decision of the U.S. Supreme Court, and other courts. TARIFFS ARE VERY IMPORTANT TO THE NATIONAL SECURITY, AND ECONOMY, OF THE U.S.A. Based on their egregious behaviour, ALL TRADE NEGOTIATIONS WITH CANADA ARE HEREBY TERMINATED."
- Canada reportedly limits how many American vehicles Stellantis (STLAM IM) and GM (GM) can import tariff-free, while the move comes after companies dropped some Canadian production, according to CBC. Canada's government later confirmed significant reductions to import quotas of General Motors (GM) and Stellantis (STLA IM), reducing the annual remissions quotas for General Motors by 24.2% and for Stellantis by 50%.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mostly higher as the region took impetus from the rebound on Wall St, where energy names were underpinned amid surging oil prices and with the improved risk sentiment also facilitated by confirmation of a Trump-Xi meeting for next Thursday. ASX 200 lagged as gains in tech were offset by weakness in defensives and the top-weighted financials sector. Nikkei 225 rallied at the open and reclaimed the 49,000 status alongside a weaker currency, while the latest CPI data from Japan printed mostly in line with forecasts but showed an acceleration in the headline and core figures. Hang Seng and Shanghai Comp conformed to the upbeat mood following confirmation of a Trump-Xi meeting next week, although gains were capped as it was also reported that the US is to probe China's 2020 trade deal compliance, while an investigation could be announced on Friday.
Top Asian News
- Chinese President Xi said China’s development is facing both strategic opportunities and challenges, while he added that China should comprehensively promote the integrated development of education, science, and technology talent, as well as strive to break through key core technologies, according to Xinhua.
- China's NDRC head said the economy relies on the real economy to move towards the future, and noted that strong domestic demand is strategic underpinning for China's modernisation. NDRC head also stated that there is room and potential for China to expand domestic demand and they will implement some major investment projects, improve the structure of government investment and increase the proportion sent to people's livelihoods. Furthermore, they will expand economic policy space during the next five years, will prevent improper government intervention in the economy and will increase coordination of macroeconomic policies.
- China's Deputy Head of Office of Financial and Economic Affairs Commission said the external environment is uncertain and unstable, b